Ensign's Third-Quarter Test: Can Core Strength Outrun Its New Texas Turnaround Drag?
The Ensign Group heads into its third-quarter report with two guidance raises already behind it this year and a stock that has gone nowhere since the last one. That gap between operating confidence and market response sets up the central question for Tuesday's release after the close: can Ensign's mature buildings keep producing enough growth to absorb a fresh batch of 20 low-occupancy acquisitions that management openly said will not add to earnings for some time?
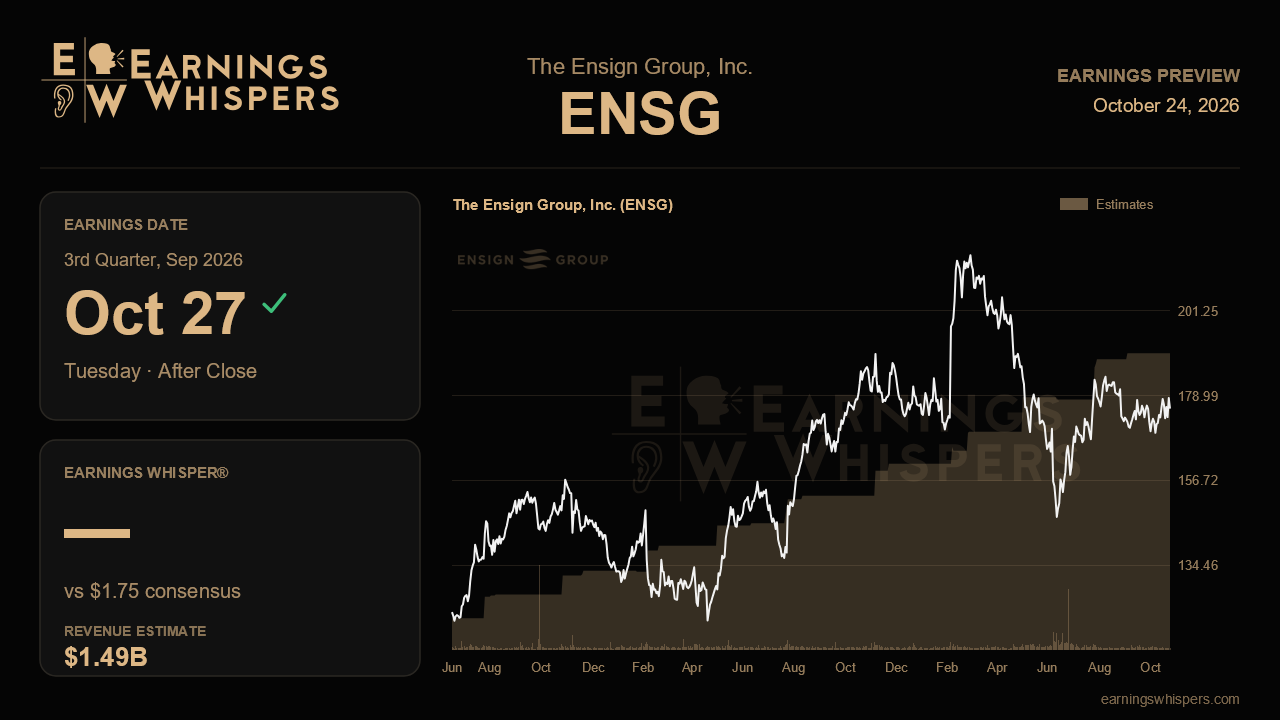
Wall Street expects earnings of $1.75 per share on revenue of about $1.49 billion. That would mean roughly 19% earnings growth and nearly 15% revenue growth from a year ago, when Ensign earned $1.47 on $1.30 billion. It would also be a modest step up from the $1.72 the company posted last quarter. These are strong growth figures for a skilled nursing operator, and they rest partly on acquisitions. Management's full-year outlook now calls for $7.75 to $7.85 per share on revenue of $5.87 billion to $5.92 billion, up from $7.48 to $7.62 a quarter earlier and from an initial $7.41 to $7.61. When that latest range came out, the full-year consensus of $7.56 sat below even its low end. Analysts were catching up to the company rather than getting ahead of it, which leaves Ensign some cushion. The flip side is that a third straight raise is now partly expected, so the bar has risen.
The operating story to test is simple. Last quarter, same-store managed care revenue rose 6.1% and skilled mix days climbed 6.2%. Those are signs that Ensign is attracting higher-acuity, better-paying patients. Same-store occupancy of 84% dipped slightly from the record 84.3% set in the first quarter. A return to new highs would ease worries that the mature portfolio is plateauing. A second consecutive slip would make the acquisition-driven growth look more exposed. Margins matter just as much. Management described them as roughly flat, with dilution from the Texas turnarounds offsetting same-store gains. If consolidated margins hold steady despite a full quarter of those 19 Texas buildings and one in Iowa, that would support the claim that the drag is manageable. Noticeable compression would suggest the ramp is costing more than the guidance assumed.
The real estate arm, Standard Bearer, is the other piece of the story. Funds from operations have risen every quarter, reaching $24.7 million, and rental revenue jumped to $44.1 million after 23 assets were added, including third-party senior living and memory care properties. Continued growth there would show the platform is diversifying beyond Ensign's own operators. Rent coverage eased to 2.4 times from 2.7 times, though, so further slippage would deserve scrutiny. Commentary on how the July changes to CMS star ratings affected quality scores, and on state Medicaid budgets heading into 2027, could shape the tone of the call as much as the quarter's numbers.
Sentiment has warmed noticeably, moving from essentially neutral before the last report to clearly positive now. The share price tells a cooler story. The stock is down 3.5% since the last report while the S&P 500 gained 2%. At about $176, it trades below its 200-day moving average near $182 and sits in the lower half of its post-earnings range of roughly $167 to $186. Investors seem to like the fundamentals but are hesitant to pay up while the new cohort dilutes results.
The report therefore hinges on whether Ensign can show that the Texas turnarounds are a temporary weight on an engine still running hard. A beat paired with steady margins, firm skilled mix and at least a reaffirmed outlook would keep the narrative of compounding execution intact. Flat margins that start to slip, or guidance left unchanged without a clear explanation, would give the market's skepticism more to work with.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-23 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-06 | |
| Oct-06 | |
| Oct-02 | |
| Oct-02 | |
| Oct-02 | |
| Oct-02 |
