Ensign Beats And Raises Again, But Slowing Revenue Growth And Turnaround Dilution Complicate The Setup
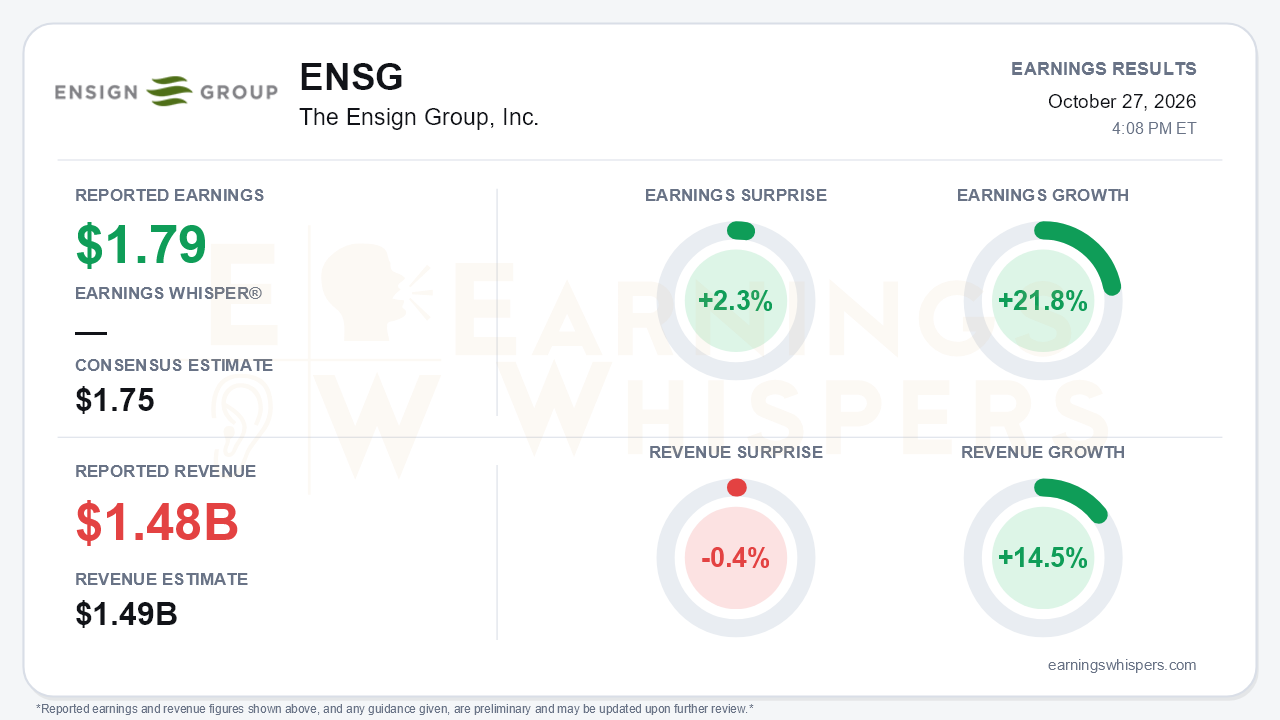
The Ensign Group delivered another earnings beat and a third consecutive increase to its full-year outlook, but the quarter also showed a clear split between profit and top-line growth. Earnings Whispers normalized EPS came in at $1.79, topping the $1.75 consensus by 2.3% and up 21.8% from a year ago. Revenue of $1.484 billion rose 14.5% but missed the $1.49 billion consensus by 0.4%. That is the central tension. Ensign is extracting more profit from its existing portfolio while its consolidated growth rate keeps cooling. Revenue growth has slowed from 20.2% in the fourth quarter of 2025 to 18.4%, 17.3%, and now 14.5%. Meanwhile, the newest acquisitions are deeper turnarounds that will take longer to contribute.
The quality of the beat holds up better than the revenue miss implies. Two company measures bracket the normalized figure. GAAP diluted EPS was $1.76, up 23.9%. Company-adjusted EPS was $2.03, up 23.8% after accelerating from 20.8% growth in the second quarter. Adjusted EBITDA rose about 26% to $190.7 million on 14.5% revenue growth, which points to genuine operating leverage. GAAP operating income climbed to $138.0 million from $96.2 million, although last year's quarter carried a $12 million litigation charge. Below the operating line, the picture was less flattering. Other income fell to $2.2 million from $10.4 million as interest income declined, and the tax provision rose faster than pretax income. Investors should also note that stock-based compensation, which the adjusted figures exclude, jumped to $19.0 million from $13.0 million.
The operating story at the mature facilities is the strongest part of the report. Same-facility skilled mix revenue rose 10.7%, Medicare revenue rose 11.1%, and managed care revenue rose 9.1%. That managed care gain was a notable acceleration from 6.1% in the second quarter. Same-facility skilled mix by revenue improved to 51.2% from 49.5%, and the Medicare daily rate rose to $812 from $787. Transitioning facilities lifted occupancy to 86.1% from 82.9% a year ago. Same-facility occupancy of 84.1% was up year over year but slightly below the first-quarter record of 84.3%. The dilution is visible in the recently acquired cohort, which posted 77.4% occupancy and a 43.2% skilled revenue mix, down from 45.6%.
On the call, management sounded more emphatic than in prior quarters. Executives described 50 to 60-plus acquisitions per year as "totally doable" and pointed to a 2027 pipeline that includes larger portfolios. The company added 22 operations during and after the quarter, including nine in Florida, and bought out properties it had leased from a public REIT for nearly two decades. Standard Bearer is becoming a more meaningful contributor. Rent reached $47.7 million, up from $44.1 million in the second quarter, and FFO rose to $27.3 million with rent coverage of 2.6x. Management was also candid about the drawbacks:
- The Florida and Texas deals are full clinical, financial, and physical-plant turnarounds expected to take a year or more to contribute.
- Texas remained non-accretive in the third quarter.
- Management itself cited Florida's litigation environment as the main historical reason it had stayed out of the state.
- Ensign's quality outperformance versus state peers narrowed slightly, to 21% from 23% on CMS quality measures and to 15% from 18% on survey results.
Guidance reflects the same split. Full-year EPS guidance rose to $7.94 to $8.02 from the $7.75 to $7.85 range set after the second quarter. The release refers to that prior range as "original" guidance, but the year actually began at $7.41 to $7.61. The new midpoint implies 21.5% growth over 2025. Revenue guidance, however, only gained a higher floor of $5.89 billion, with the top end held at $5.92 billion despite heavy deal activity. That is consistent with management's acknowledgment that slower-ramping turnaround deals have tripped up revenue projections. The balance sheet is absorbing the expansion. Cash fell to $337.6 million from $539.5 million in the first quarter after roughly $675 million of year-to-date growth spending, and lease-adjusted leverage rose to about 2x from 1.73x. Year-to-date operating cash flow of $512 million keeps that leverage manageable.
The market has not rewarded the earnings momentum. Shares at $169.50 are down 6.8% since the opening after the July report and sit about 6.6% below the 200-day moving average of $181.50. The Earnings Whispers price trend is neutral, while the AVWAP trend remains negative. Investor sentiment moved from essentially neutral to modestly positive, rising about 0.11 to 0.11. That is a constructive shift but hardly euphoric.
The bottom line is that Ensign's core engine is running hotter, with accelerating skilled-mix and managed care growth, expanding margins, and an EPS outlook raised for the third straight quarter. Bears still have legitimate ammunition in decelerating revenue, a capped revenue outlook, rising leverage, and a growing book of slow-ramping turnarounds in a litigious new state. A stock trading below its 200-day average suggests the market wants evidence that the newest acquisitions can follow the same path as the older cohorts.
Read our earnings preview for The Ensign Group, Inc.: https://www.earningswhispers.com/article/ENSG/21333
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 7 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-24 | |
| Oct-23 | |
| Oct-20 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Oct-06 |
