Choice Hotels Faces A Q3 Test Of Its Rebound As The Street Prices Above Guidance
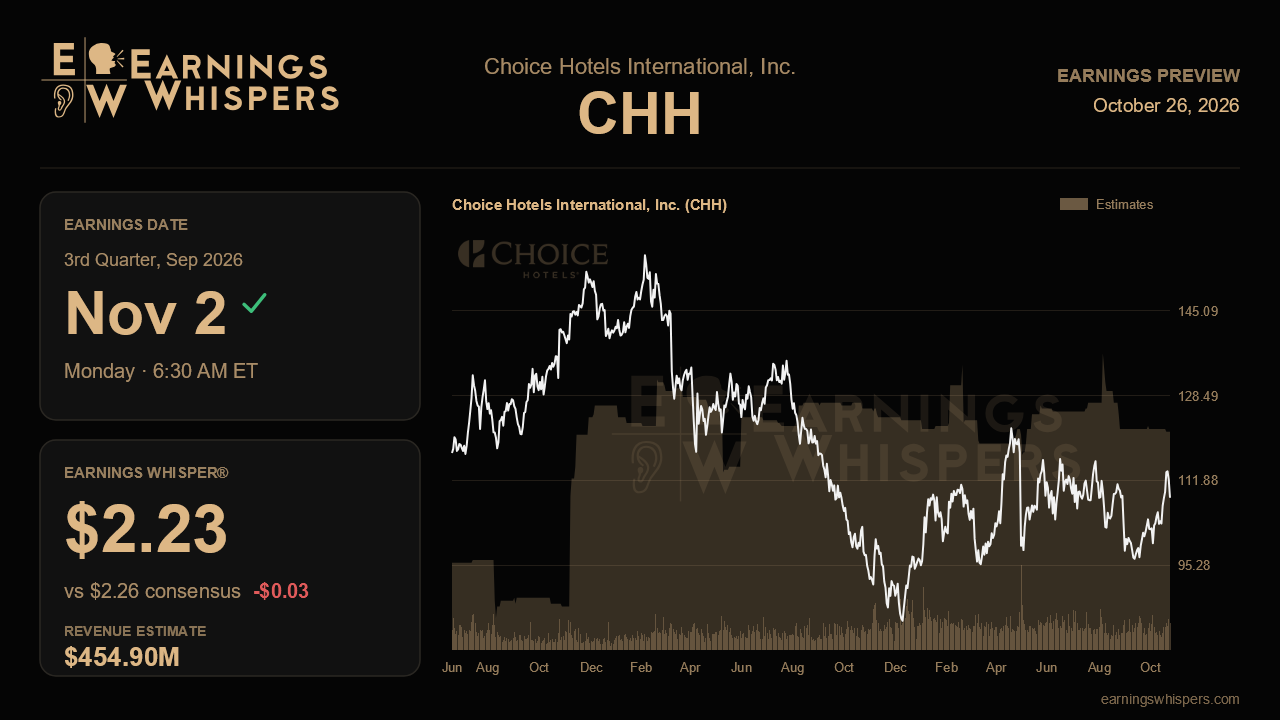
Last quarter Choice Hotels raised its outlook for adjusted EBITDA, U.S. RevPAR, net rooms growth and royalty rates, yet trimmed its full-year earnings-per-share range. That split result is the backdrop for the third-quarter report due before the open on November 2. The operating story is improving, but EPS is pressured by higher interest expense and a higher tax rate. The coming release will show which of those two forces carries more weight.
The Street expects adjusted EPS of $2.26 on revenue of $454.9 million. That would be EPS growth of about 7.6% on revenue up only 1.7%, a quarter of modest top-line expansion that relies on margin discipline and a lower share count. The Earnings Whisper sits at $2.23, slightly below consensus, so the informal bar is a touch lower than the published one. The more telling gap is on the full year. Management now guides to $6.86 to $7.10 in adjusted EPS, down from $6.92 to $7.14. Consensus of $7.14 still sits above the top of that lowered range. Either analysts expect the operating improvement to outrun the below-the-line drag, or their estimates have not fully caught up with the cut. A quarter that only lands near consensus without a firmer annual outlook could make that gap uncomfortable.
The third quarter also carries a built-in obstacle. The year-ago period included roughly $9.5 million of liquidated damages that will not recur, which makes EBITDA growth harder to show. That makes the underlying drivers especially important. U.S. RevPAR turned positive at 1.3% in the second quarter after a choppy stretch, helped by about 60 basis points from World Cup travel. Holding the new 0% to 1.25% full-year range requires demand that stays healthy without that event lift. The U.S. royalty rate has risen about 10 to 11 basis points for three straight quarters, and another gain in that range would support the pricing-power story. Choice still trails its chain-scale peers by roughly 300 basis points on RevPAR index, particularly in urban and business-transient markets. Any narrowing of that gap would be meaningful.
Unit growth is the strongest part of the turnaround and needs to hold. U.S. gross openings jumped 27% last quarter while exits fell about 50%, leaving domestic net rooms close to flat for the first time in years. Global net rooms guidance was raised to about 1.5%. Signs that exits remain low, and that the conversion pipeline, up 24%, is turning into openings, would back that higher target. The cost of that growth is visible in cash flow. First-half operating cash flow fell to $67 million from $116 million, driven by key money payments and reimbursable marketing spend, and SG&A rose 7% on the Canada franchising transition and higher receivable reserves. Steadier expenses and clearer cash generation would ease concerns that growth is being bought too expensively.
Sentiment has improved but remains negative, with bearish readings easing to about 21% from 29% before the prior report. The stock has slipped 1.4% since then, slightly better than the S&P 500. At $108.48 it sits above its 200-day moving average and roughly midway in its post-earnings range of $95.77 to $115.40, well short of a breakout. Several longer-term items, including the Business Direct small-business platform, extended-stay hotels near data centers and a planned wholly owned hotel sale in 2027, add color but are unlikely to move this quarter's numbers.
The central question is whether interim CEO Dom Dragisich can show that the operating recovery is strong enough to stabilize EPS guidance. Holding or lifting EBITDA guidance despite the tough comparison, with RevPAR and net rooms on track, would support the improving story. Another trim to EPS, or softer RevPAR once the World Cup lift fades, would suggest the Street's full-year estimates are too high.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-07 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-30 | |
| Sep-29 | |
| Sep-17 | |
| Sep-04 | |
| Sep-04 | |
| Aug-31 | |
| Aug-31 | |
| Aug-27 |
