Choice Hotels Beats As RevPAR Accelerates, But Rising Costs Limit How Much Reaches Earnings
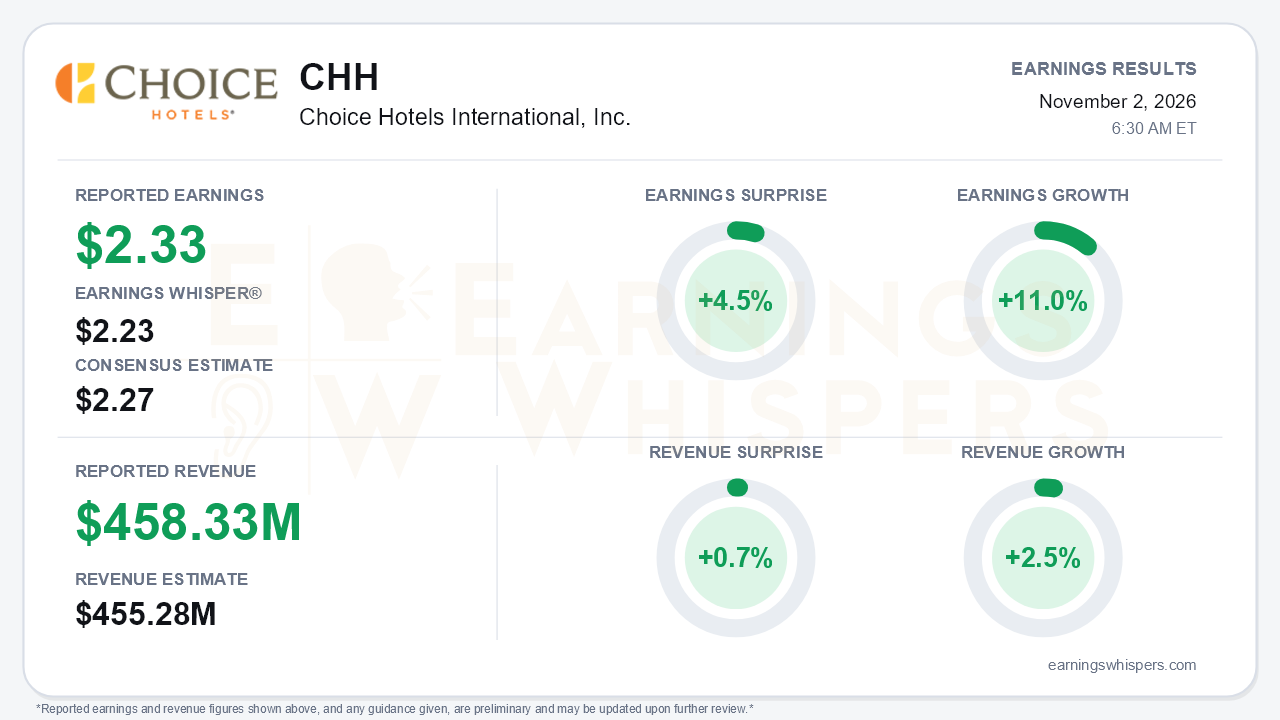
Choice Hotels delivered the kind of top-line inflection that investors have been waiting for, but the quarter also showed how much of that improvement is being absorbed before it reaches shareholders. Adjusted EPS of $2.33 beat the $2.27 consensus by 4.5% and cleared the more cautious $2.23 Earnings Whisper number. Earnings grew 11.0% year over year. Revenue of $458.33 million topped the $455.28 million consensus by 0.7% and rose 2.5%. The acceleration is real. Nine-month adjusted EPS was $5.41 versus $5.36 a year earlier, which means the third quarter reversed a softer first half. That is the central tension: demand is improving faster than management expected, yet cost growth, interest expense and cash drag mean full-year adjusted EPS guidance was only narrowed, not raised.
The quality of the beat deserves scrutiny in both directions. GAAP net income fell 68% to $58 million, or $1.28 per share. The year-ago quarter included a $100 million joint-venture gain, and this quarter absorbed a $24 million charge to terminate an option on a lease-based European hospitality business plus a $6 million impairment on two owned hotels. Adjusted EBITDA rose just 1% to $193 million. Stripping out liquidated damages ($3.3 million versus $9.5 million a year ago), however, both EBITDA and revenue excluding reimbursables grew about 5%. That is a cleaner read of the franchise engine. Franchise and management fees climbed 5% to $204 million on higher U.S. royalties, and the U.S. royalty rate expanded 8 basis points to 5.23%. Share repurchases also helped adjusted EPS outgrow adjusted net income.
The operating trajectory is the strongest part of the story. U.S. RevPAR rose 3.8%, up from 1.3% in the second quarter, driven by a 160-basis-point occupancy gain and a 1.0% rate increase. Extended stay led at 6.2%, and economy swung to 3.5% growth after declining year to date. Management said October U.S. RevPAR was up roughly 7% and now expects fourth-quarter RevPAR to exceed the third. That directly reverses the moderation it guided on the prior call. Full-year U.S. and global RevPAR outlooks were raised to 1.5% to 2.5%, from 0% to 1.25% and 0% to 1%, respectively. Adjusted EBITDA guidance moved to $641 million to $651 million, the second consecutive raise. The development story also firmed:
- U.S. net rooms growth improved for a third straight quarter to roughly flat, with management targeting about 1% by year-end.
- Third-quarter room exits fell 23%.
- U.S. franchise agreements awarded rose 24%.
- The conversion pipeline grew 29% year over year.
Bears still have legitimate ammunition. Adjusted SG&A growth, excluding Harvest Hosts, is now guided to about 9%, versus the mid-single digits promised all year. Management attributed the increase mainly to non-recurring strategic and AI-related spending and higher receivable reserves. The top of the adjusted EPS range slipped to $7.07 from $7.10 on higher interest expense and lower affiliate earnings. GAAP net income guidance was cut sharply, partly because of a roughly $135 million reimbursable marketing and reservation deficit. That deficit, together with key money tracking toward the upper end of $120 million to $130 million, helped push nine-month operating cash flow down to $122 million from $185 million. Global net rooms growth also slowed to 1.7% from 2.6% in the second quarter, and U.S. gross openings fell 8% in the period.
The forward catalysts are more tangible than they were a quarter ago:
- Capital recycling began ahead of the first-half 2027 timeline. Two owned hotels were sold for about $34 million with franchise agreements retained, and a third disposition is expected by the first quarter of 2027.
- Net development capex is expected to fall to about $20 million from $103 million in 2025.
- The roughly $130 million Harvest Hosts acquisition adds an asset-light subscription business.
- The RAISE rate-management tool rolls out this quarter.
- Dom Dragisich's appointment as permanent CEO removes a leadership question.
Investor sentiment remained negative but improved, moving from -0.29 to -0.20. That suggests skepticism is easing rather than turning into enthusiasm. The stock has gone essentially nowhere since the last report, up 1.1% from the $110 post-earnings open to $111.16. It sits 3.9% above its 200-day moving average and 3.7% below its October 21 inter-earnings high of $115.40, after rebounding 16.1% from a September low. The Earnings Whispers trend signals are mostly constructive, with momentum and AVWAP positive, although sequential growth still reads negative. That is consistent with a business whose revenue is improving faster than its profit flow-through.
The bottom line is that Choice's call preserved and strengthened a credible recovery story in RevPAR, net rooms and asset-light execution. The earnings leverage from that recovery is being diluted by elevated SG&A, financing costs and cash drag. Investors who already bid the stock up from its September low now need evidence that the 2026 spending is truly non-recurring and that faster top-line growth will reach EPS in 2027.
Read our earnings preview for Choice Hotels International, Inc.: https://www.earningswhispers.com/article/CHH/21342
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours | |
| Oct-26 | |
| Oct-07 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Oct-01 | |
| Sep-30 | |
| Sep-30 | |
| Sep-29 |
