Tower Semiconductor's Photonics Boom Faces A Skeptical Market As Stock Slumps Toward Lows
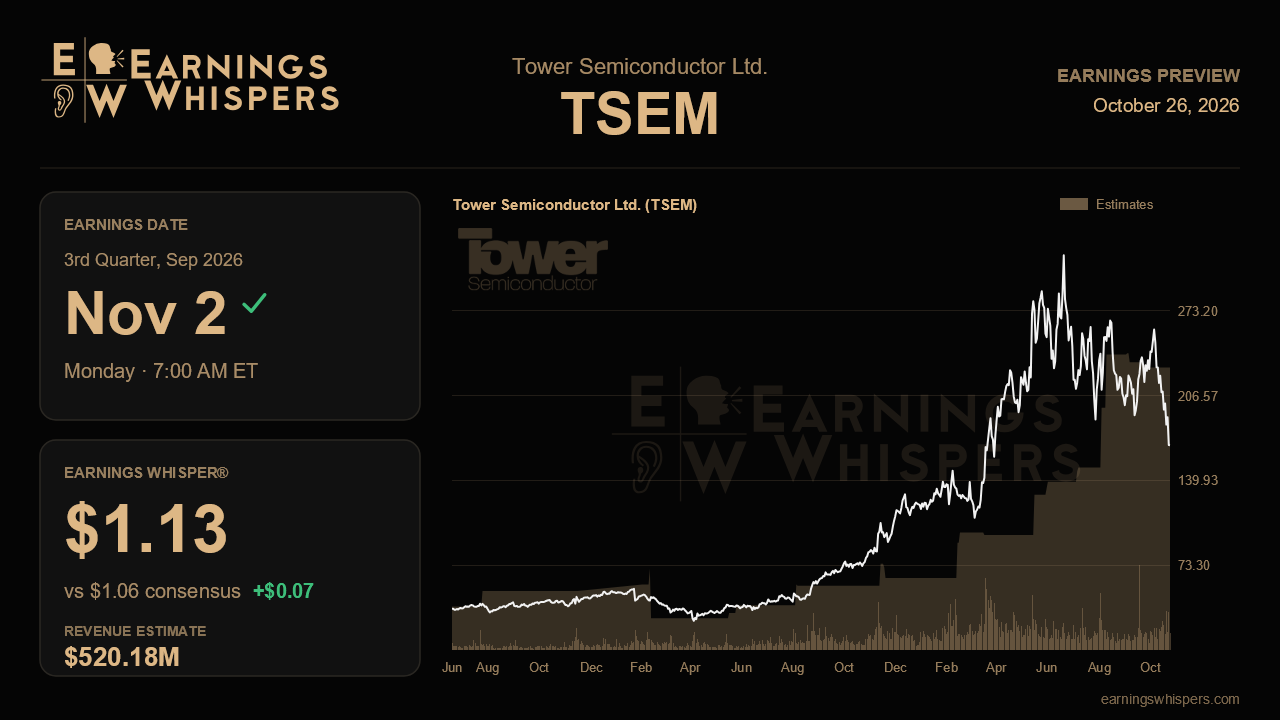
Few semiconductor companies came out of their last report sounding more confident than Tower Semiconductor, and few stocks have been treated more harshly since. Management delivered record revenue, guided well above the Street, sharply raised its 2028 targets and unveiled a multi-billion-dollar Japan expansion built around silicon photonics for AI data centers. Since then, the shares have fallen about 26% while the S&P 500 has been roughly flat. The report due before the open on November 2 is a test of which side is reading the story correctly.
The bar is set high on paper. Analysts expect non-GAAP earnings of $1.06 per share on revenue of $520.2 million, up 31.5% from a year ago and a solid step up from the $460.1 million reported last quarter. The earnings whisper of $1.13 sits meaningfully above consensus, which suggests the more engaged crowd expects margin upside, not merely a revenue print in line with the guide. Management called for third-quarter revenue of $494 million to $546 million. When that guidance came out, consensus sat near $490 million, below the bottom of the range. Analysts have since moved right to the $520 million midpoint, so a result at the midpoint now counts as merely meeting expectations rather than exceeding them.
Silicon photonics is the variable that matters most. Last quarter that business grew more than 60% sequentially to an annualized run rate of roughly $680 million. Management is targeting a $1 billion run rate by the fourth quarter. The third quarter should show a clear move along that path, and a figure comfortably in the $800 million range would support the trajectory. Equally important is whether the roughly $1.3 billion of customer-committed 2027 photonics contracts is reaffirmed or expanded. Tangible updates on Marvell's coherent modules and early near-package optics deployments would also help. The IQE indium phosphide supply agreement was meant to remove a bottleneck flagged in earlier calls, so any hint that materials still limit shipments would undercut that claim.
Margins are the second pillar. Gross margin has climbed from 24% a year ago to 30% last quarter. Management's new 2028 model now calls for 45% gross margin and a 33% net margin, up from the roughly 39% to 40% gross margin assumed in earlier models. Revenue growing faster than fixed costs should keep that slope intact this quarter. A stall would raise questions about the operating leverage that underpins the raised model. Management itself identified wafer pricing as the biggest swing factor, so commentary on photonics ASPs deserves close attention, especially with GlobalFoundries, STMicro and Samsung adding capacity. The offsets are known quantities. RF mobile remains stuck in a 200mm to 300mm transition, with recovery not expected until mid-2027, and image sensors have been flat. Further erosion there would matter less than any wobble in photonics.
Sentiment has cooled noticeably, slipping from moderately bullish before the last report to roughly neutral now. The stock trades well below its 200-day moving average near $203. It also sits only about 2% above its post-earnings low of $163.69, a long way from the $277.88 high set after the last report. That positioning cuts both ways. Clean execution could meet a market that has priced in considerable doubt, while a soft guide would confirm the skeptics' fears.
The real verdict will likely rest on the fourth-quarter outlook and on whether it keeps the $1 billion photonics run rate in reach. A guide that implies continued sequential growth, steady margin expansion and firm pricing would suggest the narrative from last quarter is intact. Anything less would suggest the market's recent pessimism was justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Sep-25 |
Chip Stocks Rise After Two-Day Skid. Tower Semiconductor Among Leaders.
TSEM +6.07%
Investor's Business Daily
|
| Sep-25 | |
| Sep-25 | |
| Sep-25 | |
| Sep-25 | |
| Sep-24 | |
| Sep-23 | |
| Sep-18 | |
| Sep-18 |
