Tower Semiconductor Beats Narrowly And Lifts SiPho Trajectory, But The 2028 Model Holds And Shares Sit Near Lows
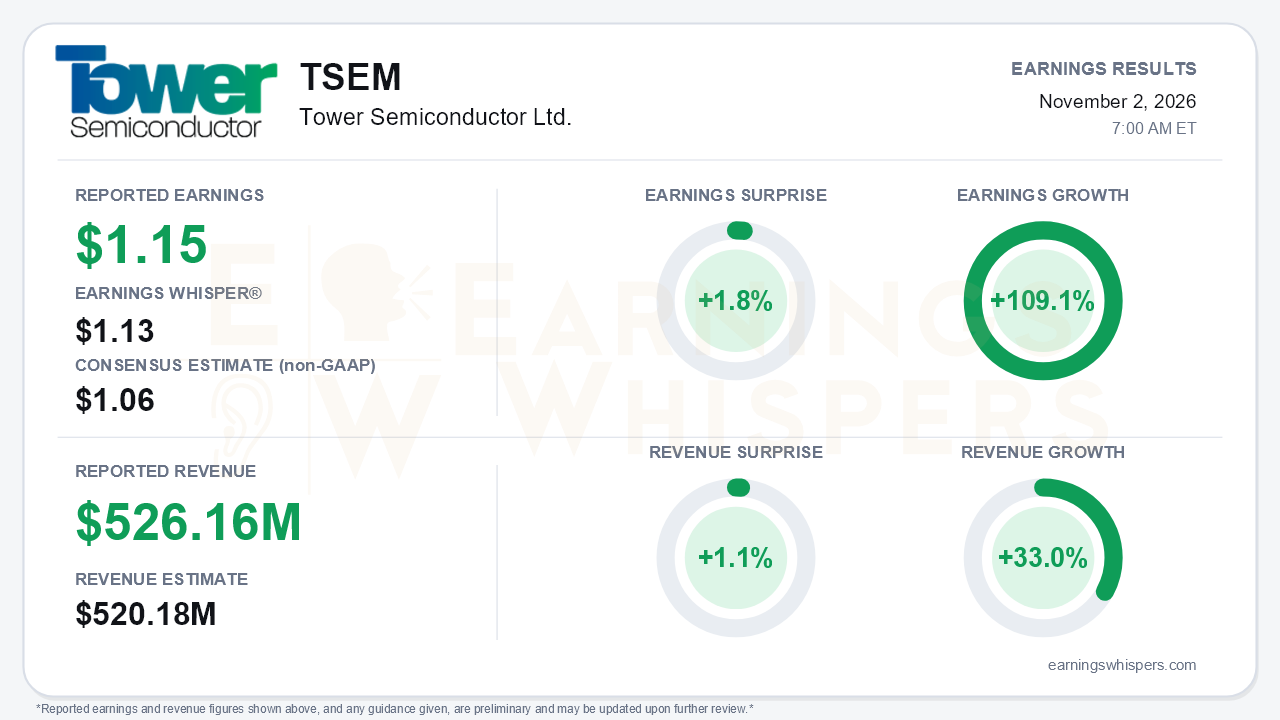
Tower Semiconductor delivered another quarter of accelerating growth. Adjusted earnings of $1.15 per share topped the $1.06 consensus and edged past the $1.13 Earnings Whisper number, a 1.8% surprise. Revenue of $526.16 million beat the $520.18 million consensus by 1.1%. Earnings grew 109.1% year over year on 33.0% revenue growth, and fourth-quarter guidance of $600 million at the midpoint implies 36% year-over-year growth and a 14% sequential gain. The fundamentals are getting stronger, but the stock has done the opposite. Shares have fallen 26.2% since the August report and sit just 3.8% above their inter-earnings low. Much of the improvement was already anticipated, and investors appear to be pricing in capital intensity, competition, and the lack of a formal model raise rather than the beat itself.
Operating leverage drove the quarter. Gross profit rose to $179 million, about a 34% margin, from $138 million (30%) in the second quarter and $111 million (27%) in the first. Operating profit reached a record $127 million. Net margin climbed to 23% from 20% and 16% in the two prior quarters. Adjusted diluted EPS stepped up from $0.88 to $1.15 sequentially, while GAAP diluted EPS was $1.05 against $0.79. The GAAP-to-adjusted gap reflects only stock compensation and intangible amortization, so earnings quality is not a concern.
Cash flow is where the beat deserves scrutiny. Operating cash flow of $185 million was fully absorbed by $191 million of net capex, leaving free cash flow slightly negative for the quarter. That $185 million also included $23 million of customer advances. Across nine months, $305 million of operating cash came from net customer advances. Deferred revenue and customer advances now total roughly $341 million, up from about $27 million at year-end. Those prepayments signal real customer commitment, but they also bring obligations. The release explicitly flags the risk of penalties or prepayment repayments if Tower cannot meet capacity commitments.
The call made the growth story more concrete, led by silicon photonics. SiPho revenue was about $240 million in the third quarter, up from roughly $170 million in the second. Management now targets an annualized run rate above $1.1 billion in the fourth quarter, ahead of the roughly $1 billion target set in August. Other operating points:
- SiPho capacity is planned to double from third-quarter levels by year-end and triple by the third quarter of 2027.
- The Track 1 300mm expansion in Japan is ahead of schedule, with full production starts now targeted for the third quarter of 2027.
- Customer capacity contracts were extended through 2029.
- 200mm utilization rose to 85-90%.
- New business includes a Semtech SiGe capacity agreement, NPO prototyping with more than ten top customers, initial integrated InP laser production, and BCD long-term agreements lifting blended 2027 pricing about 20%.
- Management expects to avoid typical first-quarter seasonality and targets first-quarter 2027 revenue more than 45% above the prior year.
Bears still have legitimate ammunition. The 2028 model of $3.6 billion in revenue and $1.2 billion in net income was reaffirmed, not raised, and the CEO declined to call it conservative. The third quarter's roughly 62% incremental gross margin is not sustainable. The CFO guided to 55-58% as depreciation from the remaining 35% of the $920 million capex program and Track 1 tools arrives. Other concerns:
- The current ratio has fallen to about 3.7x from 4.9x in the second quarter and 5.6x in the first.
- Management acknowledged that competitors are adding SiPho and SiGe capacity and that there is room for other players.
- RF mobile is still digesting a fab requalification.
- NPO timing depends on market adoption.
- Track 2 output is largely a 2029 story.
- The Pillar Two minimum tax regime is already raising the effective tax rate.
The market setup is more complicated than the surprise suggests. Investor sentiment fell from a positive 0.25 after the August report to a slightly negative -0.05, a meaningful turn from optimism to mild skepticism. Shares at $166.48 are 18.7% below the 200-day moving average of $204.75 and 40.1% below the $277.88 peak reached in mid-August. That means the stock has given back the entire post-report rally and more. The Earnings Whispers trend readings are mixed: sequential growth and momentum remain positive, while price and AVWAP trends are negative.
The bottom line is that Tower's results and outlook argue its growth phase is still building: SiPho is ahead of plan, contracts now run to 2029, and capacity is coming online early. The beat over the whisper was modest, however. Free cash flow relies on customer prepayments, margins face a depreciation headwind, and management chose to reaffirm rather than raise its 2028 targets. With shares near their lows and sentiment soured, the report gives the bull case new evidence. The market now has to decide whether that execution is worth paying up for again.
Read our earnings preview for Tower Semiconductor Ltd.: https://www.earningswhispers.com/article/TSEM/21358
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 6 hours | |
| 6 hours | |
| 8 hours | |
| 8 hours | |
| 10 hours | |
| Oct-26 | |
| Oct-23 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Sep-25 |
Chip Stocks Rise After Two-Day Skid. Tower Semiconductor Among Leaders.
TSEM +6.07%
Investor's Business Daily
|
| Sep-25 |
