Chemours Faces Refrigerant Slump Test As Titanium Dioxide Price Gains Try To Carry The Quarter
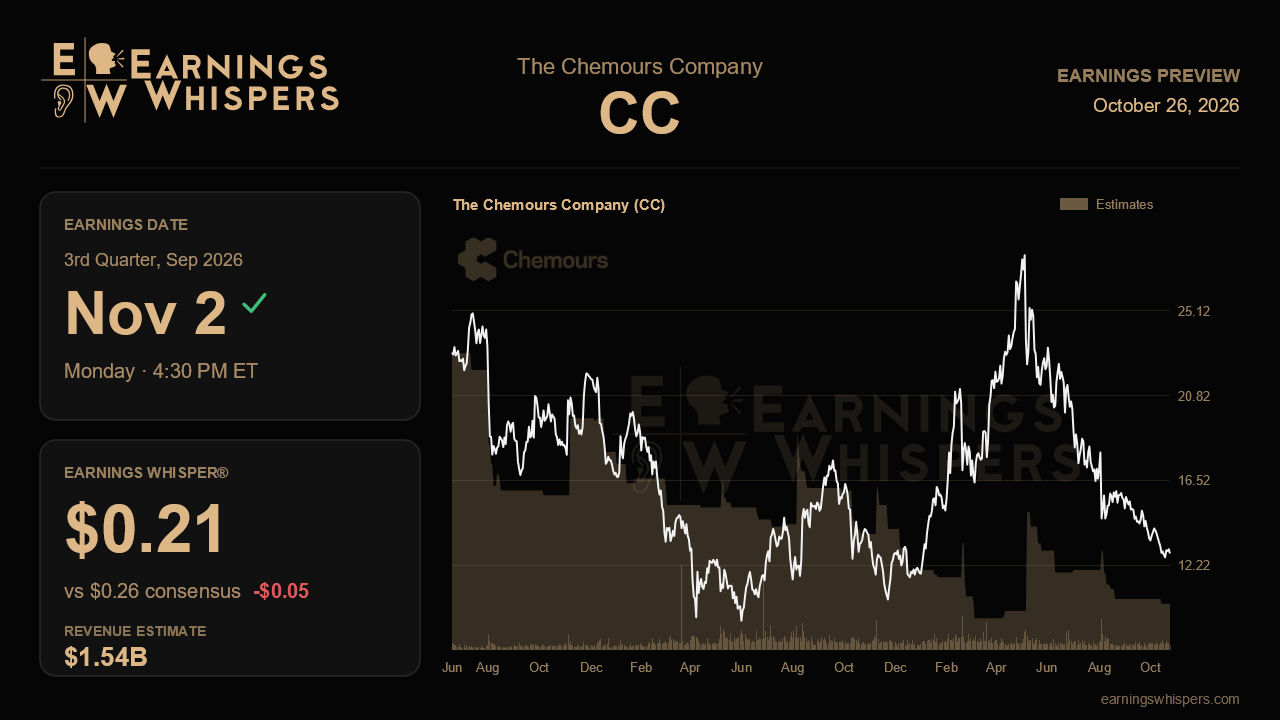
Chemours heads into its third-quarter report with two businesses pulling in opposite directions. Its titanium dioxide unit is finally pushing through price increases after a long trough, while its refrigerant franchise, until recently the company's most dependable profit engine, has run into a sharp aftermarket slowdown. The report after the close on November 2 will show whether the pricing recovery is strong enough to offset that slump, or whether last quarter's guidance cut was only the first step down.
Wall Street expects earnings of $0.26 a share on revenue of about $1.54 billion. That would be a 30% gain over the $0.20 earned a year ago on revenue growth of only 3%, which shows how much the story now depends on margins rather than volume. It also marks a clear sequential decline from the $0.42 and $1.59 billion posted last quarter. The Earnings Whisper of $0.21 sits below consensus, so the market appears braced for a shortfall rather than hoping for a beat. Management reaffirmed full-year revenue of $5.98 billion to $6.10 billion, and the Street's $6.05 billion sits comfortably inside that range, slightly above the midpoint. The pressure point is profit, not sales. Adjusted EBITDA guidance has already been lowered to $775 million to $825 million from an original $800 million to $900 million, and full-year sales growth was trimmed to 1% to 5%.
Thermal and Specialized Solutions is the biggest swing factor. Management said the stationary aftermarket market was down roughly 25% from a year ago. It blamed channel inventory built up during the 2025 refrigerant transition pre-buy, along with high interest rates, weak housing and a cold spring. The company guided third-quarter segment sales down mid-teens to 20% from the second quarter, with EBITDA of $125 million to $140 million and margins reset to the high 20s from the 30%-plus level it had long described. Landing within that range would suggest the reset was realistic. A figure near the bottom, or any sign that destocking will stretch beyond the first quarter of 2027, would cast doubt on next year as well.
Titanium Technologies needs to deliver the offset. Three price increases since December have produced about 5% year-to-date pricing. Management guided third-quarter segment sales up low to mid single digits sequentially, with EBITDA of $70 million to $80 million, a big improvement from the near break-even level early in the year. The key test is whether that price holds as sulfur and other input costs rise, and whether management sounds confident about further increases. Advanced Performance Materials offers the more interesting long-term thread. Performance Solutions grew 8% on data center and semiconductor demand, product trials rose 70%, and the first small sales of two-phase liquid cooling fluids began. Evidence that those samples are turning into repeat orders would add weight to the growth story.
Cash flow is the other support for the bull case. Management raised its free cash flow conversion target to above 25%, repaid about $270 million of euro term loan debt ahead of plan and settled legacy matters with the EPA and West Virginia regulators. It still targets net leverage near 3.8 times by year end. Any slippage there would hit a balance-sheet story that had been one of the few clean positives.
The market has already passed judgment. The stock has fallen 20% since the last report, trailing the S&P 500 by nearly 18 percentage points. At $12.81 it trades far below its 200-day average of $18.40 and just above its post-earnings low of $12.49. Sentiment has swung from mildly bullish to firmly bearish, so a lot of bad news may already be in the price. Even so, the central question is simple. If refrigerant earnings land inside the reset range and titanium dioxide pricing keeps building, the reduced EBITDA outlook should hold. If the aftermarket weakens again, investors may conclude the guidance cut was not the last one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 6 hours | |
| 8 hours | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-11 | |
| Sep-29 | |
| Sep-28 | |
| Sep-11 |
