Black Stone Minerals Must Show Its Shelby Trough Rig Surge Is Reaching Gas Volumes
Black Stone Minerals did something last quarter it rarely does: it raised its payout. The 7% bump to $0.32 per unit, the first increase after four straight quarters at $0.30, was explicitly tied to management's confidence in a coming natural gas ramp. That bet arrived alongside a quarter in which gas volumes actually fell. The third-quarter report, due after the close on November 2, is the first real chance to see whether the production curve is starting to catch up with the distribution.
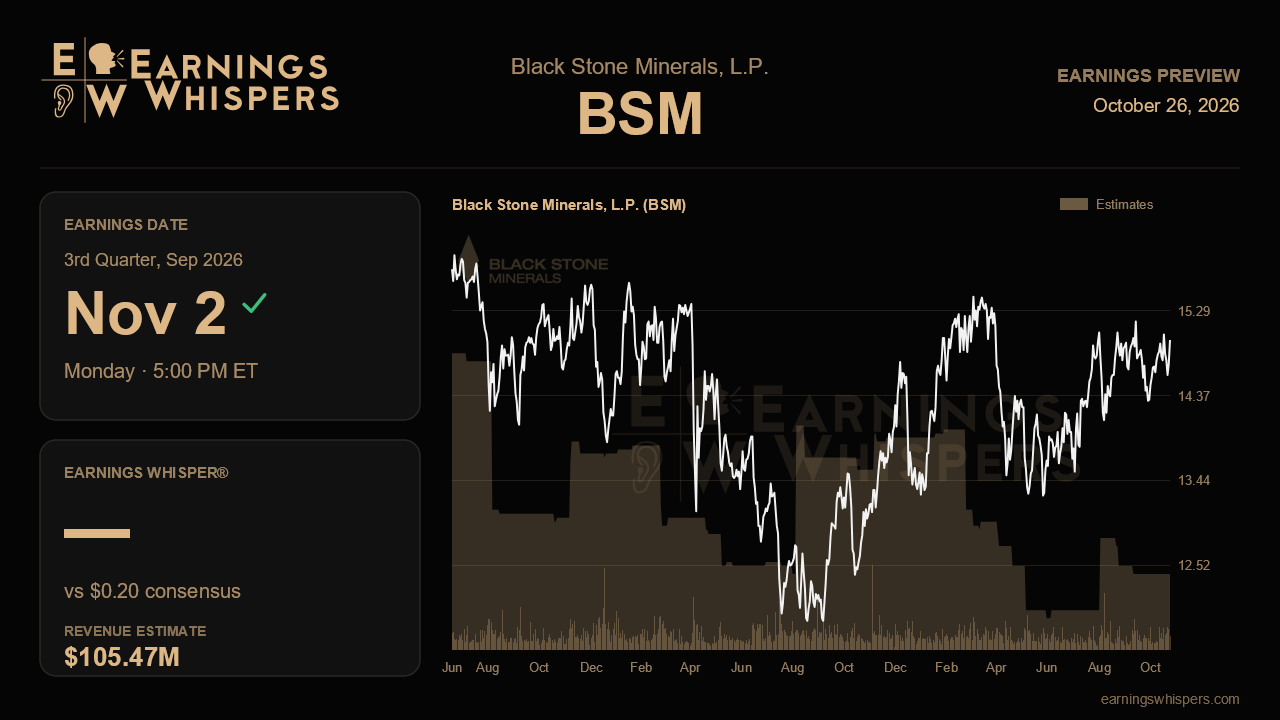
The Street is not setting a demanding bar. Consensus calls for earnings of $0.20 per unit on revenue of $105.5 million, down 50% and 20.4% from the year-ago $0.40 and $132.5 million. The drop from last quarter's $0.47 and $149.0 million is even sharper. For a royalty owner with no drilling costs, swings of that size usually reflect commodity prices, timing of high-interest wells and any hedge or lease bonus contributions rather than a fundamental change in the business. Management did not formally raise its February outlook last quarter, keeping it as the anchor, so this is a reaffirm-and-execute story rather than one built on rising targets. Against that backdrop, distribution coverage may matter more than the headline per-unit figure. Coverage stood at a healthy 1.18 times after the increase, and a quarter that keeps it comfortably above one would support the view that the higher payout is sustainable.
The operating test centers on the Shelby Trough and Haynesville acreage. The rig count there climbed from roughly 13 to about 19 between the first and second quarters, yet mineral and royalty production slid 9% to 32.5 thousand barrels of oil equivalent per day, with total production at 33.5. Management blamed lumpy timing on wells where Black Stone holds large interests. That explanation holds up only if volumes stabilize or turn higher soon. A sequential rebound would validate the inflection thesis that has run through every call over the past year; another decline with nineteen rigs running would raise uncomfortable questions about the lag between activity and cash flow.
Several newer catalysts also need progress reports. Catarus moved to a live pilot well with development drilling slated for the back half of the year, Atomos has eight more wells due online in 2026 and seventeen planned in its new program year, and management said it was close to announcing a new Haynesville development agreement with an additional operator on acreage it has marketed since late last year. Signing that deal would add a fresh source of drilling commitments, partly offsetting the reduced first-year program from Revenant after its well-control incident. On the other side of the ledger, leverage has risen from zero in 2024 to just over half a turn, $300 million of Apollo preferreds must be addressed in roughly a year, and Henry Hub spent much of 2026 below $3.50. Any update on financing plans or acquisition pace, which has reached about $300 million cumulatively, will help frame the balance sheet risk.
Expectations have warmed only slightly. Sentiment has shifted from mildly bearish before the last report to mildly bullish now, while the units have slipped 0.9% since then, roughly in line with a flat S&P 500. The stock trades at $14.97, above its 200-day average of $14.47 and within about 1.5% of its post-earnings high of $15.20, a level that already sits above last quarter's peak. A convincing report could push the units into a breakout from a range that has been tighter than the prior quarter's.
Ultimately, the question is whether the distribution hike was early confidence or premature optimism. If gas volumes begin responding to the higher rig count and the new Haynesville partner materializes, the payout increase will look like the start of a growth phase. If production stays soft and the agreement remains pending, the market may start treating the raise as a promise still awaiting proof.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-21 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 | |
| Jul-31 | |
| Jul-23 | |
| Jul-22 | |
| Jul-08 | |
| May-04 | |
| May-04 | |
| May-04 | |
| May-01 | |
| Apr-22 |
