Black Stone Minerals Edges Past EPS Consensus As Hedge Losses Hide Record Cash Flow And A Much Larger Caturus Runway
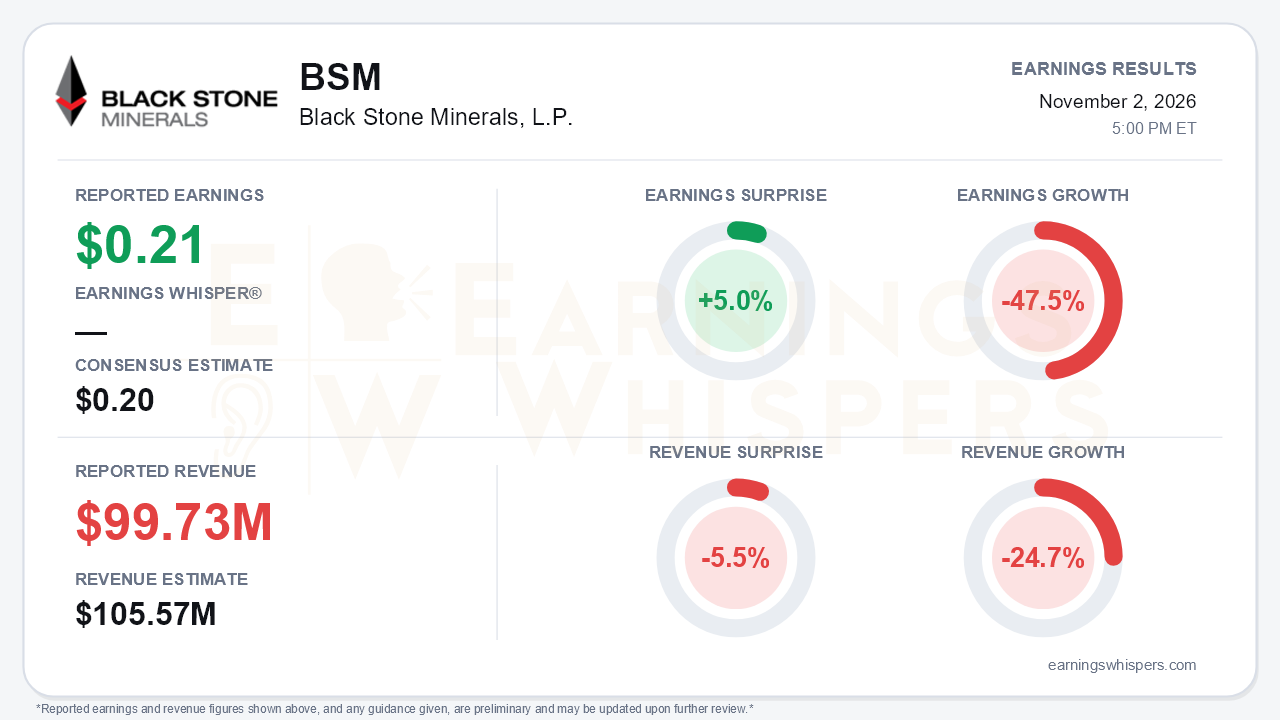
Black Stone Minerals (NYSE: BSM) reported third-quarter earnings of $0.21 per unit. That was $0.01 above the $0.20 consensus, a 5.0% surprise. Revenue of $99.73 million missed the $105.57 million estimate by 5.5%. On the surface the comparisons look poor: earnings fell 47.5% year over year and revenue declined 24.7%. Those figures are distorted, however, by the partnership's hedge book. Total revenue includes a $30.2 million loss on commodity derivatives, almost all of it a non-cash $29.8 million unrealized mark. A year earlier the same line was a $27.3 million gain. Strip that swing out and the quarter was the strongest cash-generating period in the recent run. That is the central tension: weak GAAP optics sit on top of improving distributable economics.
The underlying numbers deserve more attention than the headline. Revenue from contracts with customers rose to $129.9 million from $105.2 million a year ago. Oil and gas revenue increased 6% sequentially to $122.7 million. Adjusted EBITDA reached $104.1 million, up from $91.3 million in the second quarter and $88.1 million a year earlier. Distributable cash flow climbed to $93.0 million, or $0.437 per unit, from $0.371 a year ago. That supported a second straight distribution increase, to $0.35 per unit ($1.40 annualized). The payout is up 9% sequentially and 17% since the first quarter, and coverage still improved to 1.25x from 1.18x in the second quarter and 1.05x in the fourth quarter of 2025.
The beat has quality caveats. Mineral and royalty volumes of 34.5 MBoe/d rose 6% from the second quarter but were essentially flat with the 34.7 MBoe/d of a year earlier. The year-over-year improvement was therefore driven by price, not volume. Realized oil prices jumped to $86.95 per barrel from $62.60, and oil and condensate generated 63% of oil and gas revenue even though production is 73% natural gas. Realized pricing per Boe was roughly flat sequentially, down 1%, after rising in the prior quarter. Costs also moved the wrong way:
- G&A rose to $16.5 million from $12.3 million.
- Interest expense increased to $3.9 million from $2.4 million.
- Exploration expense, largely seismic, more than doubled. Management excludes seismic costs from Adjusted EBITDA under a definition revised last year.
The call preserved a credible, and expanding, growth story. The headline development was an amended and restated agreement with Caturus. It added roughly 730,000 gross acres, bringing the contract area to 950,000. Management said that together with the Adamas and Revenant agreements, structured development programs now cover about 1.4 million gross acres, up from roughly 500,000 cited at the end of 2025. Nearer-term catalysts are concrete:
- Revenant's first wells are expected to turn to sales by year-end.
- Caturus spud its first two development wells in October, with production expected in the first half of 2027.
- Adamas turned seven gross wells to sales during the quarter.
- Third-party operators have 10 wells drilling or awaiting completion across the Shelby Trough.
Investors should still be clear about timing. The new Caturus areas do not start until a pilot well by the first quarter of 2028. Ramps to roughly 12 gross wells a year are not scheduled until 2034 and 2038, and each phase depends on Caturus electing to proceed.
Bears have legitimate ammunition. Recent oil strength leans on price-driven DUC conversions, and operators' 2027 capital plans are uncertain. Management characterized the gas ramp as lumpy and offered no explicit 2027 production outlook. The hedge book also caps upside. Oil swaps sit near $65 per barrel through 2027, well below the quarter's realized price. On the balance sheet, $197 million is drawn against $375 million of commitments. Acquisitions continue, with $30.6 million in cash spent in October and management hinting at more. The $300 million preferred remains unresolved. Management said the credit facility is sufficient to fund the acquisition program, and the $580 million borrowing base was reaffirmed ahead of an April 2027 redetermination.
Investor sentiment moved from slightly negative (-0.07) to slightly positive (+0.06) heading into the report. That is a meaningful improvement in tone, but hardly euphoric. The units have not followed the fundamentals. At $14.74, they are 2.4% below the $15.10 open following the August report and only 1.6% above the $14.50 200-day moving average. Earnings Whispers trend readings are mostly positive, though sequential growth remains a soft spot.
The bottom line is that Black Stone's quarter was better than its GAAP headline and revenue miss suggest. It produced record cash flow, wider coverage, a growing distribution and a substantially enlarged development footprint. The open question is durability. Volumes are no higher than a year ago, oil prices did much of the work, and the largest new Caturus commitments are years from contributing. Investors are being asked to bridge a flat production base today to a gas-driven ramp that depends on operator execution.
Read our earnings preview for Black Stone Minerals, L.P.: https://www.earningswhispers.com/article/BSM/21371
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-21 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 | |
| Jul-31 | |
| Jul-23 | |
| Jul-22 | |
| Jul-08 | |
| May-04 | |
| May-04 |
