Camping World's Q3 Tests Whether Cost Cuts And Used Sales Can Hold Its Lowered Guidance
Camping World enters its third-quarter report with a credibility problem rather than a demand problem it can fix alone. Last quarter management cut its full-year adjusted EBITDA outlook to $230 million to $270 million from $275 million to $325 million, the first outright reduction after a year of setting and reaffirming targets. It also warned that July was shaping up worse than June. The upcoming numbers are the first real check on whether that reset was conservative enough, or whether the slide in new RV demand has further to run.
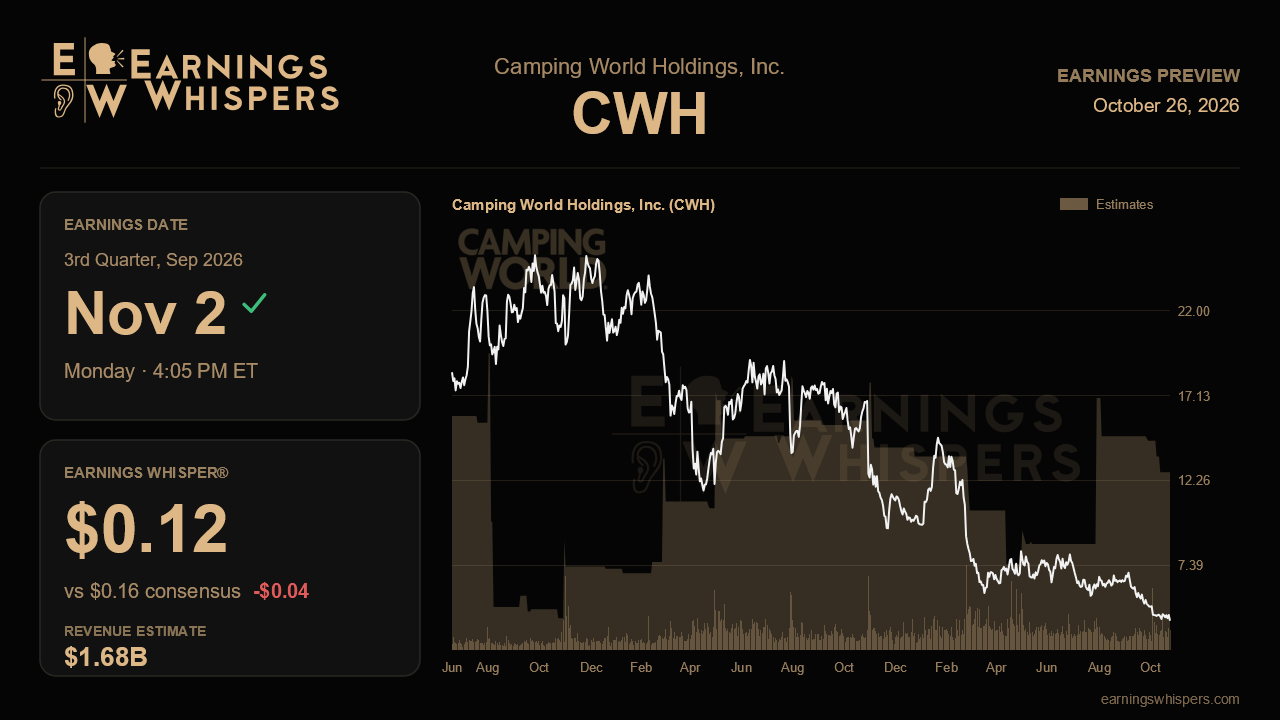
Wall Street expects earnings of $0.16 a share on revenue of about $1.68 billion, a 7% decline from a year ago. That is a sharp step down from the $0.35 earned in the same quarter last year and the $0.50 posted last quarter, so analysts are already penciling in contraction. The Earnings Whisper sits lower still at $0.12. The gap is small in absolute terms, but on a base this thin it signals that the more skeptical crowd expects at least a modest shortfall against published estimates.
The new vehicle business is the main swing factor. New units fell more than 16% last quarter and new gross margin compressed to 10.9%, down from 12.2% in the first quarter and 13.8% a year earlier. Management's revised full-year range of 11.5% to 12% implies the second half needs to run noticeably better than the second quarter did. It said July margins were improving sequentially, and its unusually clean inventory supports that claim: prior-model-year new units are near 1% of stock, compared with 6% a year ago. A third-quarter new margin that climbs back toward the guided range would validate the idea that the worst discounting is over. A reading stuck near 11% would suggest the industry's excess channel inventory is still forcing price concessions, and that the full-year target is at risk. The same applies to used margins, which slipped to 16.5% against a full-year guide of 17.5% to 18%.
Used units are the bright spot worth tracking. Same-store used volume swung to growth of more than 5% from a decline in the first quarter, and management described continued share gains. If that momentum held through the summer, it shows Camping World can grow where it controls sourcing and pricing even while new demand falters. Good Sam, where services and plans margin expanded to nearly 62%, should again act as a steady profit cushion. On costs, the company has been trimming SG&A by roughly $27 million to $29 million a quarter and launched a new $100 million savings program, with about half expected by the end of 2026. Visible progress here, including early returns from the in-house sales CRM and the new tiered service labor rates, would lend weight to the roughly $70 million of 2027 tailwinds management has identified.
The market has delivered its verdict on the guidance cut. Shares have dropped about 31% since the last report while the S&P 500 gained roughly 3%. At $4.20, the stock trades far below its 200-day moving average near $7.57 and just above its post-earnings low of $3.97, a range entirely beneath last quarter's $5.49 floor. Sentiment has turned slightly more bearish than it was heading into the prior report. Expectations look low, but a stock pinned near its lows offers little support if the outlook slips again.
The question that matters most is whether management can hold the $230 million to $270 million EBITDA range. A reaffirmation backed by improving new margins and sustained used growth would suggest the self-help story is outrunning a weak industry. Another cut, especially one blamed on a further drop in new unit volume or a lower industry forecast than the current 290,000 to 310,000 units, would extend a pattern of eroding guidance that investors have already punished hard.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-19 | |
| Jul-29 | |
| Jul-29 | |
| Jul-17 | |
| Apr-29 | |
| Apr-29 | |
| Apr-16 | |
| Mar-24 | |
| Mar-22 | |
| Mar-16 | |
| Mar-12 | |
| Mar-10 | |
| Feb-27 |
