Camping World Misses Badly As New-Vehicle Margins Crack, Leaving A Bigger Cost Program To Carry The Story
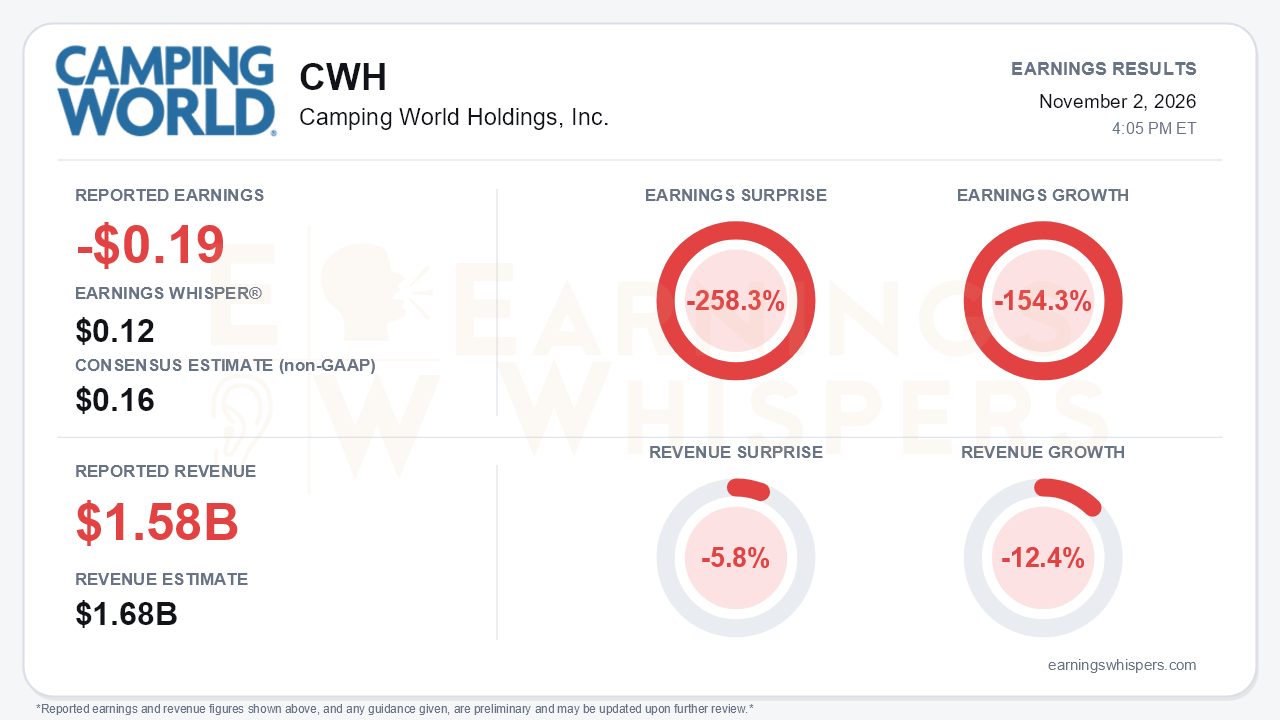
Camping World Holdings (NYSE: CWH) delivered a decisive third-quarter miss. The adjusted loss was $0.19 per share, against a $0.16 consensus profit and an Earnings Whisper of $0.12. That is a 258.3% negative surprise and a 154.3% year-over-year decline from adjusted EPS of $0.43. Revenue fell 12.4% to $1.583 billion, 5.8% short of the $1.68 billion consensus. On a GAAP basis the loss was $3.09 per share, driven by a $286.7 million noncash goodwill impairment on the RV and Outdoor Retail unit. The central development is that the industry's new-vehicle pricing problem has proven deeper and longer-lasting than management expected. Its answer is to cut its way to a lower-earnings base rather than wait for demand to return.
The quality of the quarter does not soften the miss. Adjusted EBITDA fell 62.4% to $36.0 million, and management put the figure at about $49 million excluding a $12.7 million F&I chargeback reserve adjustment. That adjustment was tied to rising product cancellations, which is not a reassuring sign about the consumer. New unit sales fell 25.4%, and same-store new units fell 26.4%. New-vehicle gross margin dropped 252 basis points year over year to 10.2%, because average cost per unit rose 15.0% while selling prices rose 11.7%. Products, service and other margin fell 690 basis points as service was billed at lower labor rates. Even the brighter spots carry caveats. Good Sam Club revenue jumped 75.6%, but that included a nonrecurring $5.3 million milestone payment. SG&A fell $23.9 million, yet it consumed 89.1% of gross profit, up 964 basis points, because gross profit shrank faster than costs.
The call showed deterioration accelerating on several fronts. New gross margin has slid from 12.2% in the first quarter to 10.9% in the second and 10.2% now. Management cited competitors discounting 37% to 40% off MSRP and acknowledged ceding new unit share after record share gains through May. Used units swung from roughly +5% in the second quarter to about -9%, and the used market softened from August. The guidance path tells the story most plainly:
- Full-year adjusted EBITDA was guided to $275 million to $325 million early in the year.
- It was cut to $230 million to $270 million last quarter.
- It is now expected below the low end, with no formal outlook.
The long-term new-margin target of 13% to 14% has also been pushed beyond 2027. Earlier, the company had targeted 13% to 13.5% by 2027.
The offsets are real but mostly self-help. The efficiency program grew from about $100 million to more than $150 million annualized, including a roughly 15% headcount cut and four store closures. Fourth-quarter SG&A is expected to fall more than $50 million year over year. Management's early 2027 framework adds $75 million of incremental SG&A savings plus some margin normalization, and it expects positive free cash flow with capex below $80 million. Several operating trends are improving:
- Used gross margin recovered to 18.0% from 16.5% in the second quarter.
- Good Sam Services and Plans margin expanded to 62.3%.
- 61% of new inventory is model-year 2027, versus an estimated 40% to 45% at peers.
- The same-store new-unit decline narrowed from the high-20s in July to the low-teens in October.
Bears still have legitimate ammunition. Fourth-quarter combined units are guided down mid-teens. Management expects industry new retail to be flat to down mid-single digits in 2027 and is planning more conservatively than that. Net debt leverage has climbed to 8.6 times trailing adjusted EBITDA from 5.2 times a year ago, and a refinancing of the senior secured facilities will likely carry a higher rate.
The balance sheet is the counterweight. Year-to-date operating cash flow reached $488.0 million, total inventory is down $343 million from year end, and net debt fell 7.0% year over year. That cash came largely from liquidating inventory, however, not from earnings power. With trailing EBITDA shrinking, the leverage ratio moved the wrong way even as absolute debt declined.
Investor sentiment remained negative but improved modestly, from -0.12 to -0.06, ahead of the release. Expectations were already subdued but not capitulatory. As of the report date, shares traded at $5.35. That is 12.3% below the open following the July report and 27.4% below the 200-day moving average of $7.37. Earnings Whispers price, momentum and AVWAP trend readings are all negative, consistent with a stock the market had been steadily marking down before this miss.
The bottom line is that Camping World's quarter confirmed the bear case on the parts of the business it cannot control: new-vehicle pricing, unit share, used demand and consumer credit behavior. Its response was aggressive on the parts it can control. The expanded cost program, cleaner inventory and improving used and Good Sam margins give management a credible path to a leaner earnings base. Still, 2027 now hinges on cost savings and margin normalization rather than demand recovery. With guidance cut for a second straight quarter and leverage elevated, investors will need evidence that new margins have stopped falling before giving the turnaround narrative much credit.
Read our earnings preview for Camping World Holdings, Inc.: https://www.earningswhispers.com/article/CWH/21384
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-26 | |
| Oct-19 | |
| Jul-29 | |
| Jul-29 | |
| Jul-17 | |
| Apr-29 | |
| Apr-29 | |
| Apr-16 | |
| Mar-24 | |
| Mar-22 | |
| Mar-16 |
