Capital Southwest Must Prove Its Origination Surge Can Outrun Falling Rates And Defend The Dividend
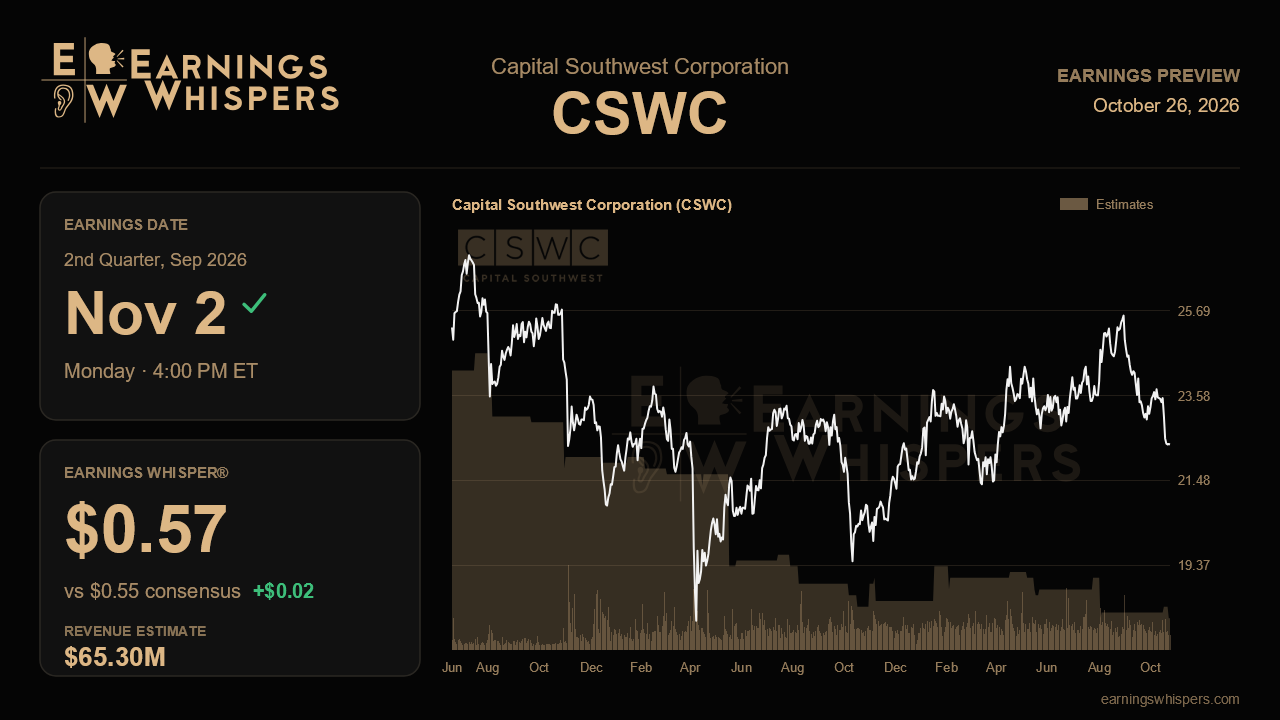
Capital Southwest heads into its fiscal second-quarter report with a split personality. Management sounded as confident as it has in some time last quarter, calling for a jump in new lending and a joint venture ramping well ahead of plan. Yet the stock has fallen 8.5% since that call while the S&P 500 was essentially flat, and it now trades just above its post-earnings low. The report due after the close on November 2 needs to show that portfolio growth is finally strong enough to offset lower base rates, which have been steadily eroding per-share income.
The Street expects net investment income of $0.55 per share on revenue of about $65.3 million. That revenue figure would be up nearly 15% from a year ago, but per-share income would be down about 3.5% from $0.57. The gap shows the core problem: the business is getting bigger, but each share is earning a little less as SOFR declines and the share count grows. Notably, consensus now sits a penny below management's guidance of $0.56 to $0.57, while the whisper number of $0.57 sits at the top of that range. The difference is small, but it suggests analysts have trimmed numbers even as more optimistic market participants expect management to deliver what it promised.
The most testable claim from last quarter is origination. After a soft $158 million in the March quarter and a rebound to $222 million in June, management guided to $250 million to $300 million for the September quarter, with roughly $125 million already closed by early August. Landing inside that range would confirm that the momentum is durable rather than a single good quarter. Falling short would revive the concern that a crowded lower middle market is squeezing both volume and spreads. Equally important is the CapTrend joint venture, which held about $98 million across 14 companies last quarter. Management pulled its full-ramp estimate forward to 12 to 15 months from 18 to 24 months and raised its targeted return to 13% to 15%. Steady growth in that book, along with the first-out economics that helped lift the debt yield to 10.9%, would support the idea that income growth can outpace rate cuts.
The dividend math is where the stakes rise. The regular payout of $0.58 sits above guided NII of $0.56 to $0.57, and the supplemental $0.06 depends on undistributed taxable income that dropped to $0.87 per share from $1.07. Management pointed to an equity realization expected to close by September 30 to rebuild that cushion. Confirmation of that gain, plus some stability in net asset value after its slip to $16.61, would ease the worry. Investors should also note that part of last quarter's PIK income came from a one-time catch-up, so a modest step down there would be expected rather than alarming.
Two balance sheet items matter as well. The vote to raise authorized shares needed two-thirds of all outstanding shares by September 1, and its outcome directly affects the company's ability to keep issuing stock above book value, its key advantage over peers. At roughly 1.35 times last reported NAV, that premium has narrowed with the share price. Progress on the credit facility amendment, which management said should lower borrowing costs, would also help per-share income.
Sentiment has soured, with readings more bearish than before the last report, and the stock sits below its 200-day moving average after a wider, more volatile trading range. That sets a fairly low bar. The central question is simple: whether faster origination, the JV ramp and a realized gain together show that Capital Southwest can grow per-share earnings back toward its regular dividend. If they do, the recent selloff looks overdone. If income lands at the low end with a thinner tax cushion, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-15 | |
| Sep-17 | |
| Sep-10 | |
| Sep-02 | |
| Sep-01 | |
| Aug-27 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-16 | |
| May-27 | |
| May-14 | |
| May-13 |
