Capital Southwest Misses The Whisper By A Penny As Record Originations Collide With Creeping Credit Strain
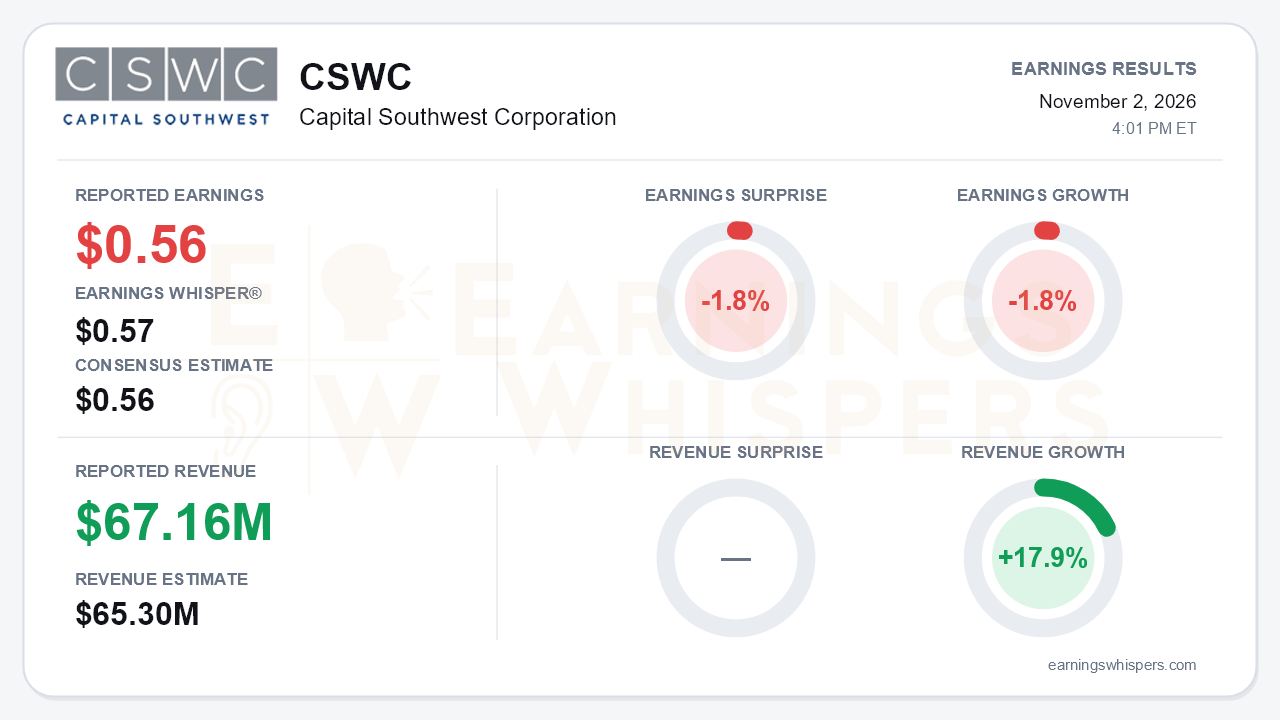
Capital Southwest (NASDAQ: CSWC) reported fiscal second-quarter net investment income of $0.56 per share. That matched the $0.56 consensus but fell short of the $0.57 Earnings Whisper number, a 1.8% miss. Earnings also slipped 1.8% from a year ago. Revenue (total investment income) told a different story: $67.16 million beat the $65.3 million consensus by 2.8% and grew 17.9% year over year. Top-line growth also clearly accelerated on a sequential basis. Income rose $6.2 million from the June quarter's $61.0 million, after a smaller step up from $57.8 million in the March quarter. That is the central tension. CSWC is growing its asset base faster than at any point in its history, yet per-share earnings are flat to down, and credit quality moved the wrong way.
The quality of the quarter deserves scrutiny on both sides. On a pre-tax basis, NII rose to $0.58 from $0.57, exactly covering the $0.58 regular dividend. A swing to a $0.9 million tax provision from a prior-quarter benefit pushed the after-tax figure below the regular payout. Several other pressures held back per-share results:
- **Dilution.** Weighted average basic shares rose to 63.6 million from 55.5 million a year ago, as equity issuance outpaced earnings growth.
- **Interest costs.** Interest expense climbed to $21.0 million from $16.0 million a year earlier.
- **One-time expenses.** Operating expenses rose on legal and proxy-solicitation costs tied to the annual meeting.
- **Fee income.** Non-control fee income more than doubled to $3.9 million. That is a byproduct of heavy origination activity and not a dependable recurring stream.
One genuine positive was a cleaner income mix, with PIK falling to 7.4% of income from 8%. Below the NII line, net realized and unrealized losses of $13.4 million cut the net increase in net assets to $0.33 per share, down from $0.46 a year ago. NAV ticked up to $16.64 from $16.61, but only because ATM issuance at a premium offset the portfolio markdowns.
The call made the growth case credibly. New commitments hit a record $391 million, compared with $222 million in the June quarter and $158 million in the March quarter. Management raised its normalized origination run-rate expectation to roughly $250 million per quarter from about $150 million. Several moves improved the balance sheet:
- **Debt issuance.** A $350 million 6.75% note was swapped to SOFR plus 2.16%.
- **Credit facility.** The facility was upsized to $595 million with a lower 2.00% margin and a 2031 maturity.
- **SBIC II.** Approved leverage capacity rose to $250 million.
- **Equity.** The authorized-share vote that had hung over the stock last quarter cleared, re-enabling the ATM, which raised $67 million at roughly 148% of NAV.
Liquidity jumped to $647 million from $375 million. The new Desert Star joint venture with Trinity Capital adds tech-lending exposure targeting 14-16% returns. Management's tone turned notably more confident, floating possible regular or supplemental dividend growth in 2027 and pointing to widening spreads, with new deals at 6.5%.
Bears have legitimate ammunition, however:
- **Non-accruals.** These rose to 1.4% of the portfolio at fair value from 1.1%. At cost they stand at 3.5%. A car wash operator and a roofing roll-up were added to the list, and debt depreciation reached roughly $14.6 million.
- **Leverage.** Regulatory leverage of 1.0x now sits at the top of the 0.9-1.0x target band, leaving less room for error.
- **Underwriting.** New-deal leverage crept up to 3.4x and 33% loan-to-value, from 2.8x and 29% in the June quarter.
- **Equity cushion.** Embedded unrealized appreciation has shrunk for several straight quarters to $0.48 per share, down from $0.76 three quarters ago, as larger exits slip into 2027-28.
- **Repayments.** Management expects about $200 million of repayments in the December quarter against roughly $250 million of originations, which will slow net portfolio growth.
- **Software exposure.** The software lending added through Desert Star comes amid AI-disruption concerns.
Investors appear to be weighing those risks more heavily than the origination record. Earnings Whispers sentiment, already slightly negative heading into the report, became more negative, falling to -0.149 from -0.057. That is a meaningful but not dramatic shift. Shares have lost 4.1% since the open following the August report and now sit at $23.43, essentially on top of the $23.41 200-day moving average. The trend readings are mixed: sequential growth and momentum are positive, while price and AVWAP trends remain negative. That split mirrors a fundamental picture of accelerating revenue alongside deteriorating credit marks.
The bottom line is that Capital Southwest delivered a scale-up quarter that strengthened its funding base and lifted its growth outlook. The penny miss against the whisper and the flat per-share earnings show that rapid, equity-funded growth is not yet translating into higher NII per share. With leverage at the top of its range, non-accruals rising and the equity cushion thinning, the stock's premium valuation now rests on management converting record originations into per-share earnings growth without further credit slippage. Estimated undistributed taxable income of $0.92 per share gives the dividend a buffer while that plays out.
Read our earnings preview for Capital Southwest Corporation: https://www.earningswhispers.com/article/CSWC/21383
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-15 | |
| Sep-17 | |
| Sep-10 | |
| Sep-02 | |
| Sep-01 | |
| Aug-27 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-16 |
