Crescent Energy Brings Its Permian Synergy Story Into A Planned Oil Dip Quarter
Crescent Energy enters its third-quarter report with an unusual setup: management has already told investors that oil volumes will soften, yet the Street's informal bar sits well above the published estimate. After a second quarter in which the company raised production guidance, cut its cost outlook, tripled its Permian synergy target and posted record free cash flow, the question is no longer whether the integration is working. It is whether the business can keep showing progress in a quarter that management deliberately framed as a lull.
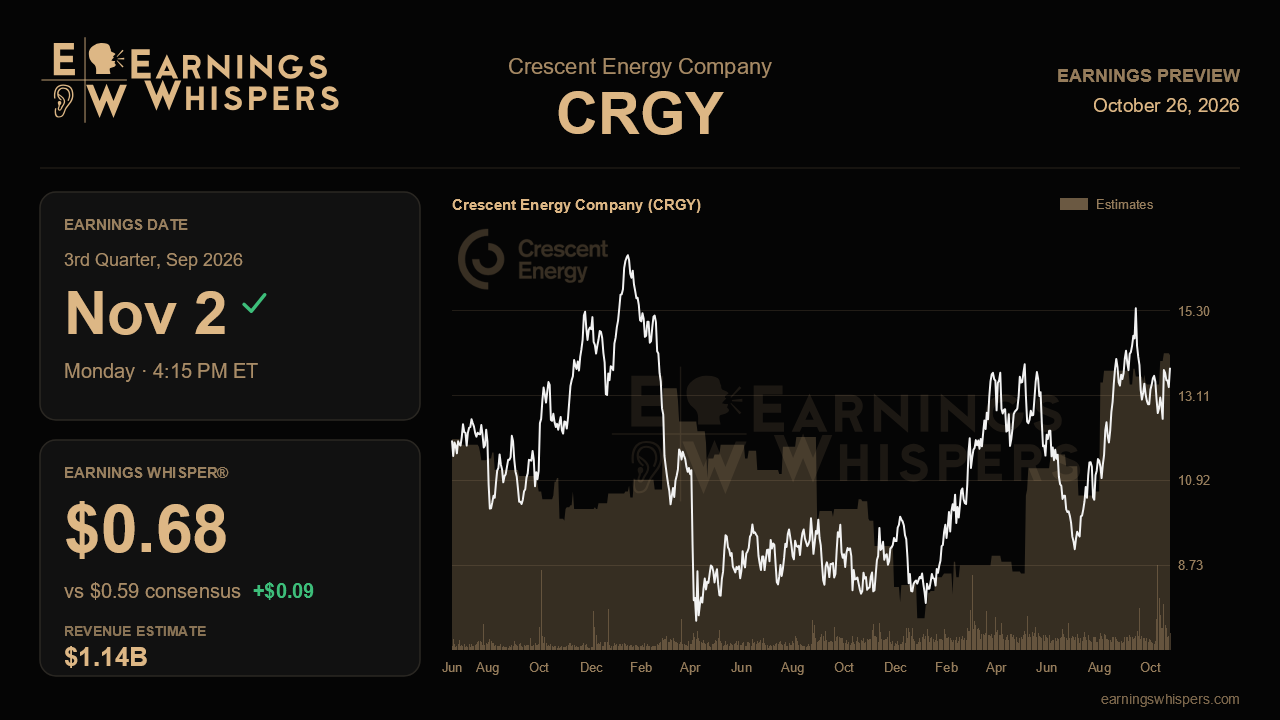
Consensus calls for adjusted earnings of $0.59 per share on revenue of about $1.14 billion. That would roughly double the $0.30 earned a year ago, and revenue would climb nearly 32% from $866.6 million, a reminder of how much the Permian acquisition has enlarged the company. Sequentially, though, the picture is softer. Last quarter Crescent earned $0.62 on $1.39 billion of revenue, so analysts expect a step down that lines up with guidance for oil production to slip into the mid-130s thousand barrels per day from about 140 in the first half. The Earnings Whisper of $0.68 is a meaningful gap above consensus and would actually top last quarter's result, suggesting that the more engaged part of the market expects lower costs and synergies to more than offset the volume dip.
That makes costs and synergies the heart of the report. Management lifted its Permian synergy goal to $250 million to $300 million, roughly three times the original base case, and said about $190 million had already been captured, up from $120 million a quarter earlier. Another solid increment toward the new target would validate the claim that the asset has moved from stabilization into optimization. Adjusted operating expenses, now guided to $11 to $12 per barrel of oil equivalent, should land comfortably inside that range if the efficiency story is real. Development capital, held at $1.325 billion to $1.425 billion despite higher volume guidance, is the other discipline test; any creep would undercut the narrative of producing more with the same money.
The volume dip itself is the main area where the story could be challenged. Management attributed it to the timing of new wells and the shift from two-mile to three-mile laterals, a mechanical explanation rather than a reservoir problem. Confirmation that full-year production of 327,000 to 335,000 barrels of oil equivalent per day remains on track, along with signs that longer laterals are coming online as planned, would keep that framing credible. Free cash flow also deserves attention. With $610 million generated in the first half, the company needs only a moderate second half to clear its outlook of more than $1 billion, so a strong third quarter could set up yet another upward revision. Lower interest expense following the redemption of the remaining 2029 notes should help at the margin. Updates on Austin Chalk wells, Uinta drilling costs and new Permian zones will matter for the longer view, especially since management has signaled a slight production decline in 2027 as Permian spending resets toward maintenance.
The stock has already priced in much of the good news. Shares are up nearly 20% since the last report while the S&P 500 was flat, and at $13.83 the stock trades comfortably above its 200-day moving average of $11.85, though roughly 11% below its post-earnings high of $15.47. Sentiment has shifted from mildly bearish to essentially neutral, a modest improvement rather than outright enthusiasm.
Ultimately, this report hinges on whether Crescent can show that cost savings and synergy capture are still compounding fast enough to carry earnings through a planned production soft patch. If synergies keep climbing and spending stays flat, the dip will look like the timing issue management described. If costs stall alongside volumes, the elevated whisper and recent rally leave little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-15 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Aug-17 | |
| Aug-04 | |
| Aug-04 |
