Crescent Energy Beats On EPS And Revenue, But The Devon Eagle Ford Deal Shifts The Story From Payouts To Scale And Deleveraging
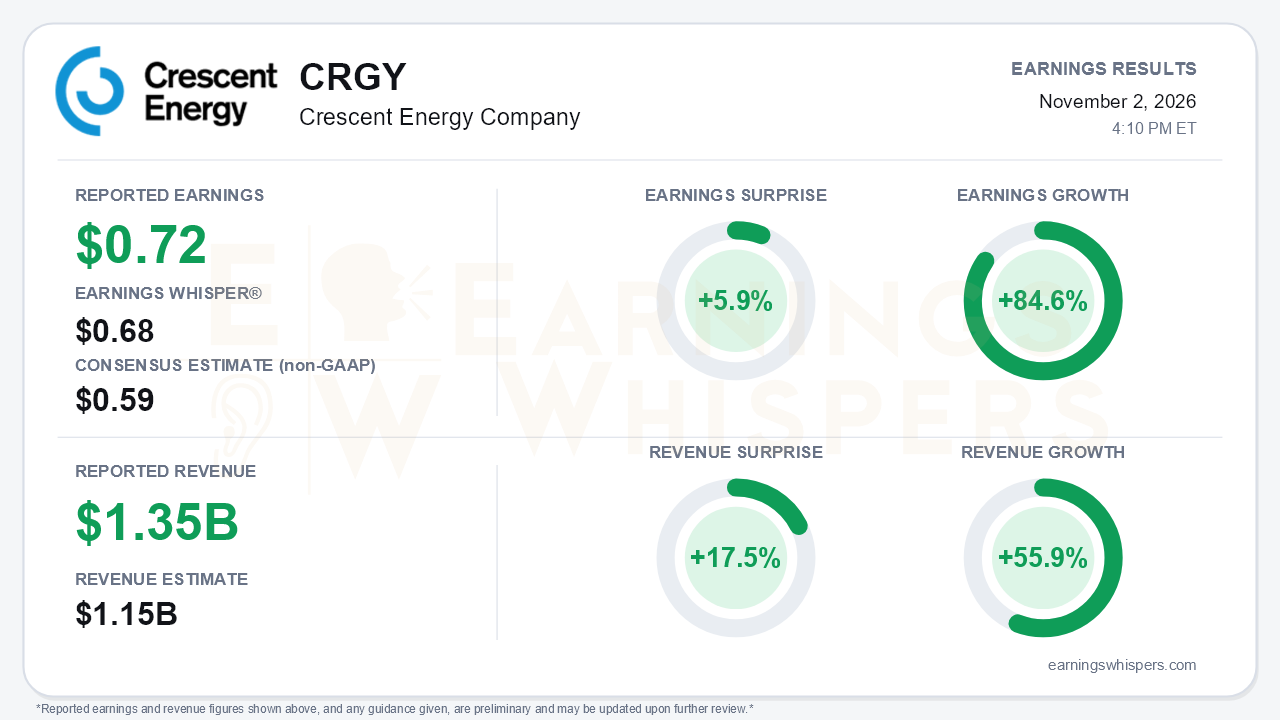
Crescent Energy delivered a clean third-quarter beat. It reported earnings of $0.72 per share on revenue of $1.351 billion, ahead of the $0.59 non-GAAP consensus and the $0.68 Earnings Whisper number, for a 5.9% surprise. Revenue topped the $1.15 billion consensus by 17.5%. Year over year, earnings grew 84.6% and revenue grew 55.9%, reflecting the larger asset base Crescent has assembled through acquisitions. Yet the beat is not the main event. The quarter's real significance is the pending acquisition of Devon Energy's Eagle Ford assets. That deal turns Crescent from a company outrunning its own organic targets into one making a transformational, leverage-funded bet on scale. Capital return takes a back seat to debt reduction.
The beat deserves some scrutiny because the year-over-year growth and the sequential trend tell different stories. The press release itself contained little beyond logistics, with figures deferred to a supplemental presentation, so the operating detail comes from the call. That detail shows a business easing off its peak. Standalone production slid from 341 MBoe/d in the first quarter to 335 in the second and 328 in the third. Oil volumes held at 140 MBo/d for two quarters before dropping to 134, on a path toward a roughly 130 MBo/d maintenance exit. Levered free cash flow fell from a record $418 million in the second quarter to $367 million. Adjusted EBITDA slipped from $798 million to $786 million. Management framed the volume decline as planned, and it is. Still, the large year-over-year growth figures mask a standalone base that has plateaued and is gently contracting.
What kept the call constructive was execution on cost and capital. Third-quarter capex of $326 million came in roughly 9% better than expected, and levered free cash flow ran about 23% above expectations despite the sequential decline. Full-year capex guidance has steadily improved:
- mid-to-high end of the range in the first quarter;
- midpoint in the second quarter;
- below the midpoint now.
Permian synergies keep climbing. The original target was $90-100 million; roughly $295 million has now been captured, with the goal raised above $300 million. Another $40 million of recontracting benefits is due starting in January 2027. Well costs are down about 25% in the Eagle Ford since 2023, about 20% in the Uinta and 20-25% in the Permian. Management expects further declines in 2027 even as the COO flagged 5-7% inflation in steel and diesel. Sub-$50 breakeven inventory has doubled. Management's tone was notably more expansive, with the claim that Crescent has never been better positioned.
The Devon deal carries both the biggest catalysts and the biggest risks. Management says it adds 600-plus net locations, makes Crescent the No. 2 Eagle Ford operator and brings $140 million of identified annual synergies, including $100 million in drilling and completion. Pro forma, the company expects about 400 MBoe/d, more than 15 years of inventory and over $7.5 billion of levered free cash flow across five years at $70 oil. The royalties business adds another lever. Pro forma EBITDA there is projected at about $250 million, up from about $200 million last quarter, and management is pursuing an IPO-type outcome on an accelerated timeline. The cost is real, however:
- about $1.15 billion of new equity, which dilutes existing holders;
- higher leverage, with roughly 6% debt;
- buybacks displaced by deleveraging targets of about 1.5x by year-end 2027 and 1x by year-end 2028.
Fourth-quarter guidance was not updated pending the close, and minerals volumes dipped from about 13 to 11 MBoe/d. Bears have legitimate ammunition in the dilution, the integration risk and the shrinking standalone volumes.
The market has leaned toward the bulls. Shares at $13.47 are up 16.7% from the open after the August report and sit about 12% above the 200-day moving average of $12.02. Most Earnings Whispers trend readings are positive, though sequential growth is neutral, consistent with the plateau in volumes. Investor sentiment is the more cautious signal. It improved only slightly, from -0.050 to -0.031, and remains marginally negative, suggesting investors have not fully embraced the deal-driven story even as the stock has rallied.
The bottom line is that Crescent beat on both lines and continues to out-execute on synergies and capital efficiency, but the investment case has changed shape. The question is no longer whether Crescent can squeeze more from its existing assets. It is whether a larger, more levered and more diluted company can deliver the Devon synergies, deleverage on schedule and unlock royalty value before declining standalone volumes and cost inflation become the bigger story.
Read our earnings preview for Crescent Energy Company: https://www.earningswhispers.com/article/CRGY/21381
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-23 | |
| Oct-15 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 |
