Hinge Health Faces A Fourth-Raise Test As Cylinder Deal And Migraine Ramp Meet A Soaring Stock
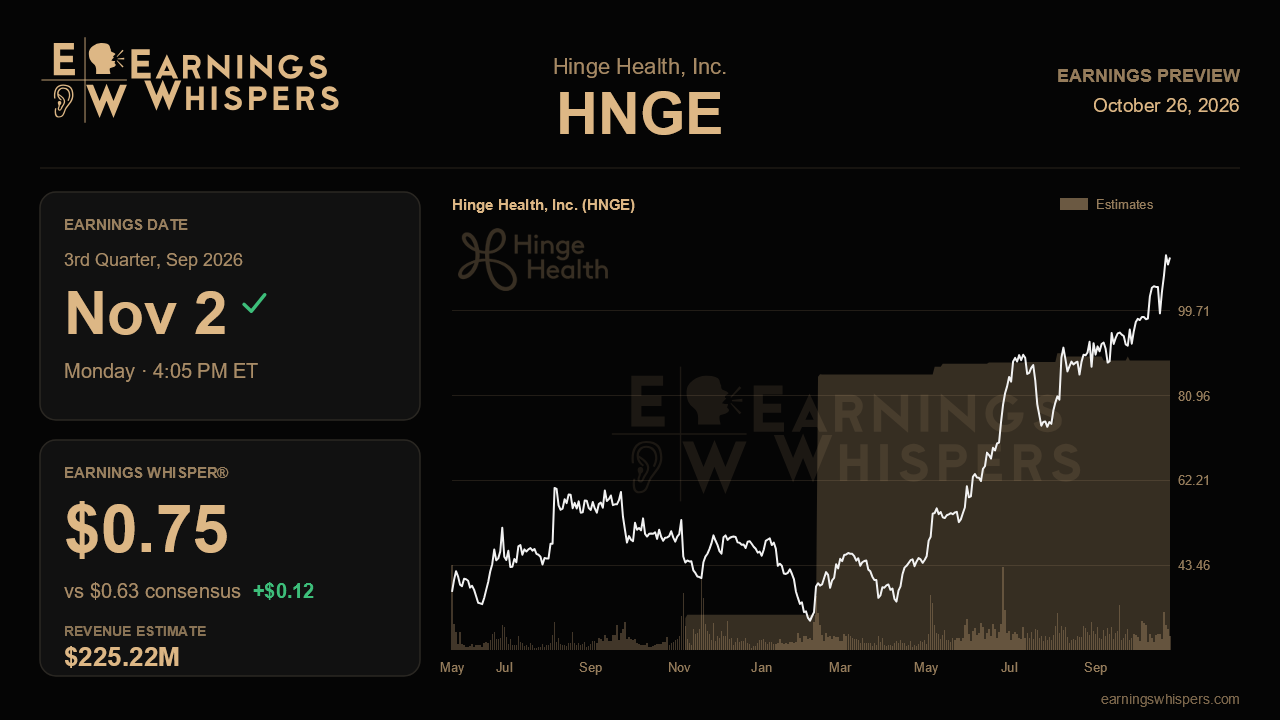
Hinge Health has spent 2026 turning guidance raises into a habit, lifting its full-year revenue outlook on three straight calls. That streak has helped push the stock up roughly 46% since the last report, while the S&P 500 slipped about 2%. The third-quarter release, due after the close on November 2, now has to answer a harder question than whether the business is growing. It must show that the step-up in yield, margins and new conditions can keep outrunning expectations that the market has already priced aggressively.
The Street is looking for non-GAAP earnings of $0.63 a share on revenue of about $225.2 million, which would be growth of roughly 46% from the $154.2 million reported a year ago. That is a slight cooling from the 53% pace of the second quarter, consistent with management's point that growth decelerates on a larger base rather than on softer demand. The Earnings Whisper sits at $0.75, well above consensus and above last quarter's $0.43, a sign that the informal bar is set noticeably higher than the published one. On revenue, consensus sits near the low end of management's third-quarter range of $223 million to $255 million, and the full-year target of $856 million to $860 million was raised from $818 million to $824 million. Given Hinge's record of clearing its own targets, as it did with second-quarter revenue of $213 million against a $200 million to $202 million guide, a print near the bottom of the range would likely read as a disappointment.
The operating story from last quarter rests on yield, the share of each covered life that turns into revenue. Management lifted its full-year yield assumption to about 4.45%, up from just above 4% a quarter earlier and 3.9% exiting 2025. Because the second-quarter beat came entirely from yield, evidence that those gains are durable matters more than headline revenue. Margins tell a similar story. Gross margin reached 87% and operating margin 29%, ahead of the full-year operating income guide of $236 million to $244 million, or about 28%. Holding something close to that level would validate the operating leverage thesis; a sharp step down would raise questions.
The swing factor is Cylinder Health, the $105 million digestive health acquisition and Hinge's first deal. Cylinder runs at a loss, and management framed GI as a long game requiring investment, with the business expected to reach Hinge's margin profile over one to two years. It should add only $7 million to $8 million of revenue across the rest of 2026, so the first look at its cost drag and integration progress is more important than its sales contribution. Migraine is the other test. The program grew from 125 clients and 2 million lives at launch to more than 450 clients and 5 million lives by the second quarter, and continued signups would support the pitch that Hinge is becoming a multi-condition platform rather than a single-condition MSK vendor.
Commercial signals also deserve scrutiny. Management cited a pipeline ahead of last year, record win rates, a Fortune 15 takeaway of about 300,000 lives and SMB lives more than doubling in the first half. With selling-season conversion concentrated in the back half, commentary on billings, which reached $862 million on a trailing basis, and early 2027 bookings will help counter a rival's loud claims about its own win rates.
Sentiment is mildly bearish and essentially unchanged from last quarter, even as the stock trades far above its 200-day average near $65 and within about 2% of its post-earnings high of $113.48. That leaves shares testing a breakout into the report. The narrative stays intact if Hinge clears the high bar on revenue, holds margins near 28% despite Cylinder, and raises full-year guidance a fourth time. Anything less risks being judged against a valuation that already assumes the streak continues.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-26 | |
| Oct-05 | |
| Sep-29 | |
| Sep-12 | |
| Sep-09 | |
| Aug-27 | |
| Aug-26 |
Oura Reportedly Eyes $3 Billion IPO at More Than $16 Billion Valuation
HNGE
Benzinga Private Markets
|
| Aug-21 |
IPO Stock Of The Week: Hinge Health Finds Support At Key Level, Eyes New Buy Points
HNGE
Investor's Business Daily
|
| Aug-19 |
IBD Stock Of The Day, Hinge, Eyes A Fresh Entry On Earnings-Tied Rally
HNGE
Investor's Business Daily
|
| Aug-06 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 |
Read Between These Lines As Eli Lilly, Hot IPO And More Face Key Test
HNGE
Investor's Business Daily
|
| Aug-03 |
