Hinge Health Clears Consensus But Misses The Whisper As Its Third Straight Raise Meets A Stock Priced Near Its Highs
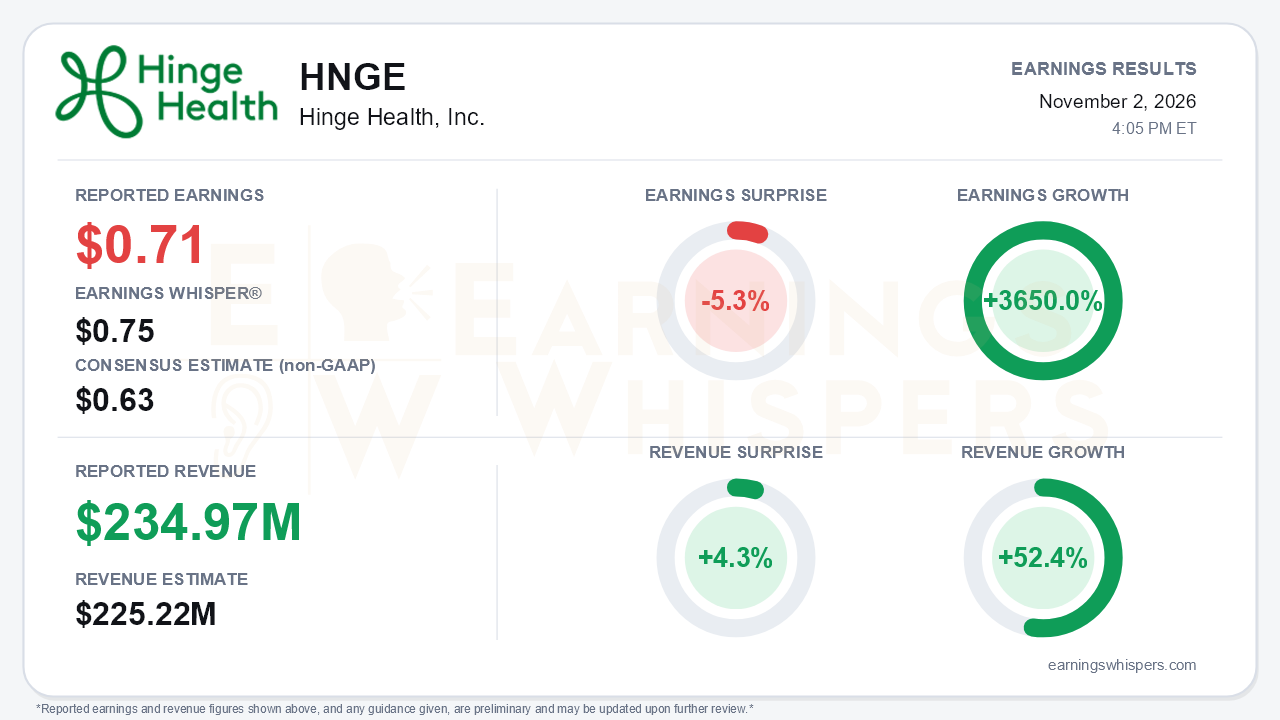
Hinge Health (NYSE: HNGE) delivered another beat-and-raise quarter, but the bar had moved higher than the published consensus. Non-GAAP earnings of $0.71 per share topped the $0.63 consensus. They fell 5.3% short of the $0.75 Earnings Whisper number, so the quarter registers as a miss against the expectations that mattered most. Revenue of $234.97 million beat the $225.22 million consensus by 4.3% and rose 52.4% year over year. Earnings growth came in at 3,650.0% by Earnings Whispers' measure. On a GAAP basis, the company swung to diluted EPS of $0.66 from a $0.02 loss a year earlier. That is the central tension. Operationally, this was arguably the company's cleanest quarter yet. Yet a stock up roughly 50% since the last report needed more than a consensus beat.
The operating detail is hard to fault. Non-GAAP operating income of $77.2 million jumped 154% and blew past management's own $61-63 million guide. Non-GAAP operating margin expanded to 33% from 20% a year ago and 29% in Q2. Gross margin reached 88%, up from 83% a year earlier and 85% in Q1. Operating leverage was broad-based, with non-GAAP sales and marketing falling to 33% of revenue from 37%. The per-share shortfall versus the whisper looks less like an operating problem than a function of below-the-line factors. The company now applies a 24% non-GAAP tax rate versus 20% last year, and other income declined. GAAP net income also benefited from a $3.7 million tax benefit. Cash flow showed one wrinkle. The release reports free cash flow of $112.7 million, a 48% margin, down from 53% a year ago. The call analysis cites $120 million at a 51% margin. Investors should anchor to the release figure.
Beneath the headline, growth is holding rather than fading. Revenue growth of 52% was essentially in line with Q2's 53% and above Q1's 47%. LTM calculated billings rose 54% to $960.3 million, accelerating from 52% in each of the prior two quarters. Clients grew 28% to 3,270. Full-year revenue guidance has now climbed at every call: from an initial $732-742 million, to $856-860 million in August, to $879-881 million today. The new range implies roughly 50% growth versus about 25% originally guided. Full-year non-GAAP operating income guidance rose to $266-268 million, a margin of about 30%. Management's yield assumption has drifted up to 4.6% from roughly 3.9% at the start of the year, and management describes the improvement as structural.
The demand commentary was the strongest part of the call. Verbal agreements year to date already cover more lives than 2025's record 4.8 million, excluding Cylinder. The company added three new Fortune 15 clients and closed about 1 million SMB lives after roughly a year of investment. Migraine access grew to about 9 million lives across 800-plus clients, up from 5 million and 450 clients in Q2, with most launches slated for Q1 2027. Bears still have legitimate ammunition. The Q4 guide implies 46% growth, a step down from 52%. ASP is expected to stay roughly flat through 2026 and 2027, with any uplift deferred to the second half of 2027 or 2028. Management is holding its ~85% gross margin target for 2027 despite the 88% print, which signals reinvestment in care teams. GI and migraine revenue is back-end loaded, and the integrated GI product does not arrive until mid-2027. President Jim Pursley will also step down at year-end and join the board, with Aaryn Pure leading the commercial organization.
Capital deployment was heavy. The quarter included roughly $97 million for Cylinder, about $26 million of buybacks and $97 million in RSU tax withholdings. Cash and investments now stand at $358.5 million.
The market setup is more complicated than the fundamentals imply. Shares closed at $114.32 ahead of the report, up 49.5% from the post-Q2 open. That price sits just 2.7% below a 52-week high of $117.55 set October 29 and roughly 71% above the 200-day moving average. The trend signals remain constructive, with momentum and AVWAP both positive. Investor sentiment, however, remained negative and weakened modestly, slipping to -0.21 from -0.17. Investors were not chasing the story with conviction even as the price ran.
The bottom line is that Hinge Health's business momentum is intact and arguably improving. Billings are accelerating, margins are at records, and the selling season is ahead of last year's record pace. But the stock entered the print priced for a cleaner outcome than a whisper miss, a decelerating Q4 guide and a flat ASP outlook. The fundamental story strengthened. Whether it was strong enough to justify the run is the open question.
Read our earnings preview for Hinge Health, Inc.: https://www.earningswhispers.com/article/HNGE/21397
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 5 hours | |
| Oct-26 | |
| Oct-26 | |
| Oct-05 | |
| Sep-29 | |
| Sep-12 | |
| Sep-09 | |
| Aug-27 | |
| Aug-26 |
Oura Reportedly Eyes $3 Billion IPO at More Than $16 Billion Valuation
HNGE
Benzinga Private Markets
|
| Aug-21 |
IPO Stock Of The Week: Hinge Health Finds Support At Key Level, Eyes New Buy Points
HNGE
Investor's Business Daily
|
| Aug-19 |
IBD Stock Of The Day, Hinge, Eyes A Fresh Entry On Earnings-Tied Rally
HNGE
Investor's Business Daily
|
| Aug-06 | |
| Aug-04 |
