After A 59% Rally, Ibotta Must Prove Its Revenue Turnaround Survives A Timing Dip
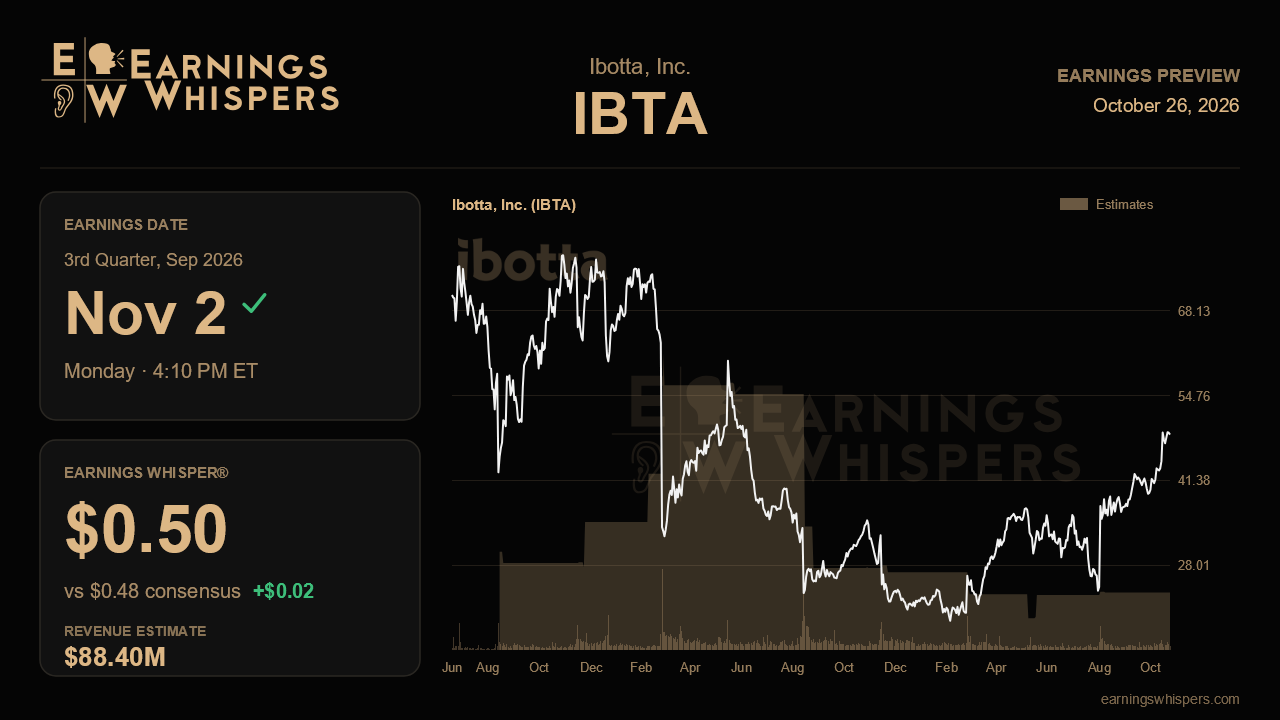
Ibotta heads into its third-quarter report with a problem most turnaround stories would welcome: the recovery arrived early, and the stock has already priced in a good deal of it. Shares have climbed nearly 59% since the company reported a return to revenue growth a quarter ahead of schedule, while the S&P 500 has gone nowhere. That leaves the November 2 release, due after the close, with a narrower job than it might seem. Ibotta needs to show that the second-quarter inflection was the start of a trend, not a flattering quarter helped by a well-timed retail promotion.
The Street expects revenue of about $88.4 million, up 6.2% from a year ago. That is modest growth, but it would mark the strongest year-over-year gain in this recovery so far, following a 3% rise last quarter and steep declines through 2025. Management guided to $86 million to $90 million, so consensus sits slightly above the $88 million midpoint and inside the upper half of the range. Given that Ibotta has beaten the high end of its guidance three quarters running, that placement looks reasonable rather than aggressive. On earnings, analysts are looking for $0.48 a share, with the whisper number a touch higher at $0.50, a small gap suggesting a bar only slightly above the published estimate rather than a market leaning hard on an upside surprise.
The guidance carries a wrinkle worth understanding. The range implies revenue roughly flat to slightly down from the second quarter's $88.9 million, because Walmart deal days pulled two to three points of growth into the prior period. A sequential dip is therefore baked in and should not be read as a stall. The more telling numbers sit underneath the headline. Third-party redemption revenue, the engine of the Ibotta Performance Network, accelerated to 27% growth last quarter from 12% in the first quarter. Holding growth near that pace would confirm the network is genuinely scaling. So would continued gains in redeemers, which reached 20.9 million, and another positive reading on third-party redemptions per redeemer, which turned up last quarter for the first time since late 2024 and signals healthier offer supply from brands.
The new publishers are where the story can strengthen or wobble. Uber's native offer experience went live only at the very end of the second quarter and Giant Eagle launched in July, so this is the first full quarter in which both should contribute. The 7-Eleven deal, covering more than 11,500 stores across its apps, has not been sized, and convenience stores are a lower-consideration channel where redemption behavior is uncertain. Any detail on launch timing and early engagement will matter more than the revenue it produces this quarter. Meanwhile, the direct-to-consumer business continues to shrink, falling 24% last quarter, and management does not expect it to stabilize this year. The bull case does not require that leg to recover, only that third-party growth keeps outrunning its decline.
Profitability offers the second test. Adjusted EBITDA margin rebounded to 18.6% from 11% in the first quarter, and non-GAAP gross margin improved to 79.3%. Management also raised its full-year target for free cash flow conversion to about 70% of adjusted EBITDA. Margins holding near those levels despite softer sequential revenue would show the operating leverage is structural.
Sentiment has improved but remains guarded, with bearish readings easing to about 32% from roughly 50% ahead of the last report. The stock trades far above its 200-day average near $32 and sits within about 4% of its post-earnings high of $50.54, so the run has largely played out in the price. The central question is simple: can third-party network growth stay strong enough, with fresh publishers ramping and a soft CPG backdrop, to make the second quarter look like a floor rather than a peak?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-14 | |
| Oct-07 | |
| Sep-24 | |
| Aug-26 | |
| Aug-06 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-06 | |
| May-28 | |
| May-28 | |
| May-08 |
