Ibotta Delivers Accelerating Beat, But A Sharp Rally, Falling Unit Pricing And An ~8% Q4 Guide Complicate The Setup
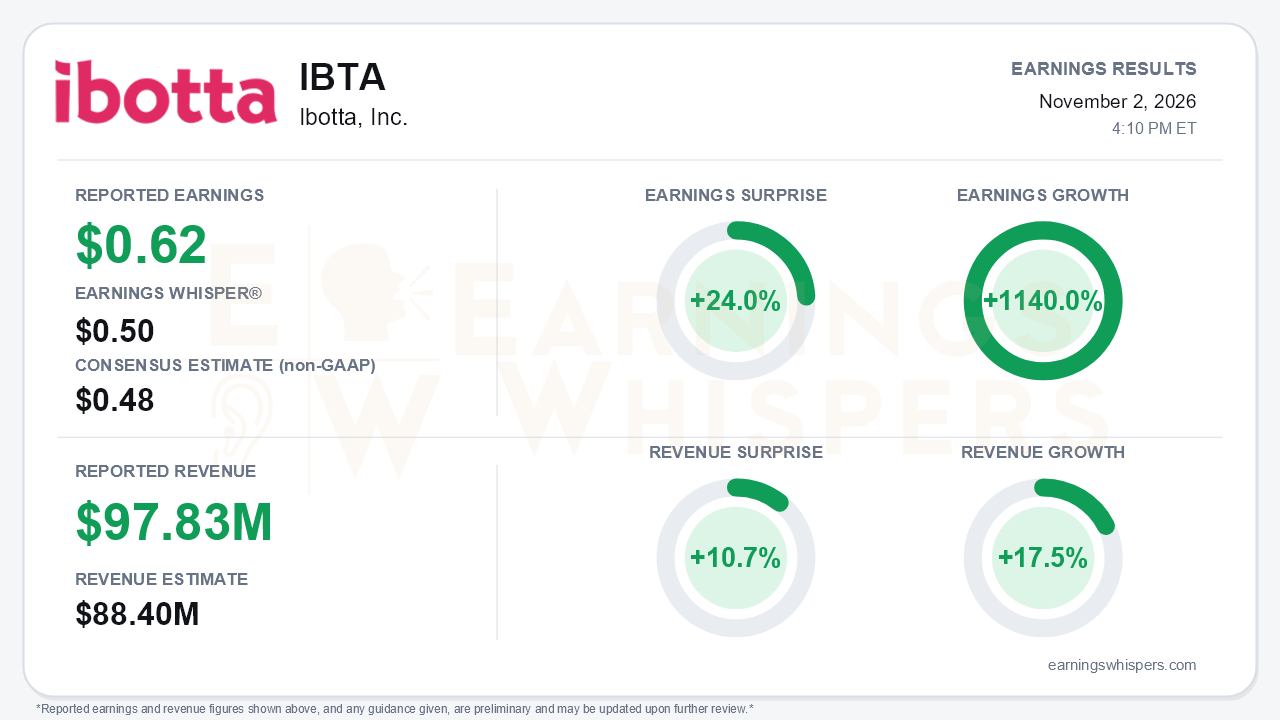
Ibotta's third quarter was its cleanest evidence yet that the business has turned. Non-GAAP earnings of $0.62 per share beat the $0.48 consensus by 24.0% and cleared the $0.50 Earnings Whisper number. Revenue of $97.83 million topped the $88.4 million consensus by 10.7% and grew 17.5% year over year. The acceleration is the real story. Revenue growth moved from -10% in the fourth quarter of 2025 to -2%, then +3%, and now +17%. Adjusted EBITDA of $23.8 million rose 43% and nearly doubled the midpoint of management's $12-14 million guide. This was the fourth straight quarter above the high end of guidance. The central tension is that the market had already priced in much of this recovery, and the outlook shows growth roughly halving next quarter.
The quality of the beat deserves scrutiny. Earnings Whispers calculates EPS growth at 1,140.0%, a figure that reflects a very small year-ago base. The company's own reconciliation shows non-GAAP EPS up a more modest 11%, from $0.56. Non-GAAP net income actually fell 2% to $16.0 million. The per-share gain came largely from buybacks, which cut the non-GAAP diluted share count to about 25.7 million from 29.4 million. On a GAAP basis, Ibotta swung to a $3.5 million net loss ($0.15 per share) from a $1.5 million profit. That swing was driven by a $9.6 million tax provision, not by operations. Operating income doubled to $4.7 million, and free cash flow rose to $16.8 million from $10.6 million. Investors should therefore read the quarter as genuine operating improvement, while recognizing that the headline growth rate flatters it.
Beneath the surface, Ibotta is growing volume much faster than it is growing revenue. Third-party publisher redemption revenue rose 43% to $70.7 million. Redeemers climbed 30% to 23.6 million, the largest quarterly addition since late 2023. Total redemptions jumped 40%. Redemptions per redeemer grew 8%, its first year-over-year increase since the network model took hold, which suggests advertiser offer supply is finally catching up with consumer demand. Non-GAAP gross margin improved to 80.7%. The offset is pricing. Revenue per redemption fell 13% to $0.76, a steeper drop than the 4% decline in the second quarter, because of a mix shift toward lower-priced food items and pricing actions. Management signaled further declines ahead. The legacy direct-to-consumer business also keeps shrinking: its redemption revenue fell 22% and ad and other revenue fell 17%.
The call offered more forward catalysts than Ibotta has typically provided:
- A large food manufacturer that had lapsed returned to the top five clients, spending more than ten times its full-year 2025 total in the third quarter alone.
- Giant Eagle went live during the quarter. 7-Eleven, Speedway and Festival Foods launched after quarter-end, with 7NOW still to come.
- A Danone pilot of Ibotta's LiveLift measurement tool showed more than $3 of incremental return per dollar spent, validated by Circana.
- A next-generation LiveLift product suite is slated for 2027.
The guidance is where bears have legitimate ammunition. Fourth-quarter revenue of $94-98 million implies only about 8% growth. Management cited the third quarter as the easiest comparison and pointed to shifting seasonality. The adjusted EBITDA guide of $15-17 million implies margin falling back to roughly 16.7% from 24.3%. Management also gave its first-ever annual view, calling for 2027 revenue growth of at least mid-single digits, which some analysts viewed as below their expectations. The pending Instacart–DoorDash merger adds publisher-concentration uncertainty, and the release continues to flag the Walmart relationship as a risk factor.
Market positioning raises the stakes. Shares had climbed 58.8% from the $30.61 open after the August report to $48.62 as of October 30. That left the stock about 48% above its 200-day moving average and just 3.8% below the $50.54 52-week high set on October 22. Ibotta entered the report near the top of its inter-earnings range, not as a neglected recovery story. Investor sentiment improved meaningfully, from -0.50 to -0.29, but it remains negative, a sign that skepticism has eased rather than disappeared. Earnings Whispers trend readings are mostly positive, although sequential growth is only neutral.
The bottom line is that Ibotta delivered a decisive operating beat, with third-party volume, engagement and new publisher launches all pointing in the right direction. Capital returns are also real: the company repurchased $14.4 million of stock in the quarter, though cash declined to $149.9 million from $186.6 million at year-end. Against that, falling revenue per redemption, a guide that implies about 8% growth, and a conservative 2027 floor arrive after a near-60% run. The fundamental story improved, but the bar for the next leg is considerably higher than it was in August.
Read our earnings preview for Ibotta, Inc.: https://www.earningswhispers.com/article/IBTA/21401
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| Oct-26 | |
| Oct-14 | |
| Oct-07 | |
| Sep-24 | |
| Aug-26 | |
| Aug-06 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-06 | |
| May-28 |
