Independence Realty's Leasing Turn Faces Proof Test As Shares Slide Below Key Average
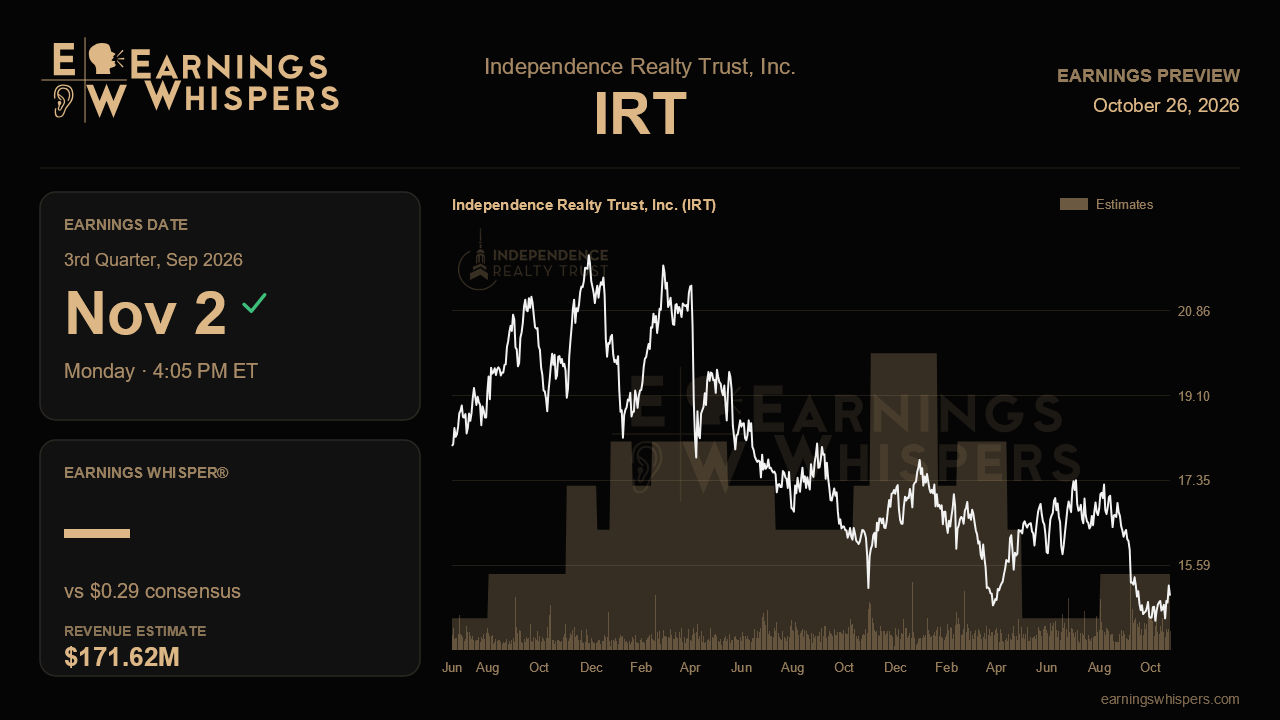
Independence Realty Trust heads into its third-quarter report with an odd disconnect. Last quarter management sounded more confident than it had in years, describing new lease rates on like-term leases turning slightly positive in August for the first time this cycle and lifting its same-store NOI outlook. The market has responded by marking the stock down 12% since that call, while the S&P 500 was essentially flat. Either investors doubt the leasing recovery will hold through the seasonally softer fall months, or they are focused on the part of the story that didn't improve: per-share cash earnings.
The bar itself is modest. Wall Street expects earnings of $0.29 per share on the basis it tracks, flat with a year ago and a penny above the prior quarter, on revenue of roughly $171.6 million, up about 2.7% year over year and a healthy step up from the $167.2 million posted last quarter. That revenue jump matters because it should begin to capture the community Wi-Fi rollout, which management said was running ahead of plan and on track for about $5.5 million of second-half revenue. On full-year guidance, the company narrowed its core FFO range to $1.13 to $1.15 per share, and consensus at $1.14 sits squarely at the midpoint. Nobody is pricing in heroics, which means the quality of the operating data will likely matter more than the headline number.
The central question is whether the leasing curve kept bending. Management walked new lease tradeouts from negative 3.9% in the first quarter to negative 2.7% in the second, negative 1.1% in July and slightly positive in August, while renewals climbed to 4.6% and blended rent growth reached 2.5% in July. A third-quarter print showing blended rents holding above 2%, new leases staying near or above break-even into September and October, and renewals still in the mid-4% range would validate the inflection story. Slippage back into clearly negative new-lease territory, or a renewal pullback, would suggest the summer gains were seasonal rather than structural. Concessions are a useful tell: they fell from more than half of new leases in April to roughly a quarter in July, but Dallas and Tampa were still near 40%, so progress in those two markets would show the supply overhang is actually clearing.
The flip side is the earnings bridge. Management raised same-store NOI guidance by 70 basis points to 1.5% and cut expense growth expectations to 2.0%, yet held the FFO midpoint flat because higher interest costs and a weaker lease-up at the Tisdale at Lakeline Station joint venture in Austin ate the extra $2.5 million of NOI. That lease-up, just 42% occupied in July with stabilization pushed to early 2027, deserves scrutiny; further delay would chip at non-same-store income again. So would any change in interest assumptions, which had baked in a September rate hike. Investors should also look for progress on the Stonebridge Crossing sale in Memphis and the path toward leverage in the mid-5s, which could free capital to restart buybacks that were paused in the second quarter. Bad debt, still running around 95 to 110 basis points, and occupancy, which management let slip to 95.0% in favor of rate, round out the risk list.
Sentiment has soured noticeably. The Earnings Whispers reading has moved to 38.3% bearish from just 8.9% bearish ahead of the last report. At $14.96, shares sit below the 200-day moving average of $16.13 and near the bottom of their post-earnings range of $14.33 to $17.35, a lower band than the prior quarter's $15.66 to $17.70. That pessimism lowers the hurdle somewhat, though it does not guarantee a favorable reaction.
Ultimately, this report hinges on whether improving rents can finally show up in per-share earnings rather than being absorbed by financing costs and lease-up drag. If leasing held firm and management can point to an FFO trajectory that bends upward into 2027, helped by Wi-Fi and value-add renovations, the recent selloff may look premature. If rents fade and the offsets keep growing, the recovery narrative will look more like a revenue story than an earnings one.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-14 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-14 | |
| Sep-10 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-08 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 |
