Independence Realty Trust Matches Estimates As Leasing Accelerates, But The Centerspace Deal And Rising Costs Keep Investors Skeptical
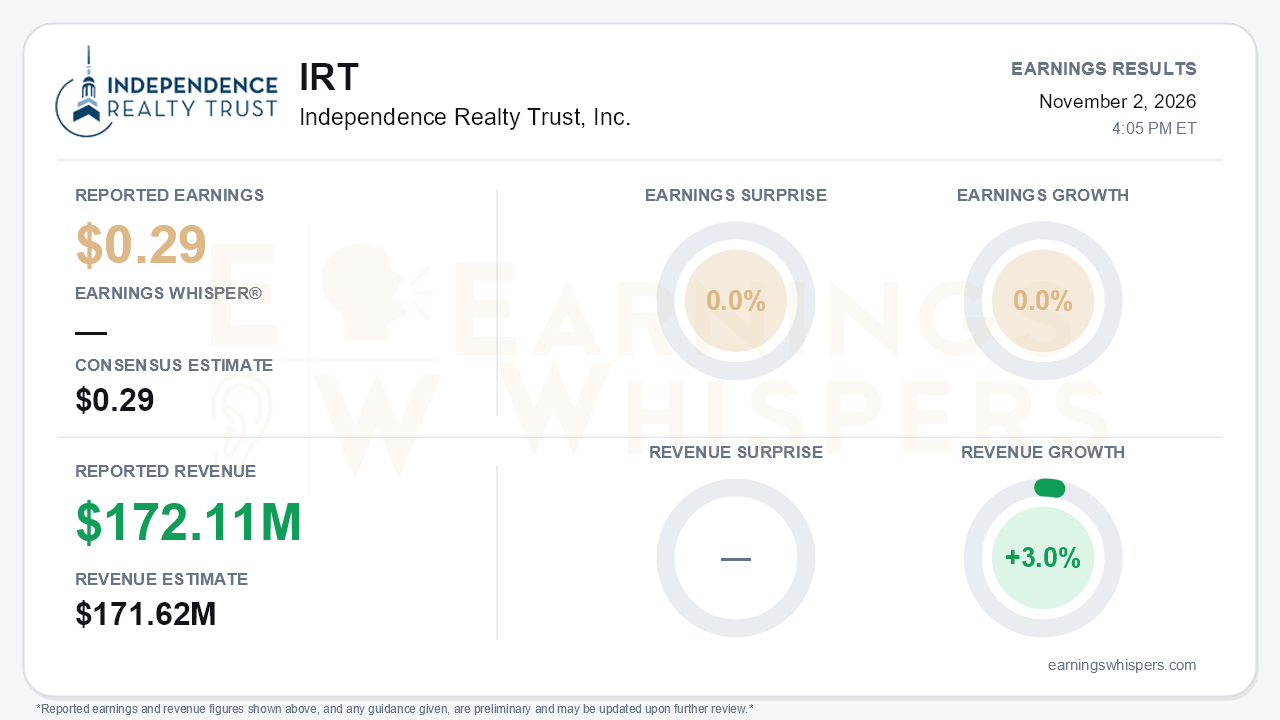
Independence Realty Trust (NYSE: IRT) delivered an in-line third quarter. Core FFO of $0.29 per share matched consensus exactly and was flat year over year. Revenue of $172.11 million edged past the $171.62 million estimate by 0.3% and grew 3.0%. The headline is unremarkable. The leasing data beneath it is not: IRT's rent trajectory improved more sharply this quarter than at any point in the past year. That is the central tension. Operating momentum is building just as investors have soured on the stock, largely because of the pending Centerspace merger.
The quality of the reported numbers deserves some scrutiny. GAAP EPS jumped to $0.11 from $0.03, but that gain came mostly from a $26.5 million gain on the sale of Stonebridge Crossing in Memphis, not from operations. NAREIT FFO actually slipped to $0.27 from $0.30 a year ago. That decline reflects $6.2 million of merger and integration costs, which management excludes from core FFO. The full-year guidance shows the same split:
- **Core FFO** guidance held at $1.13 to $1.15.
- **GAAP EPS** guidance fell to $0.18 to $0.20 from $0.22 to $0.27.
- **FFO** guidance fell to $1.13 to $1.15 from $1.16 to $1.18, reflecting deal costs and slightly lower expected gains.
The same-store NOI range was only narrowed to 1.2% to 1.8%, keeping the midpoint unchanged after the raise in the second quarter. This was a reaffirmation, not an upgrade.
The operating story is where the quarter earned its credibility:
- **Blended rents:** Like-term blended rent growth reached 2.8%, compared with 1.3% in the second quarter and 0.1% a year earlier. It was the best result in five quarters.
- **New leases:** Trade-outs improved to -0.6% from -2.7% sequentially, a 310-basis-point year-over-year improvement.
- **Renewals:** Renewal spreads climbed to 4.6% from 4.1%.
- **Retention:** Resident retention rose 240 basis points sequentially to 60.5%.
- **Revenue:** Same-store revenue growth more than doubled to 2.0% from 0.9% in the second quarter. Other property revenue helped, including $2.3 million of Wi-Fi income versus $0.4 million the prior quarter.
- **Demand:** On the call, management said concessions on new leases were cut nearly in half from the second quarter, lead volume is up 11% year over year, and bad debt is falling in every market.
Bears still have legitimate ammunition. Same-store operating expenses rose 2.5%, up from 0.5% in the second quarter, and controllable costs rose roughly 4% on Wi-Fi contract costs. As a result, NOI growth of 1.6% lagged revenue growth, and the NOI margin slipped 20 basis points to 63.2%. Average occupancy fell 40 basis points year over year to 95.0%, and average rent rose just 0.6%. Weak spots remain:
- Dallas new leases are still running at -3.5%.
- Tampa continues to face supply pressure.
- The Tisdale lease-up still relies on concessions.
Management also trimmed two targets. The 2026 value-add count is now tracking about 2,200 units, down from the 2,500 cited last quarter. The mid-5s year-end leverage target is now likely to be missed after the Mustang joint-venture buyout, with low-5s pushed out 12 to 18 months. Net debt to adjusted EBITDA did improve to 6.2x from 6.5x.
The forward story now runs through Centerspace. The all-stock deal pays 3.800 IRT shares per Centerspace share and creates a roughly 44,400-unit, $8 billion enterprise-value REIT. Management projects about 5% core FFO accretion on $24 million of synergies. The shareholder vote is set for November 10, and closing could come as early as year-end. Proxy advisors back the deal, and Fitch and S&P reaffirmed IRT's investment-grade ratings. Management also outlined a pipeline of growth levers:
- An estimated 2027 earn-in of about 80 basis points, compared with roughly zero last year.
- A Wi-Fi rollout to at least 7,000 more units.
- About 3,200 Centerspace units identified for value-add renovation.
The risks are concrete. IRT needs roughly $140 million of dispositions to keep the deal leverage-neutral, and buyers are pushing cap rates higher. Centerspace's Denver exposure adds supply risk, and integration execution remains unproven.
The market has not been rewarding the plan. Shares have fallen 12.1% since opening at $17.00 after the August report, to $14.94, about 7% below the 200-day moving average of $16.06. Investor sentiment weakened meaningfully, falling from roughly neutral at -0.09 to -0.32. That suggests the merger announcement deepened skepticism rather than easing it. The Earnings Whispers trend signals are mixed: sequential growth and momentum readings are positive, while price and AVWAP trends remain negative. That split mirrors the gap between improving fundamentals and a reluctant stock.
The bottom line is that IRT posted a quarter whose in-line headline understates a genuine acceleration in leasing, while rising expenses, slipping leverage and renovation targets, and a transformative merger give skeptics reasons to wait. If concessions keep burning off and the Centerspace integration delivers its promised accretion, 2027 could look materially better than 2026. For now, investors are demanding proof of execution before giving credit for the improving rent trends.
Read our earnings preview for Independence Realty Trust, Inc.: https://www.earningswhispers.com/article/IRT/21405
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-14 | |
| Oct-01 | |
| Sep-30 | |
| Sep-29 | |
| Sep-14 | |
| Sep-10 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-09 | |
| Sep-08 |
