Jazz Must Prove Its Xywav Surge Is Durable After A Raise The Market Has Shrugged Off
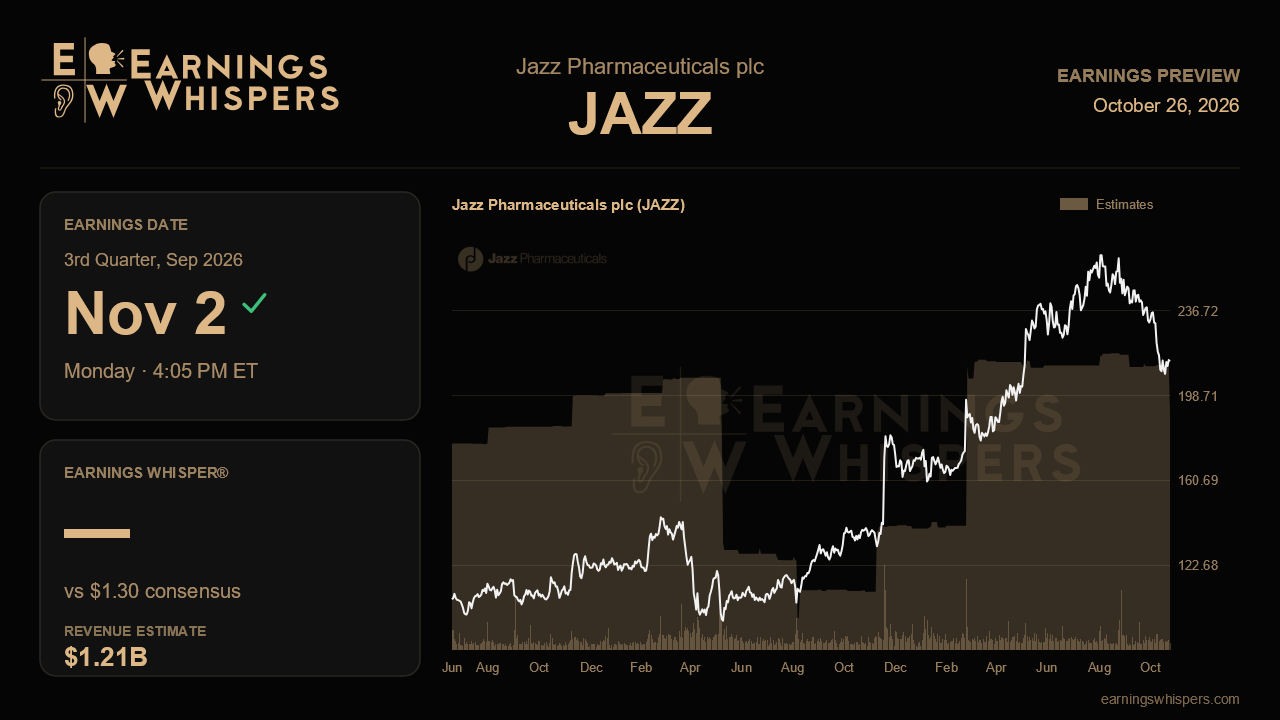
Three months ago Jazz Pharmaceuticals delivered the kind of quarter companies hope for: record revenue, a first genuine full-year guidance raise and a flagship sleep franchise that was supposed to be under siege but instead posted its best patient growth in a year. The stock has since fallen 16.2% while the S&P 500 was essentially flat. That gap is the story heading into the third-quarter report on November 2, after the close. Either the market doubts the second-half sleep story will hold, or it is offering investors a discount on momentum that has not yet faded.
The Street is looking for GAAP earnings of $1.30 per share on revenue of $1.21 billion. That top line would be up 7.5% from a year ago, a solid but clearly slower pace than the 16% growth posted last quarter, and it would be flat sequentially. GAAP figures have swung widely for Jazz, from $6.99 a year ago to $4.63 last quarter, so revenue and segment trends are the cleaner signal. The more telling comparison is with guidance. Management lifted its 2026 revenue outlook to $4.60 billion to $4.75 billion from $4.25 billion to $4.50 billion, yet full-year consensus sits around $4.49 billion, below the bottom of the new range. With first-half revenue of roughly $2.28 billion, the guide implies about $1.16 billion to $1.24 billion per quarter for the rest of the year, so the $1.21 billion quarterly estimate is comfortably inside it. The Street looks cautious relative to the company, which leaves room for upside if management's confidence proves justified.
That confidence rests heavily on Xywav. Earlier this year management framed the second half as a period of mounting pressure from high-sodium generics and potential orexin-based competition, guiding Xywav to flat or mid-single-digit growth. Last quarter it reversed course, calling for double-digit growth and raising rare sleep revenue guidance to $2.025 billion to $2.125 billion after generic uptake proved quite limited and net patient additions climbed to roughly 525. This report is the first real test of that pivot. Another quarter of net adds near or above that level would validate the raise; a sharp drop, or any sign that generic volume is accelerating, would suggest the market's skepticism was warranted.
Oncology is the second leg. The portfolio grew 32% last quarter, with Zepzelca at $106 million and Medeso at $48 million on more than 600 patients. Zepzelca faces a planned removal of its second-line indication this quarter, so the question is whether first-line maintenance, now carrying a top-tier treatment guideline endorsement, keeps offsetting the erosion. Zanidatamab is the bigger swing factor. Management described the gastroesophageal cancer approval as being in the home stretch ahead of its August 25 decision date and said it was launch-ready, and an interim overall survival readout for the doublet regimen was due this quarter. Early launch metrics and any update on that data will shape how investors value the pipeline beyond sleep.
The costs of that ambition matter too. Gross margin is drifting lower as royalty-bearing oncology sales grow, SG&A guidance was nudged up for launch spending, and the tax rate ran above plan. None of these undermines the thesis alone, but together they determine how much revenue upside reaches the bottom line. A slip in the Medeso trial readout to the first half of 2027 is a smaller timing issue unlikely to move this quarter.
Sentiment has cooled, with bullish readings falling to 25.2% from 37.9% a quarter ago. The stock trades at $214, just below its 200-day moving average and only about 3.5% above its post-earnings low of $206.71, far from the $266.38 peak reached after last quarter's report. Expectations, in other words, have reset lower. The central issue is simple: if Xywav keeps adding patients against generic competition and the zanidatamab launch starts cleanly, the raised guidance looks credible and perhaps conservative. If sleep momentum stalls, last quarter's optimism will look like a high-water mark.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-23 | |
| Oct-19 | |
| Oct-15 | |
| Oct-07 | |
| Sep-30 | |
| Sep-15 | |
| Sep-08 |
Quoin in line for priority review voucher if rare paediatric drug approved
JAZZ
Pharmaceutical Technology
|
| Sep-08 |
Quoin in line for second priority review voucher if rare paediatric drug approved
JAZZ
Pharmaceutical Technology
|
| Sep-02 | |
| Sep-01 | |
| Aug-31 | |
| Aug-27 | |
| Aug-26 | |
| Aug-25 |
