Jazz Pharmaceuticals Beats As Revenue Guidance Rises Again, But Slowing Growth And An Actio Charge Leave The Stock At A Crossroads
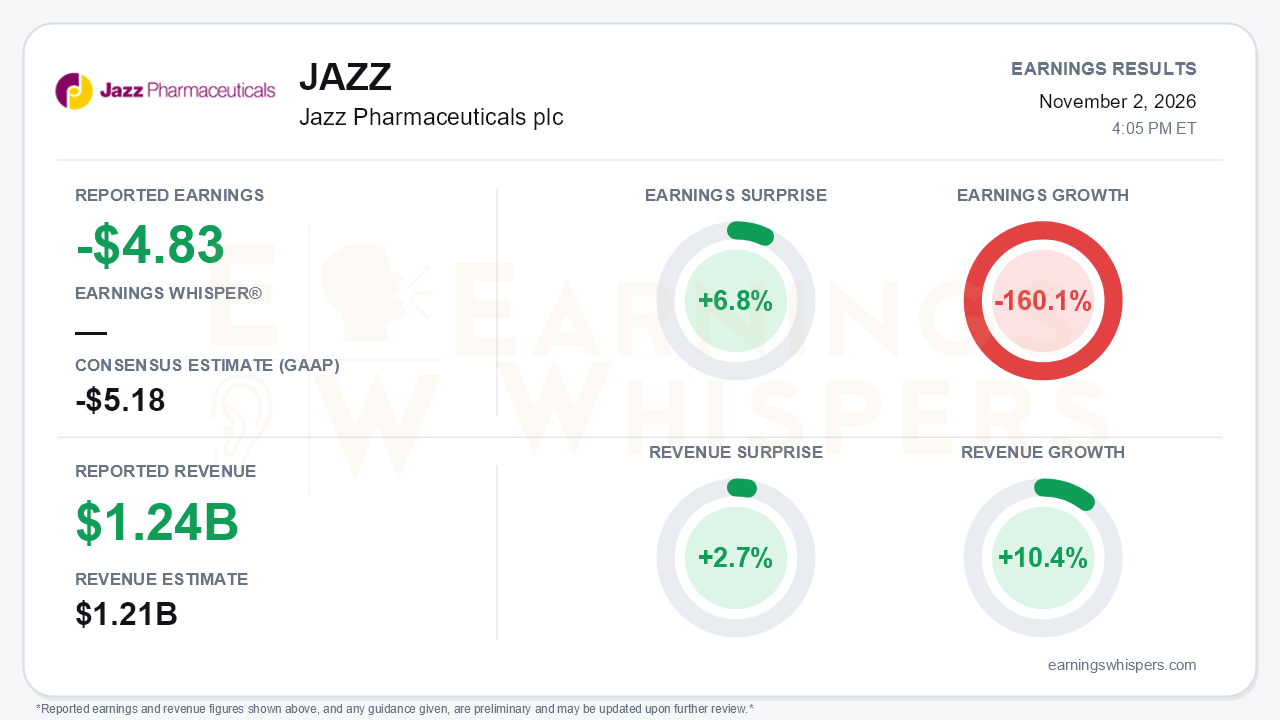
Jazz Pharmaceuticals delivered a better-than-feared third quarter and raised its full-year revenue outlook for the second straight quarter. Earnings Whispers puts the result at a loss of $4.83 per share, 6.8% better than the GAAP consensus of a $5.18 loss. Revenue was a record $1.243 billion, up 10.4% from a year earlier and 2.7% above the $1.21 billion consensus. On the bottom line, earnings fell 160.1% year over year, a swing from a sizable profit to a loss. That swing came almost entirely from the $754 million acquired IPR&D charge for the Actio acquisition, which the company says cost $11.32 per share on a GAAP basis and $11.03 per share on an adjusted basis. The company's own figures were a GAAP loss of $7.48 and an adjusted loss of $3.88, so the normalized Earnings Whispers figure sits on a different basis than either. Excluding the Actio charge, the call analysis put earnings at $7.15 per share. The central tension is that the commercial business keeps outrunning guidance even as headline growth decelerates and several oncology assets lose momentum.
The guidance raise is the strongest part of the quarter. Jazz now expects 2026 revenue of $4.775 billion to $4.85 billion. The new low end sits above the prior $4.60 billion to $4.75 billion range, and the outlook is well above the $4.25 billion to $4.50 billion the company started the year with. The quality of the beat still deserves scrutiny. Revenue growth has slowed from 19% in the first quarter to 16% in the second and 10% in the third. Management said third-quarter growth absorbed a roughly nine-point U.S. oncology headwind from one fewer shipping week, which softens the deceleration but does not erase it. Royalty revenue from the high-sodium oxybate authorized generic also fell to $38.4 million from $52.9 million.
Sleep remains the engine. Xywav sales rose 12% to $483 million on about 425 net patient adds, ending the quarter with roughly 17,550 active patients. Management lifted full-year Xywav growth guidance to low double digits to low teens, compared with flat to mid-single digits in the original plan. It also raised rare sleep guidance to $2.125 billion to $2.175 billion. Oncology grew 35%, but the details are uneven:
- **Zepzelca** rose 32% to $104 million, slowing from 42% growth in the second quarter. Its second-line indication has been removed from the label.
- **Modeyso** posted $61 million, but that included a $14 million inventory build by its Japan partner. Management guided to a "more measured" pace after a summer dip in new patient starts.
- **Epidiolex** slipped 2% year over year to $295 million, which the company attributed to gross-to-net and inventory comparisons.
Margins tell a mixed story. Adjusted gross margin fell 110 basis points to 91.5% on higher royalties. Even so, management raised full-year adjusted gross margin guidance by 50 basis points and held SG&A and R&D guidance steady.
The forward catalysts lean toward Ziihera. The drug won first-line HER2-positive GEA approval on August 25. September brought a threefold increase in new ordering accounts, 80% of them community-based, and roughly a 40% rise in average demand vials per selling day. Final HERIZON-GEA-01 data showed a triplet overall-survival hazard ratio of 0.65 and median survival of 27 months. Management framed peak sales potential at $3 billion to $5 billion, and the $21 million in third-quarter sales is only a starting point. Data on ABS-1230, the Actio asset, are due this quarter. The Epidiolex capsule has an April 16, 2027 PDUFA date. Bears have legitimate ammunition, however:
- Management expects Amgen's Imdelltra to pressure Zepzelca in 2027.
- Orexin-2 agonists could lengthen the time to oxybate initiation in narcolepsy type 1.
- Chief commercial officer Sam Pearce is retiring.
The balance sheet is active but manageable. Jazz holds $2.9 billion in cash against $5.6 billion of debt. It issued $1.25 billion of exchangeable notes, repurchased $225 million of stock, and authorized a new $500 million buyback.
The market setup is more complicated than the surprise implies. As of the October 30 snapshot, shares stood at $215.98, down 15.4% from the open after the August report. They hit a 52-week high of $266.38 on the day of the Ziihera approval and then fell to a quarter low of $202.30 on October 28. The stock entered the report essentially sitting on its 200-day moving average of $216.40 and in the lower third of its inter-earnings range. Investor sentiment was roughly unchanged at 0.372 versus 0.379 and remains moderately positive. That suggests expectations were not euphoric despite the guidance momentum. The internal trend readings are mixed, with sequential growth and momentum positive while AVWAP remains negative, reflecting a stock that has sold off from its post-approval peak.
The bottom line is that Jazz's core franchise, led by Xywav, is performing well enough to justify a second consecutive guidance raise, and the Ziihera launch gives the story a credible new growth leg. Against that, decelerating headline growth, a softer trajectory for Modeyso and Zepzelca, competitive threats in 2027, and an acquisition-driven loss explain why the stock has given back its August gains. Investors now need Ziihera's early demand and the upcoming ABS-1230 data to show that the next phase of growth can offset the assets that are slowing.
Read our earnings preview for Jazz Pharmaceuticals plc: https://www.earningswhispers.com/article/JAZZ/21407
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 12 hours | |
| Oct-30 | |
| Oct-26 | |
| Oct-23 | |
| Oct-19 | |
| Oct-15 | |
| Oct-07 | |
| Sep-30 | |
| Sep-15 | |
| Sep-08 |
Quoin in line for priority review voucher if rare paediatric drug approved
JAZZ
Pharmaceutical Technology
|
| Sep-08 |
Quoin in line for second priority review voucher if rare paediatric drug approved
JAZZ
Pharmaceutical Technology
|
| Sep-02 | |
| Sep-01 |
