Metallus Needs Melt Shop Gains To Turn A Swelling Order Book Into Profit
Metallus has spent 2026 climbing out of a deep hole, and the third quarter will test whether that recovery is turning into real earning power or merely bigger revenue. Adjusted EBITDA went from a shutdown-impaired $2.4 million in the fourth quarter of 2025 to $24.6 million in the first quarter and $29 million in the second. Management guided for another modest step up. The order book is up roughly 50% from a year ago and lead times now stretch into late in the fourth quarter. Demand is clearly not the problem. The open question is whether the Canton mill can run well enough to convert that demand into wider margins.
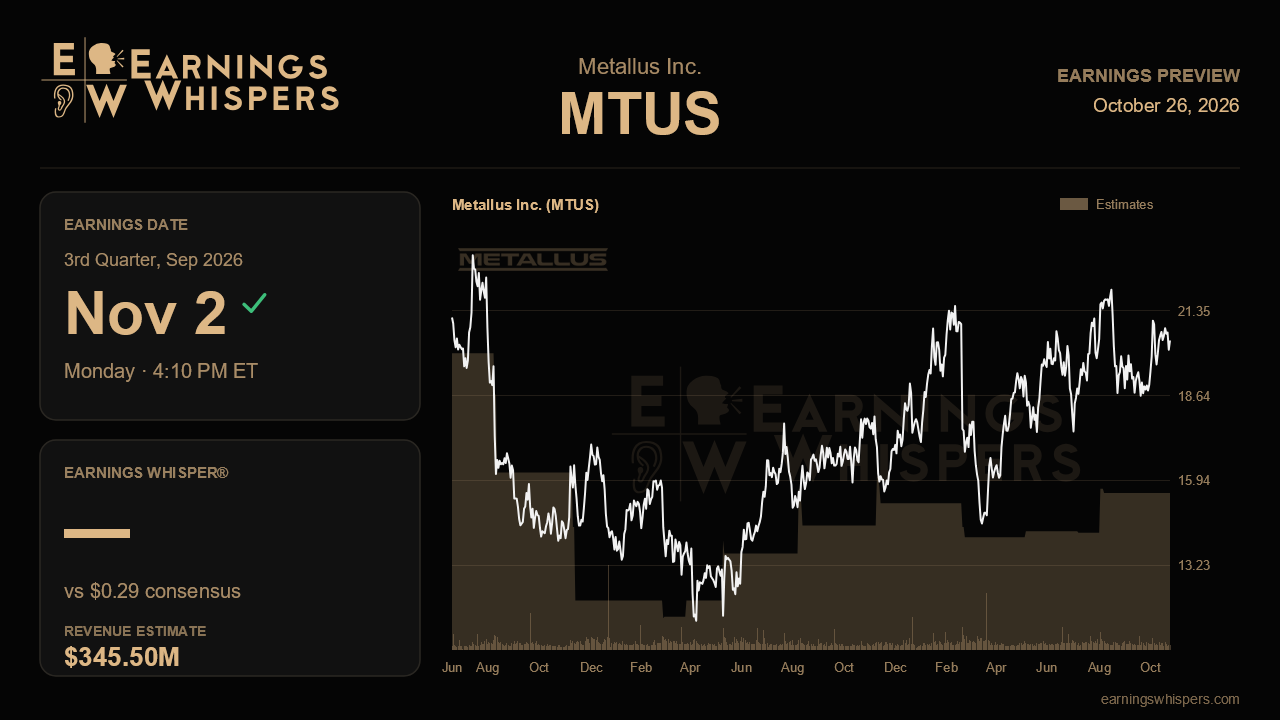
When Metallus reports after the close on November 2, Wall Street expects earnings of $0.29 per share on revenue of $345.5 million. That revenue figure is about 13% above the year-ago $305.9 million, but per-share earnings are forecast to rise only about 3.6% from $0.28. That gap tells the story. Analysts are assuming most of the top-line gain gets eaten by costs. Sequentially, the Street is looking for only a slight revenue increase from the second quarter's $341 million and a few cents of EPS improvement from $0.26. That lines up with management's call for slightly higher EBITDA and leaves little room for disappointment, but also little need for heroics.
The cost side is where the quarter will be won or lost. Melt utilization was just 74% last quarter, below internal plan. Management singled out maintenance reliability and shop-floor execution as the biggest cost lever it has yet to pull. The third quarter also carried more planned outages, higher energy costs and a second full quarter of the new union labor contract. Any improvement in utilization despite those headwinds would validate the narrative that Metallus is becoming a more resilient operator. A flat or lower reading would suggest the backlog is outrunning the plant's ability to deliver profitably. Commentary on the larger maintenance outage planned for the fourth quarter matters too. A bigger-than-expected cost hit there could temper enthusiasm even if the third quarter lands on target.
The growth catalysts deserve scrutiny as well. Aerospace and defense hit record shipments last quarter at roughly a $240 million annualized pace, and management now expects to reach its $250 million target by year-end. Progress toward that number should be visible. So should early benefits from the newly commissioned bloom reheat furnace and the recently earned AS9100D aerospace certification. Price increases of $60 a ton on bar, $100 on carbon tube and $160 on alloy tube took effect in August. The third quarter should show only a sliver of that benefit, with the full impact arriving in 2027. Any early read on 2027 and 2028 contract negotiations, which cover roughly 70% of the annual-agreement book, could matter more than the quarter itself. Cash flow is another check point after operating cash flow slipped to $12.8 million on working capital swings.
Sentiment has warmed noticeably, with the bullish reading rising to 37.6% from 23.4% ahead of the prior report. The stock has not followed. Shares are down about 0.9% since the last report, slightly trailing the S&P 500. At $20.41, the stock sits above its 200-day moving average of $19.11 but roughly 10% below its post-earnings high of $22.58. That puts it in the middle of its recent range rather than pressing for a breakout. The market appears willing to believe the demand story but wants proof on execution before paying up.
The verdict on this report will likely hinge on margins rather than sales. If Metallus shows better melt utilization, steady sequential EBITDA gains and confident commentary on 2027 pricing, the improving narrative stays intact. If revenue grows while costs again absorb the gains, investors may conclude that a record order book is not yet translating into the earnings power they have been promised.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-13 | |
| Sep-30 | |
| Sep-29 | |
| Aug-31 | |
| Aug-31 | |
| Aug-26 | |
| Aug-26 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-14 | |
| May-06 |
