Metallus Beats On Price And Mix As Defense Ramp Outruns Softer Volumes And A Revenue Miss
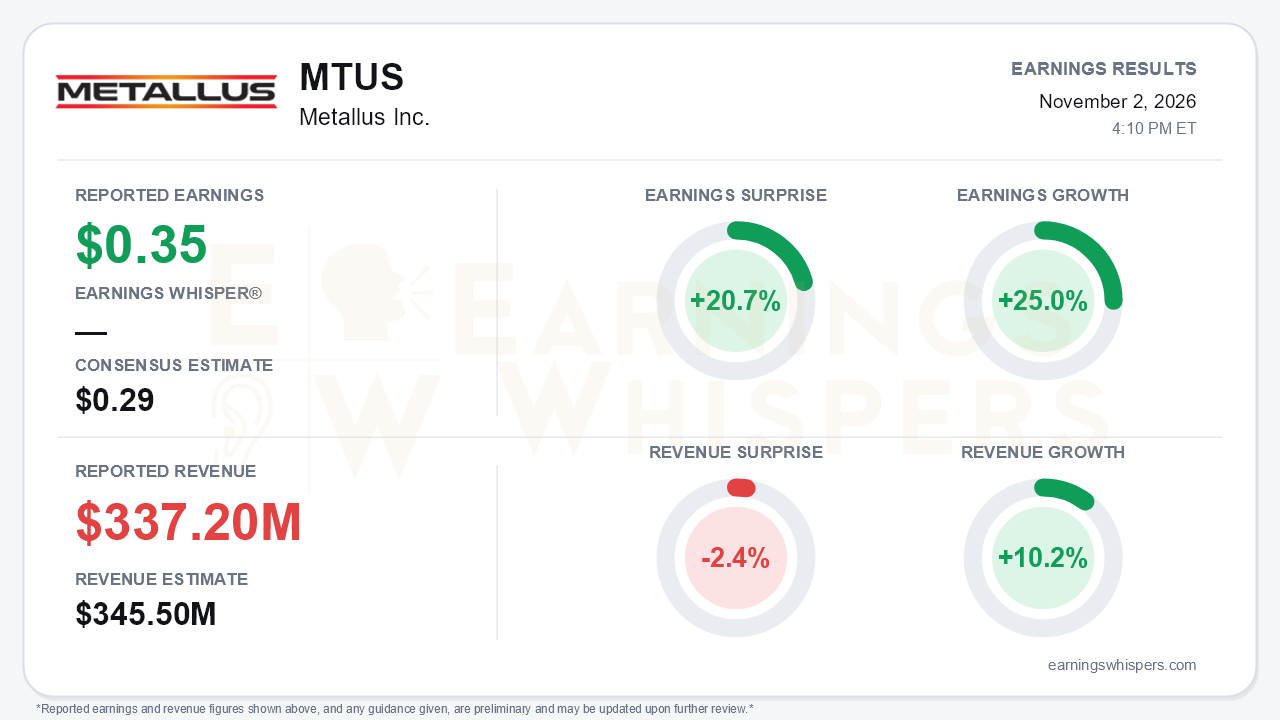
Metallus delivered a quarter in which pricing and mix did the heavy lifting while volume did not. Adjusted earnings of $0.35 per share beat the $0.29 consensus by 20.7% and grew 25.0% year over year. Revenue of $337.2 million rose 10.2% from a year ago but missed the $345.5 million consensus by 2.4% and slipped from $341.0 million in the second quarter. That is the central tension. The specialty steelmaker is shipping fewer tons than investors modeled, but each ton is worth more, and the aerospace & defense business is reshaping the earnings profile faster than management had promised.
The quality of the beat deserves a closer look, starting with the GAAP figures. Net income nearly tripled to $23.8 million, or $0.55 per diluted share, but that included a $15.7 million gain from remeasuring benefit plans. That gain is excluded from the $0.35 adjusted figure, which is the cleaner measure. On that basis the improvement is still real. Adjusted EPS rose from $0.26 in the second quarter. Adjusted EBITDA climbed 19% both sequentially and year over year to $34.5 million, and adjusted EBITDA margin expanded to 10.2% from 8.5% in the prior quarter. The EBITDA walk shows how it happened. Price/mix added $9.6 million sequentially, more than offsetting a $3.7 million volume headwind and a $3.6 million manufacturing drag. Ship tons fell 5% to 165,800, yet base sales per ton rose to $1,567 from $1,501 in the second quarter and $1,484 a year ago.
Aerospace & defense drove that mix shift. Segment shipments rose roughly 34% year over year to about 22,000 tons. Sales increased 41% to $66.4 million, and base revenue in the segment was $2,621 per ton, about double the automotive and industrial levels. The segment now generates about 20% of sales on roughly 13% of tons. Metallus reached its $250 million annualized A&D run-rate target in the third quarter, ahead of the year-end target it had previously given. Elsewhere the picture was softer. Automotive and energy shipments fell sequentially. Industrial shipments declined 3% even though the backlog had nearly doubled at the time of the second-quarter call. Management attributed that shortfall to electricity curtailments, which cost about three points of melt utilization, or roughly 10,000 tons. The order book grew both sequentially and year over year, and lead times for bar and tube now extend into the second quarter of 2027, compared with late 2026 at the prior call.
The forward catalysts strengthened considerably. The new Defense Logistics Agency contract carries an initial $125 million purchase order and a ceiling of up to $995 million over five years, with shipments expected to begin in the second quarter of 2027. Metallus also won a $10 million order from a new defense prime for finished munitions components. In addition, it commissioned government-funded defense assets and announced another $60-per-ton spot price increase effective in October. Management issued its first explicit full-year adjusted EBITDA guide of $100 million to $105 million and framed 2027 as another year of profitable growth. It noted that about 70% of annual contracts were negotiated at higher prices.
Bears still have legitimate ammunition. The full-year guide implies a sharply weaker fourth quarter. Management expects a $10 million to $15 million drag from the annual shutdown, high-single-digit sequential shipment declines and slightly lower price/mix. Cash generation is also lagging earnings. Operating cash flow was only $6.8 million because inventory rose $19.1 million, and free cash flow was negative $6.3 million for the quarter and negative $43.1 million year to date. Cash has fallen to $98.6 million from $156.7 million at year-end, although total liquidity remains ample at $388.7 million. Additional risks include:
- CEO Mike Williams retiring at year-end, with Kristopher Westbrooks succeeding him;
- some automotive programs rolling off in 2027;
- inflationary costs and lagged price realization on annual contracts;
- possible capital needs if DLA follow-on orders materialize, though those orders are not guaranteed.
Investor sentiment improved meaningfully into the report, rising from 0.23 to 0.52 on the -1 to +1 scale. Expectations have therefore moved from mildly positive to clearly constructive. The stock has climbed only 3.5% since the open after the August report, to $21.32, but it trades about 11% above its 200-day moving average of $19.16. The Earnings Whispers price, momentum and AVWAP trend readings are positive, while the sequential-growth reading is neutral. That neutral reading fits a quarter in which revenue and tonnage stalled even as profitability improved.
The bottom line is that Metallus is becoming a mix-driven, defense-levered story rather than a volume story. The third quarter showed that this transition can expand margins even when tons decline. The DLA award and the extended lead times give 2027 credible visibility. Investors now expect more, however, and they will have to look past a seasonally weak fourth quarter, thin cash conversion and a leadership handoff for that thesis to hold.
Read our earnings preview for Metallus Inc.: https://www.earningswhispers.com/article/MTUS/21412
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-13 | |
| Sep-30 | |
| Sep-29 | |
| Aug-31 | |
| Aug-31 | |
| Aug-26 | |
| Aug-26 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
