Match Group's Rally Puts Tinder's Promised Usage Turn On Trial This Quarter
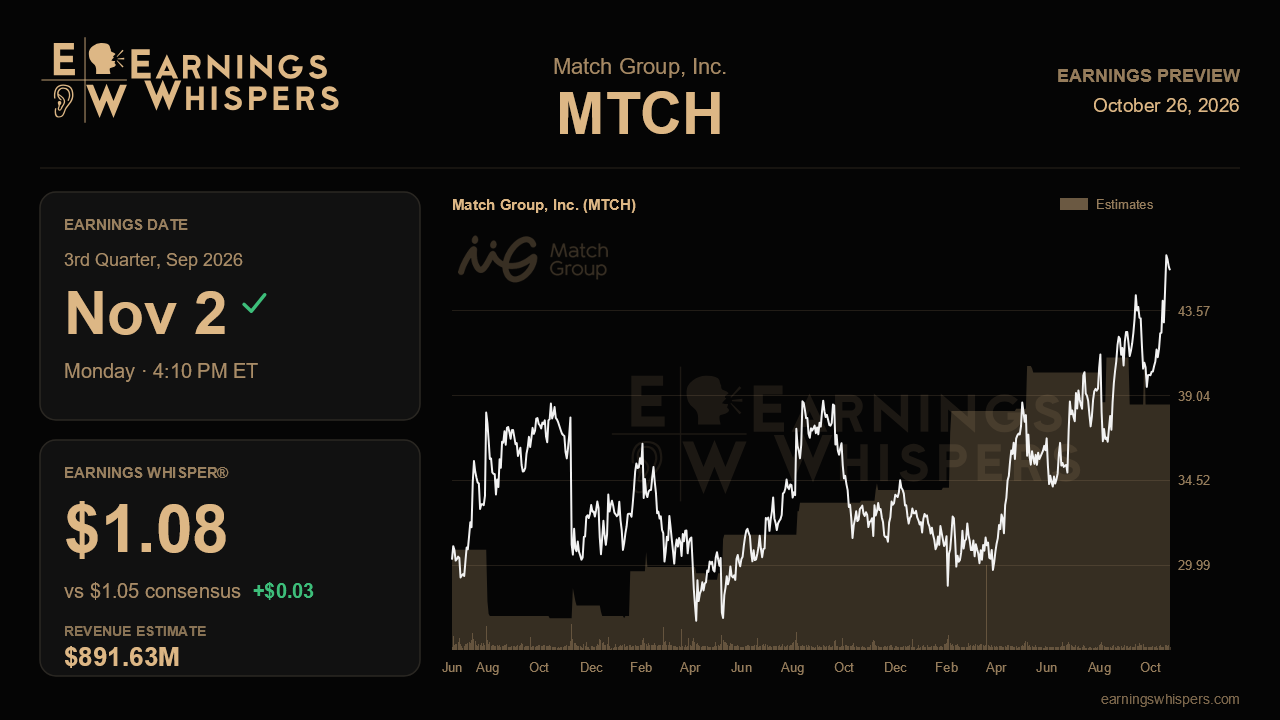
Match Group heads into its third-quarter report with a stock that has already priced in much of the recovery story. Shares have climbed about 21% since the last report while the S&P 500 slipped 2%. That leaves the company needing to show that Tinder's improving usage, which management described last quarter as on the verge of turning positive for the first time in more than three years, has actually crossed that line.
The financial bar is fairly well defined. Analysts expect non-GAAP earnings of $1.05 a share on revenue of $891.6 million, a 2.5% decline from the $914.3 million reported a year earlier. Management guided to $885 million to $895 million, so the Street sits slightly above the midpoint and comfortably inside the range. Consensus had earlier been closer to $895 million, near the top of the range, before drifting lower. The trim suggests analysts have absorbed the softer outlook rather than betting on upside. The Earnings Whisper of $1.08 is a few cents above consensus. That points to modest expectations for an earnings beat, which fits a business whose margins have been widening even as revenue shrinks.
The heart of the report is Tinder. Last quarter, management raised its full-year Tinder revenue outlook to a low-single-digit decline. It also cut the expected drag from user-experience testing to $30 million to $40 million and said the global rebrand had landed without hurting revenue. Daily active users went from falling about 6% earlier in the year to 4% in the second quarter and roughly 2.5% in July. Management said August was close to flat. Confirming the turn would mean year-over-year daily usage growth for the quarter, monthly actives improving from the 7% decline, and further gains in revenue per user and payer penetration. Proof that the mid-July recommendation algorithm update kept lifting Sparks would also help, since those were still down 4%. Investors should also look for early read-throughs from Events, which was slated to reach 26 cities by September. The weak link is conversion. Company-wide payers fell 6% last quarter, and the new CEO has set Tinder payer growth as a target for late 2027. Usage that improves without any narrowing in payer declines would raise questions about how long that lag lasts.
Hinge is the other half of the growth case. Direct revenue rose 22%, down from 28% in the first quarter, even as European expansion markets grew 86%. A further step down would not break the story. Still, it would matter more if the lower-priced tier being tested this quarter appears to be pulling down average revenue per payer rather than widening the funnel. Management continues to target $1 billion in Hinge revenue in 2027.
The known drag sits in Evergreen and Emerging. The Azar app redesign is costing roughly $15 million a quarter, and management cut its full-year segment outlook to a mid-teens decline. Advertising revenue fell 28% last quarter. Neither should surprise anyone, but any widening of the Azar hit would chip away at the revenue guide. Profitability gives the company a cushion. Adjusted EBITDA rose 14% to a 39% margin last quarter, supported by alternative-payment savings now expected at about $130 million for the year. Free cash flow is tracking toward the high end of guidance.
Sentiment has swung from mildly bearish before the last report to moderately bullish now. At $45.73, the stock trades about 2% below its post-earnings high of $46.67 and well above its 200-day average near $36. It is testing a breakout, a position that tends to reward confirmation and punish ambiguity. The central question is whether Tinder's engagement gains are real and spreading toward paying users. If daily usage has turned positive and payer trends are narrowing, the turnaround thesis holds. If usage stalls near flat, the recent rally will look early.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-08 | |
| Sep-23 | |
| Sep-22 | |
| Sep-18 |
