Match Group Misses Badly On EPS, But Tinder's Turnaround Reaches Users As A New 2027 Fee Headwind Emerges
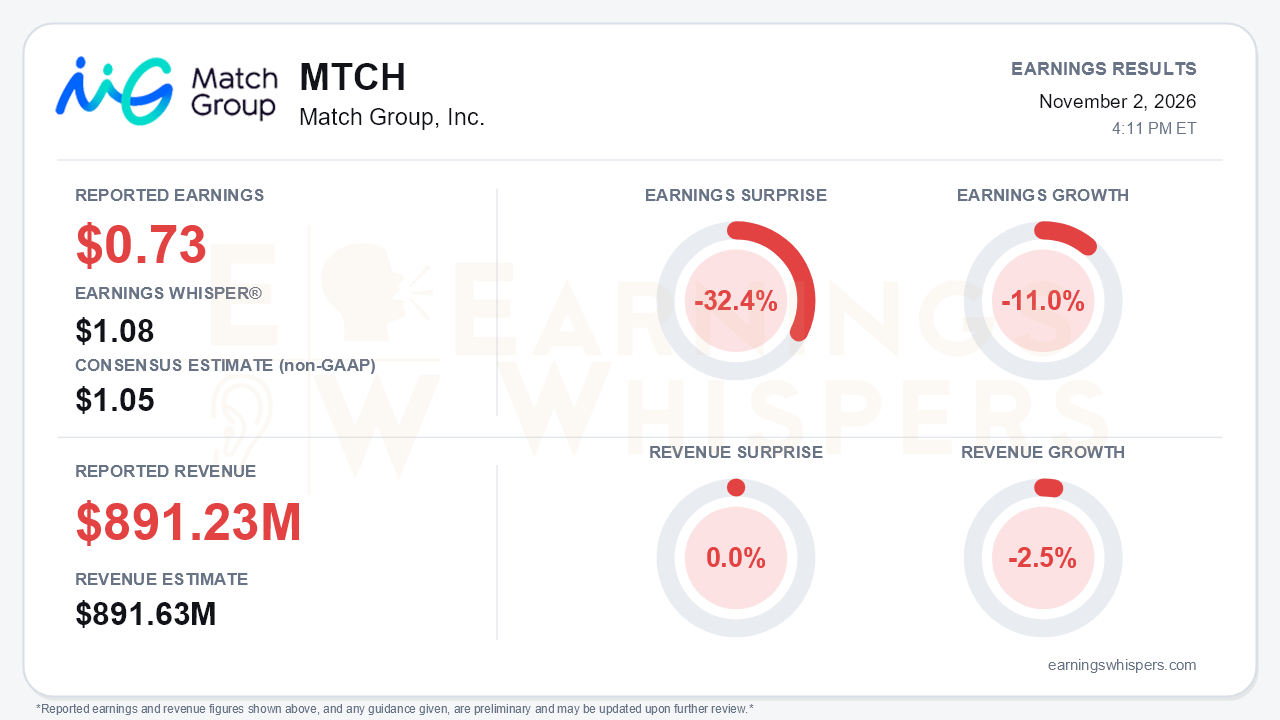
Match Group's third-quarter headline was poor. The company reported earnings of $0.73 per share, well short of the $1.05 consensus and the $1.08 Earnings Whisper number, a 32.4% shortfall. Earnings fell 11.0% year over year. Revenue of $891.23 million matched the $891.63 million consensus but declined 2.5% from a year ago. Yet the story management told, and much of the operating evidence, points the other way. Tinder's daily active users returned to year-over-year growth in September for the first time in three and a half years. Full-year 2026 targets edged higher. That is the central tension: a large earnings miss against a user turnaround that is broadening.
The quality of the miss deserves scrutiny, because the inputs do not line up neatly. Consensus was set on a non-GAAP basis, and the release excerpt does not break down what drove reported EPS. CFO Steve Bailey nonetheless said the company "delivered against our financial expectations." Management also raised its full-year outlook:
- revenue is now expected slightly above the midpoint of guidance, versus near the midpoint in Q2;
- adjusted EBITDA margin should meaningfully exceed the February target;
- free cash flow should exceed the high end of the range.
That combination suggests the EPS gap may owe more to items below the operating line, or to the basis of comparison, than to a collapse in the business. Investors should resolve that question before treating the miss as fundamental. Capital returns remain steady. Year-to-date free cash flow reached $832 million, $591 million has been returned, diluted shares are down 4% year over year and 10% since early 2025, and the $0.20 dividend was maintained.
The call showed Tinder's recovery moving beyond engagement into the metrics that eventually drive revenue:
- Monthly active users improved to -6%, from -7% in Q2, -8% in Q1 and -9% in Q4 2025.
- Payers improved to -4% from -5%.
- U.S. DAU turned positive exiting October.
- Markets representing about 70% of DAU and half of revenue are now flat or growing.
- User-experience "givebacks" shrank to about $25 million, from $30-40 million guided in Q2 and $60 million in February.
Revenue has not caught up, however. Tinder's FX-neutral direct revenue was stuck at -2% for a second straight quarter. Management expanded its 2027 targets to include full-year Tinder direct revenue growth, payer growth by Q4 2027 and flat MAU by year-end. That commitment raises the stakes, and new products give it some credibility: Groups, Events, Double Date, real-time recommendations and a Missed Connections test.
Hinge remains the growth engine, but it is decelerating. Revenue grew about 19%, down from 22% in Q2 and 28% in Q1, and management expects roughly 19-19.5% in Q4. Revenue per payer is now declining year over year, compared with +4% in Q2, as a lower-priced tier and price optimization pull in more payers. European expansion growth is slowing. The $1 billion 2027 target was reaffirmed, and a Japan entry is planned. The Evergreen & Emerging portfolio is expected to improve only modestly in 2027 from still-negative revenue.
Bears have legitimate ammunition on margins. Match's Google partnership expires in Q1 2027, and Play Store fees rise meaningfully from Q2. Apple raised EU in-app purchase fees to 26%, adding about $20 million in 2027 costs. Together, these create roughly a 1-point adjusted EBITDA margin headwind next year. That is a notable reversal from the Q2 call, when the Google change was framed as a small benefit. AI token costs doubled to more than $10 million and will rise again. The Epic v. Apple outcome could also alter the favorable U.S. alternative-payment economics. Just as Tinder is set to restart monetization from a "blank slate," the cost of collecting revenue is rising.
Investors had already leaned into the turnaround. Earnings Whispers sentiment swung from -0.14 after the prior report to +0.27, a substantial move from mildly negative to clearly positive. Shares rose 9.2% from the post-August open to $41.41 and sit 13.4% above the 200-day moving average. They had, however, already pulled back 11.3% from a 52-week high of $46.67 set on October 21. The trend readings are split: price and momentum are positive, while sequential growth and AVWAP remain negative. That split mirrors the gap between improving user trends and still-shrinking revenue.
The bottom line is that Match delivered the operating milestone turnaround believers wanted, Tinder user growth, alongside an EPS miss and in-line, declining revenue that leave the financial proof unfinished. Raised 2026 targets and strong cash returns support the thesis. A new app-store margin headwind and a slowing Hinge make 2027 more demanding. With sentiment now positive and shares well above trend, the burden has shifted to converting Tinder's engagement gains into revenue growth.
Read our earnings preview for Match Group, Inc.: https://www.earningswhispers.com/article/MTCH/21411
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 |
