Paymentus Must Prove Its Cautious 15% Growth Guide Is Sandbagging, Not A Slowdown
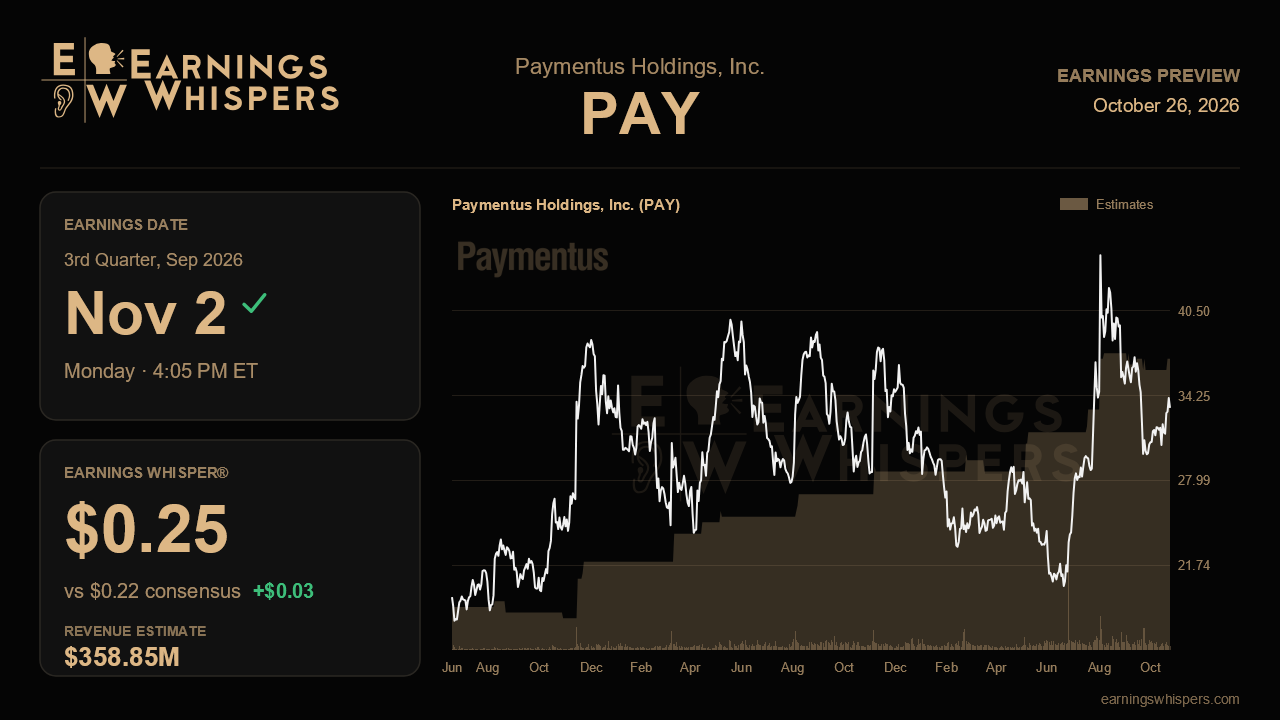
Paymentus heads into its third-quarter report with an unusual problem: the business looks better than its own forecast. Last quarter the bill-payment specialist posted record revenue of $360.7 million, up nearly 29% from a year earlier. It raised full-year guidance for a third straight time and pushed adjusted EBITDA margins to a new high. Yet its third-quarter revenue outlook implies growth of only about 15%. The stock has fallen 17.6% since that report while the S&P 500 was essentially flat. The question for November 2 is whether that step-down in guidance reflected a deliberately low bar or the first sign of real deceleration.
The Street has largely taken management at its word. Consensus calls for revenue of $358.9 million, up 15.5% from $310.7 million a year ago. That sits just above the midpoint of the company's $353 million to $363 million range, so analysts are not demanding a blowout. The consensus EPS estimate is $0.22, versus $0.15 in the year-ago quarter and $0.21 last quarter. The Earnings Whisper of $0.25 is modestly higher, which suggests the more engaged crowd expects profitability to outrun the official numbers again. Because the revenue guide looks conservative, the margin line may be where an upside surprise shows up first.
The prior call gives a clear template for judging this report. Management argued that its guidance philosophy is disciplined and that no single quarter's outlook should be overinterpreted. It backed that up by describing bookings and backlog as exceptionally strong, particularly in large enterprise, with visibility stretching into 2027. Contribution profit dollar growth had accelerated for four straight quarters, broadly across verticals and customer sizes. The narrative would be validated by revenue landing toward or above the top of the range and by a fifth quarter of contribution profit acceleration. It would also help if management nudged the full-year range of $1.443 billion to $1.458 billion higher once more. A print near the low end, or a reiterated annual outlook paired with soft commentary on implementations, would undercut the idea that the guide was merely cautious.
Profitability is the second test. Adjusted EBITDA as a share of contribution profit climbed from 36.5% to 41.3% over four quarters. Incremental margins of roughly 70% are offsetting a slow drift lower in contribution margin as big enterprise clients win volume discounts. Revenue per transaction also slipped sequentially on payment mix. If enterprise wins keep diluting unit economics while sales and marketing spending rises to convert the pipeline, that operating leverage could flatten. Another step up in EBITDA margin would show that the large-customer strategy is scaling profitably. Transaction trends also merit attention: second-quarter volume rose about 5% sequentially versus a historical norm near 2%, and management admitted it was unsure that pattern would persist.
The newer catalysts are earlier-stage but still worth tracking. Billio, the AI-driven service commerce suite, moved from launch to live deployments last quarter with favorable early client feedback. Bill Wallet had reached 100,000 users without marketing spend, and interchange monetization was flagged as an incremental opportunity. Concrete client adoption or revenue contribution would turn these from talking points into growth drivers.
Sentiment has cooled noticeably, with readings moving from mildly bearish to more firmly bearish since the last report. At $33.35, the stock sits much closer to its post-earnings low of $29.28 than its high of $45.31, though it remains above its 200-day moving average. That combination of strong reported fundamentals and a sharply deflated share price lowers the bar somewhat. Ultimately, the report hinges on one issue: whether third-quarter growth lands well above the guided 15% pace. If it does, the conservative-guidance story holds and the selloff looks overdone. If it does not, the market will conclude that the deceleration was real.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-19 | |
| Sep-29 | |
| Sep-08 | |
| Aug-17 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 | |
| Jul-20 | |
| May-05 | |
| May-04 | |
| May-04 | |
| May-04 |
