Paymentus Matches The Whisper And Raises Again, But A Sharp Growth Slowdown Sets The Real Test
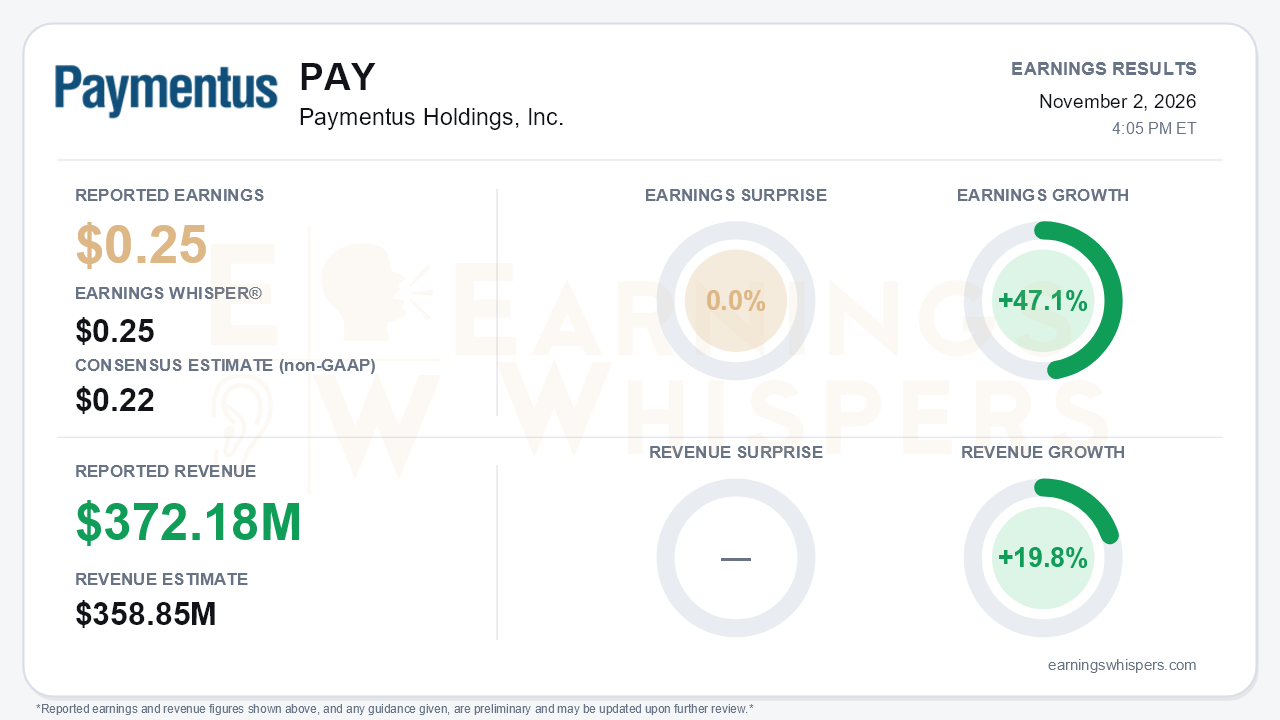
Paymentus (NYSE: PAY) earned $0.25 per share on a non-GAAP basis in the third quarter. That beat the $0.22 consensus but exactly matched the $0.25 Earnings Whisper number, so the quarter landed in line with what investors were actually looking for. Revenue of $372.2 million beat consensus by 3.7% and rose 19.8% year over year, while earnings grew 47.1%. The company raised full-year guidance for the third consecutive quarter. Yet the quarter's defining feature is not the beat. It is that top-line growth is decelerating quickly from the high-20s pace that defined the first half of 2026, while profitability keeps expanding. That is the central tension.
The quality of the earnings is hard to fault. GAAP diluted EPS rose to $0.21 from $0.14, and operating income jumped 69% to $33.5 million. Gross profit grew 25.4%, faster than revenue, and general and administrative expense actually declined year over year. Adjusted EBITDA climbed 38.6% to $49.7 million. That produced a record 41.9% margin on contribution profit, extending a steady climb from 37.3% in Q4 FY25 to 38.7% and then 41.3%, with incremental EBITDA margins near 68%. Free cash flow improved to $34.0 million from $25.7 million, and cash reached $407.6 million. This is operating leverage, not accounting help.
The headline growth rate, however, masks a weaker trajectory. Revenue growth slowed to 19.8% from 28.8% in Q2 and 30.2% in Q1. Contribution profit growth eased to 20.6% from 26.3%, and EBITDA growth dropped to 38.6% from 54%. The more telling detail is revenue per transaction, which was flat year over year at $1.70 after double-digit gains earlier in the year. Contribution profit per transaction was likewise flat at $0.54. The enterprise price-mix tailwind that inflated growth is now lapping, leaving transaction volume growth of 20.1% to carry the top line.
Guidance sharpens that picture rather than resolving it. Full-year revenue guidance rose to $1.464-$1.469 billion, adjusted EBITDA guidance to $186-$191 million, and the implied full-year EBITDA margin to 40.4%. The fourth-quarter outlook, though, implies only about 13.6% revenue growth and roughly 13.2% contribution profit growth. It also calls for adjusted EBITDA of $45-$50 million, a sequential step down that management tied to go-to-market spending. Earnings Whispers characterizes the guide as in line. The full-year raise largely reflects the third-quarter beat, while the forward quarter adds only a couple of million dollars to the prior implied range.
The call preserved a credible longer-term growth story. Paymentus booked its first sizable interchange-monetization agreement through its Instant Payment Network, an early step toward turning a major cost line into revenue. Bill Wallet users doubled to more than 200,000 without marketing spend. Bookings, backlog and pipeline were described as very strong. The CEO also framed an aspiration of roughly $2 billion in combined revenue and backlog within 18-24 months, which is explicitly not guidance. Bears still have legitimate ammunition. Management said interchange and Bill Wallet monetization are still a couple of years out and left room for added investment that could temper incremental margins. It also flagged agentic AI as both an opportunity and a disintermediation risk. Finally, management declined to offer a preliminary 2027 view, unlike a year ago, even though the release itself cited confidence in the 2027 outlook. That gap is likely to draw scrutiny.
The market had been bracing for the slowdown. Shares hit a 52-week high of $45.31 the day after the August report, then slid to a $29.28 low in late September. They entered this report at $32.82, down 18.9% from the post-Q2 open and 27.6% below that peak, though still about 14% above the 200-day moving average. Investor sentiment, already negative, deteriorated further from -0.18 to -0.30. The Earnings Whispers trend readings are mixed, with sequential growth and momentum positive while AVWAP remains negative, consistent with a stock that has given back its summer gains.
The bottom line is that Paymentus delivered a high-quality quarter: record margins, rising cash flow and a third consecutive guidance raise. However, it matched rather than beat the whisper and confirmed that growth is downshifting toward the low teens. With per-transaction economics flat and 2027 left unaddressed, the stock's path likely depends on whether bookings, backlog and new monetization levers can reaccelerate revenue before margin expansion runs out of room.
Read our earnings preview for Paymentus Holdings, Inc.: https://www.earningswhispers.com/article/PAY/21421
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-19 | |
| Sep-29 | |
| Sep-08 | |
| Aug-17 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 | |
| Jul-20 |
