Transocean's Margin Rebound And Valaris Progress Face Test As Stock Nears Breakout
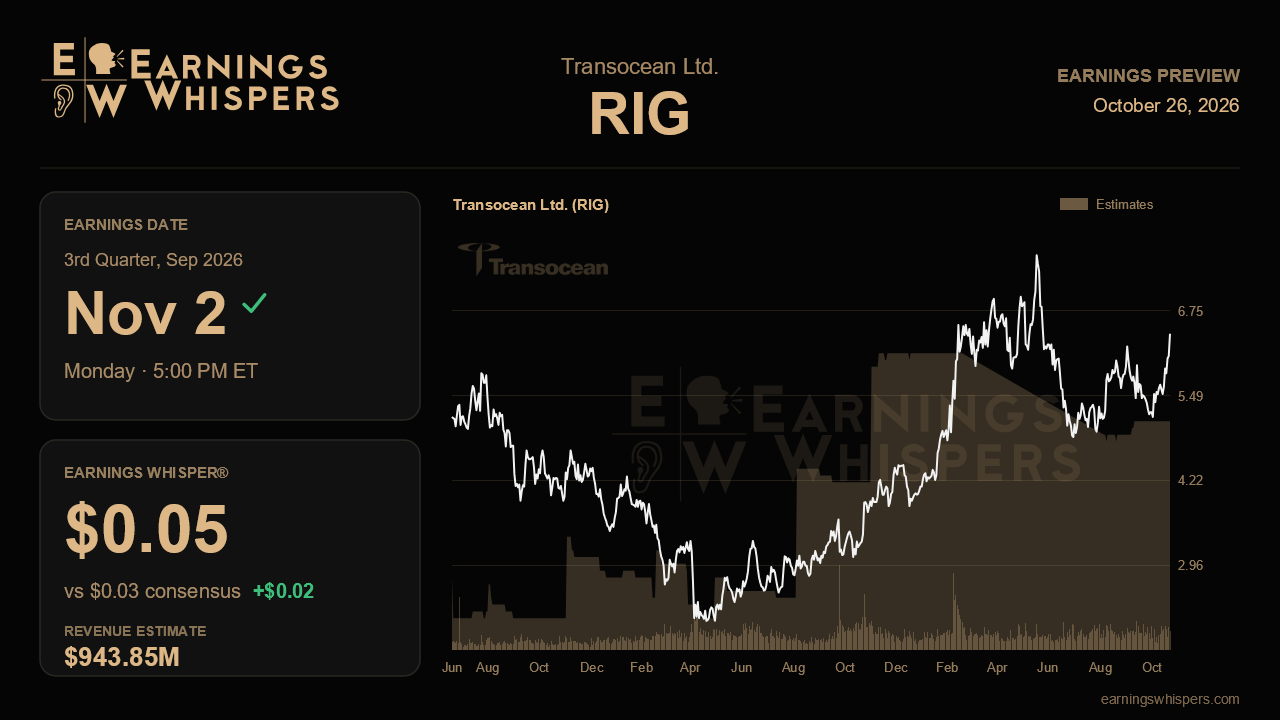
Transocean heads into its third-quarter report with a story that sounds better than its recent income statement looks. Last quarter management raised full-year revenue guidance, described a deepwater market finally converting forecasts into signed contracts, and moved its Valaris acquisition close to the finish line. Yet adjusted EBITDA margin slid to roughly 32% from above 40% the quarter before. The upcoming report, due after the close on November 2, needs to show that the step-down was the temporary distortion management said it was, not the start of a less profitable phase.
The headline numbers set a modest bar. Analysts expect earnings of $0.03 per share, matching the prior quarter but half the $0.06 earned a year ago, on revenue of about $943.9 million, down 8.2% from the year-ago $1.03 billion. That is contraction, not growth, and it reflects the rig roll-offs that shaped 2026 before the recent wave of extensions. Management guided to revenue of $920 million to $960 million, and the Street has climbed from roughly $860 million when that range was issued to a figure in the upper half of it. Consensus is no longer leaning on the company's outlook so much as taking it at its word. The whisper number of $0.05 sits a couple of cents above consensus, a small gap in dollars but a meaningful one at this tiny earnings base, suggesting traders expect cost control to show through.
Margins are the crux. Second-quarter G&A ran at about $56 million against a guided run-rate near $45 million, with roughly $11 million tied to Valaris deal costs, and management also nudged full-year cost guidance higher to support added activity. If EBITDA margin recovers toward the mid-to-high 30s with transaction expenses contained, the optical-dip explanation holds. If margin stays near 32% without a similar one-time excuse, investors will have to weigh fuel costs still running 20% to 40% above pre-war levels, lingering logistics inflation and cost savings that depend partly on deferred spending. Free cash flow matters too; the rebound to $212 million last quarter followed a working-capital-depressed first quarter, and a repeat would show that strength was not just timing.
The demand narrative faces a different test. Management lifted its outlook for deepwater utilization to approaching 100% by the end of 2027, a steady upgrade from earlier calls, and pointed to roughly $3 billion of rig time booked this year, dozens of open tenders, Africa as the largest growth region and a surge in Southeast Asian and Indian contracting. Fresh fixtures, day-rate commentary and backlog additions would confirm the inflection. Signs that the two to four deepwater rigs leaving the U.S. Gulf are struggling to find work elsewhere would complicate it. On the balance sheet, net debt to EBITDA fell to 2.8x and both rating agencies upgraded the credit; further deleveraging and an update on the remaining Brazilian and U.S. approvals for Valaris would keep the fourth-quarter close on track.
The market has already bought much of this. Shares are up nearly 18% since the last report while the S&P 500 slipped, a gap of about 19 points, and sentiment, while still negative, has turned noticeably less bearish than heading into the prior quarter. At $6.41 the stock sits comfortably above its 200-day average of $5.79 and within about 2% of its post-earnings high of $6.52, effectively testing a breakout from a tighter range than last quarter's volatile swing.
That positioning raises the stakes. Revenue landing inside guidance is likely table stakes. What will determine whether the improving narrative stays intact is evidence that profitability is recovering alongside utilization, proving that a fuller fleet translates into wider margins rather than simply busier rigs.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-19 | |
| Oct-15 | |
| Oct-12 | |
| Oct-11 | |
| Oct-09 | |
| Sep-15 | |
| Sep-15 | |
| Aug-21 | |
| Aug-21 | |
| Aug-20 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-14 |
