Transocean Posts Breakeven Miss As Backlog Surge And Valaris Clearance Shift Focus To 2027
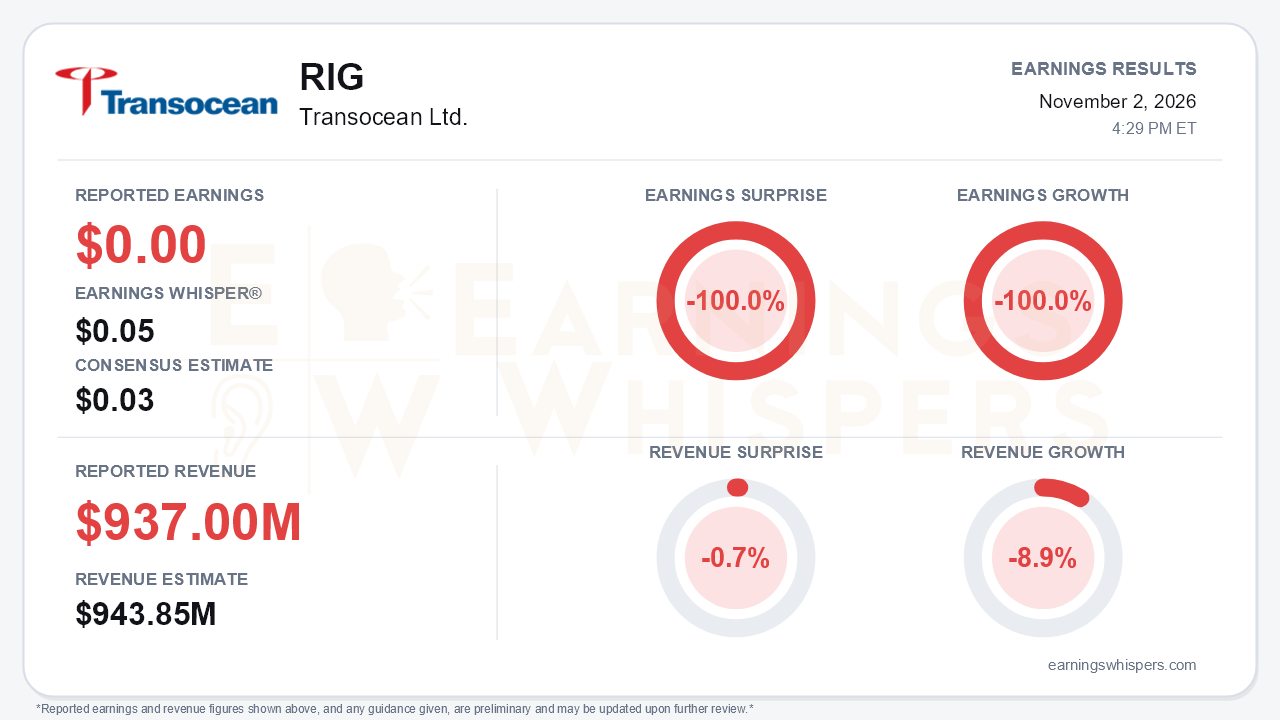
Transocean (NYSE: RIG) delivered a quarter with two competing stories. On the income statement, the offshore driller reported breakeven adjusted results of $0.00 per share. That fell short of the $0.03 consensus and the $0.05 Earnings Whisper number, a 100.0% miss and a 100.0% year-over-year decline from $0.06. Revenue of $937.0 million missed the $943.85 million consensus by 0.7% and fell 8.9% from a year ago. That is a steeper contraction than the second quarter, when revenue of $966 million was only modestly below the prior-year $988 million. The commercial story moved the other way. Transocean added roughly $2.0 billion of backlog, lifted 2027 contract coverage to about 95%, and cleared every regulatory hurdle for the Valaris combination. That is the central tension: near-term earnings are stalling while forward visibility has improved sharply.
The quality of the reported numbers deserves scrutiny. GAAP net income was $26 million, or $0.02 per diluted share, compared with a $1.92 billion loss a year earlier that was driven by $1.9 billion of impairments. The GAAP profit leaned on $93 million of discrete tax benefits, partly offset by a $101 million pretax benefit-plan termination charge. Stripping those out, adjusted pretax income was just $34 million, versus $196 million in the second quarter. Adjusted EBITDA of $313 million was flat sequentially, and the 33.4% margin edged up from 32.2%. Both remain well below the 38.7% margin a year ago and the 40.7% margin in the first quarter. The revenue softness came mainly from ultra-deepwater floaters. Their utilization dropped to 67.6% from 72.6%, and average daily revenue slipped to $442,100 from $455,500. Harsh-environment rigs were the bright spot, running at 95.1% utilization with dayrates of $504,300, up from $467,100 a year ago. Free cash flow fell to $131 million from $212 million, which the call attributed to collection timing and insurance payments.
The conference call was more confident than the financials. Management called this the best contracting year in a decade. Year-to-date awards now exceed $4 billion, and standalone backlog has climbed to about $8.0 billion, from roughly $6 billion at year-end 2025. Third-quarter additions included the $1 billion Equinor Cat-D approval and new fixtures for Proteus, Conqueror and an ONGC program. Those awards came at a weighted average dayrate near $423,000. Average contract duration has stretched to roughly 380 days from about 245 last year. The active fleet is sold out for 2026, and 2028 coverage already sits near 65%. Management's tone on a pricing inflection firmed as visibility into 2028-2031 tightened.
The Valaris deal is the dominant catalyst. The DOJ and Brazil's CADE approved it without conditions, shareholders vote November 24, and closing is targeted for December 1. Management is targeting $200 million in annual synergies, and pro forma backlog stands near $12.7 billion. The balance sheet also improved. The remaining $200 million of Deepwater Aquila notes was redeemed early, total debt principal is down $1.32 billion year over year to $4.98 billion, and the revolver will expand to $750 million with maturity extended to 2031 at closing. Bears still have legitimate ammunition, however. Guidance was essentially in line, but the details tilted toward cost:
- The 2026 revenue range was narrowed by $25 million as gap-filler upside faded.
- G&A guidance rose to $185-190 million.
- Full-year interest expense moved up to about $500 million.
- Preliminary 2027 operations and maintenance expense is guided about $60 million higher amid emerging logistics, fuel and materials inflation.
- Valaris integration costs are not yet quantified and are excluded from guidance.
- $763 million of 8.75% secured notes still need to be addressed in 2027.
- Net debt to EBITDA ticked up to 2.9x from 2.8x as trailing EBITDA declined.
Investor expectations had already been improving before the print. Earnings Whispers sentiment rose to -0.09 from -0.31 at the prior report. That is a meaningful shift toward neutral, though not yet a positive reading. Shares have gained 14.5% since opening at $5.44 after the August report and closed at $6.23, about 6.4% above the 200-day moving average of $5.86. The Earnings Whispers price, momentum and AVWAP trend signals are positive, consistent with a market that has been rewarding the contracting and merger progress more than the quarterly earnings.
That creates a more complicated setup than the miss alone implies. A stock that entered the report on firmer footing and better sentiment now has to reconcile flat EBITDA, weaker cash generation and rising cost guidance with a backlog story that keeps improving. The preliminary 2027 revenue range of $3.85-4.0 billion implies little growth before Valaris is included. That makes synergy capture and dayrate repricing the real drivers of any earnings recovery.
The bottom line is that Transocean's third quarter was a financial disappointment but a commercial success. Breakeven adjusted earnings, softer ultra-deepwater utilization and creeping cost inflation show that the earnings base has not yet turned. Meanwhile, a 95% contracted 2027, an $8 billion backlog and an unconditionally approved Valaris merger give the company a credible path forward. Investors are now being asked to look through the current quarter, and execution on integration and pricing will determine whether that patience is rewarded.
Read our earnings preview for Transocean Ltd.: https://www.earningswhispers.com/article/RIG/21427
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-19 | |
| Oct-15 | |
| Oct-12 | |
| Oct-11 | |
| Oct-09 | |
| Sep-15 | |
| Sep-15 | |
| Aug-21 | |
| Aug-21 | |
| Aug-20 |
