BBB Foods Must Prove Margin Gains Survive Distribution Center Buildout After 28% Rally
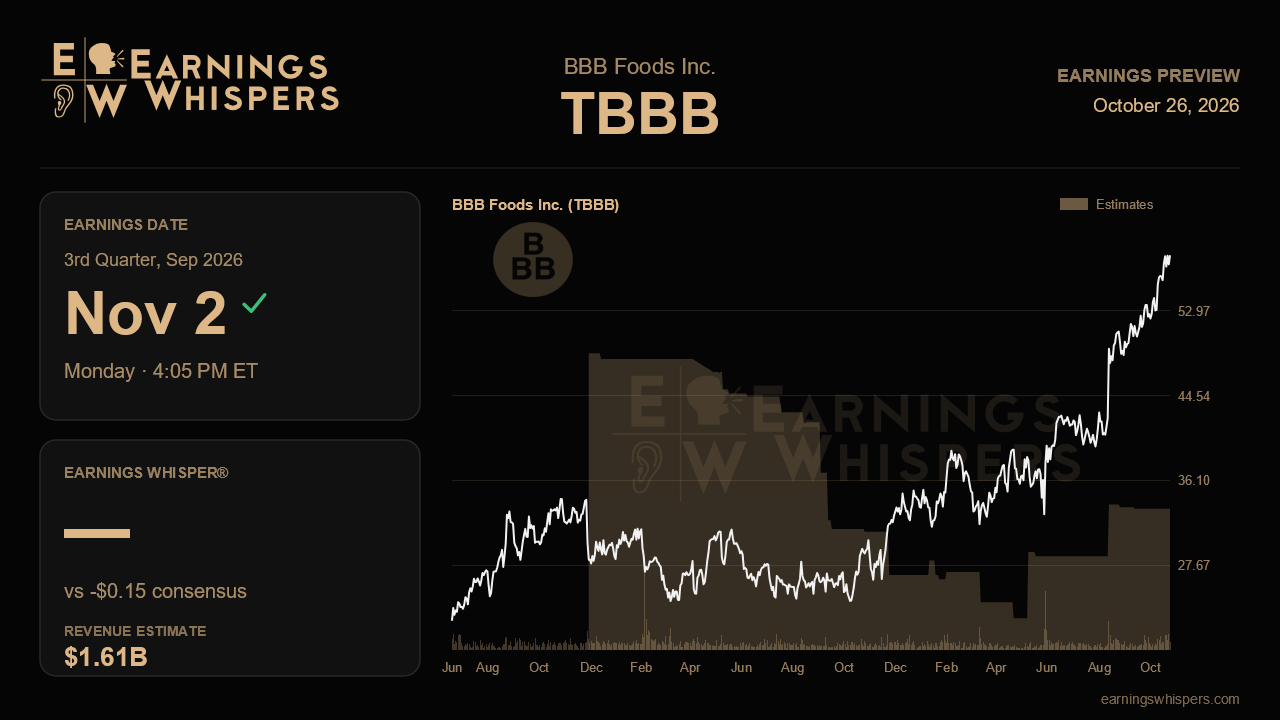
BBB Foods heads into its third-quarter report with the kind of problem most retailers would welcome: its last quarter was so strong that merely good may no longer be enough. Same-store sales at its Tiendas 3B chain accelerated to 20% in the second quarter, the fastest pace in a year. Gross margin, which had been quiet, finally started contributing to profit growth. The stock has since climbed nearly 28% while the S&P 500 slipped. The report after the close on November 2 will show whether that momentum carries through a quarter management itself flagged as noisier on costs.
Wall Street expects revenue of about $1.61 billion, up roughly 48% from a year ago. The company reports in pesos, and last quarter's local-currency growth was 39%, so currency translation likely accounts for part of the gap and is worth keeping in mind when judging the headline number. The consensus calls for a loss of $0.15 per share, a sharp improvement from the $0.66 loss a year earlier and modestly better than the $0.19 loss last quarter. The per-share loss is less useful as a scorecard than adjusted EBITDA, operating cash flow and the cost lines that drive them.
Management does not give quarterly guidance, but its 2026 framework sets up the real question. Set early in the year, it called for same-store sales growth of 13% to 16%, 590 to 630 net new stores, and revenue growth of 29% to 32%. The first half beat those targets comfortably, with comparable sales of 16% and then 20%, and revenue growth of 33% and then 39%. That leaves the annual outlook looking conservative. A third quarter with same-store sales in the high teens would make it hard for management to justify leaving the targets unchanged. A drop back toward the guided range would suggest the second quarter was a peak rather than a new baseline.
The quality of growth matters as much as the speed. Roughly two-thirds of the second-quarter sales gain came from volume, with price driven mostly by mix rather than inflation. That is the healthiest kind of growth for a hard discounter, because it points to share gains, and the gap over the ANTAD industry benchmark widened past 20 percentage points. Continued strength in new stores, all now built on a larger format with more refrigeration that management says ramps faster, would support the store-growth story. Store openings should keep pace with a year in which 155 net stores were added in the second quarter alone.
Margins are where the narrative faces its sternest test. Three new distribution centers opened around the third quarter, and management warned of temporary logistics pressure as they ramp. General and administrative costs are also rising as the company invests in talent, a trend expected to run into 2027. Last quarter, savings in selling expenses, which fell to 10.0% of revenue, more than offset those headwinds. If adjusted EBITDA margin still expands year over year despite the DC openings, the operating-leverage case gets much stronger. A modest, clearly explained dip tied to logistics would likely be forgiven, while a broader erosion would not.
Sentiment has edged up to about 51% bullish from roughly 48% before the last report, a mild shift that understates how much the stock has repriced. Shares trade near $58.50, far above the 200-day moving average and within 2% of the post-earnings high of $59.60, effectively testing a breakout. That positioning raises the stakes. The central issue is whether BBB Foods can keep comparable sales well above its own targets while absorbing the cost of new distribution centers. Do both, and a guidance raise becomes the natural next step. Stumble on either, and a stock priced for acceleration may have to settle for being merely excellent.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-19 | |
| Aug-14 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-04 | |
| Jul-31 | |
| Jul-17 | |
| May-06 | |
| May-06 | |
| May-06 |
