Tiendas 3B's Acceleration Extends To A Fourth Straight Quarter, But Reaffirmed Guidance And A Thin Profit Keep The Beat In Perspective
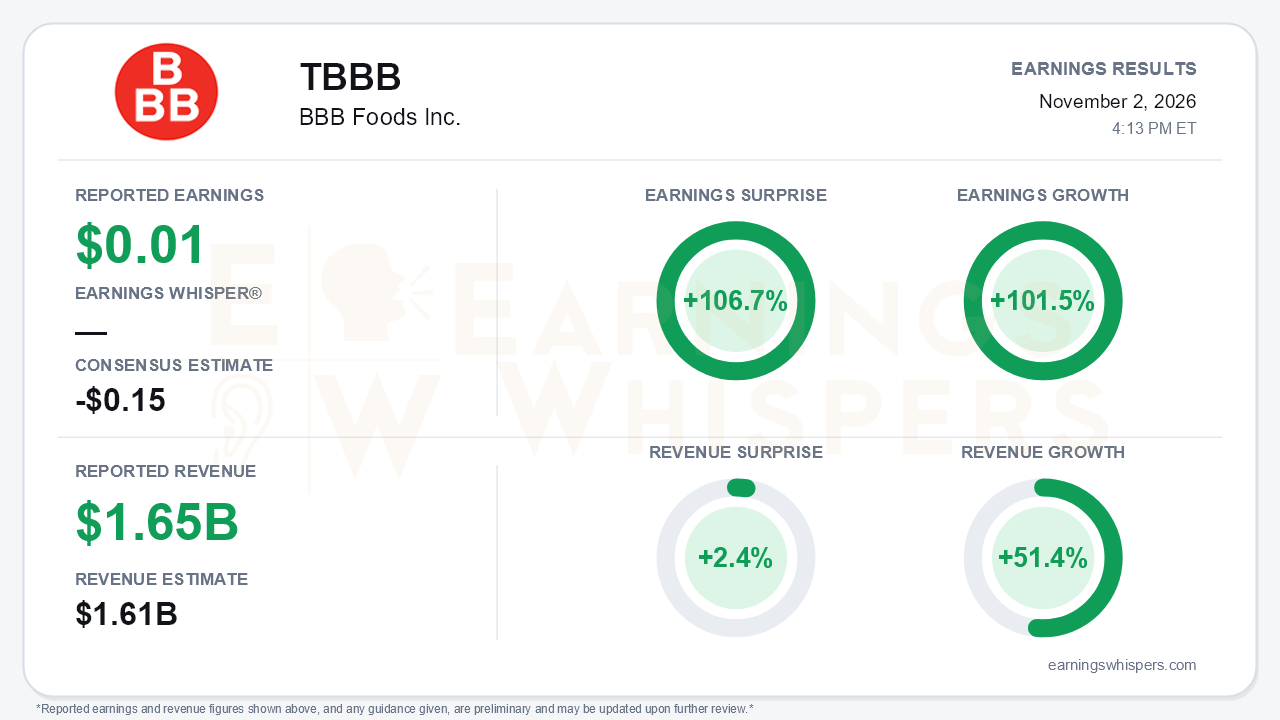
BBB Foods (NYSE: TBBB) delivered the cleanest operating quarter since its listing. It posted earnings of $0.01 per share against a consensus estimate of a $0.15 loss, a 106.7% surprise. Revenue of $1.649 billion topped the $1.61 billion consensus by 2.4%. On Earnings Whispers' normalized basis, earnings grew 101.5% year over year and revenue rose 51.4% in dollar terms. In pesos, revenue grew 40.3% to Ps. 28.4 billion. The central development is acceleration: same-store sales, revenue growth, and adjusted EBITDA growth all stepped up again. The central tension is that management simply reaffirmed full-year guidance it is running far ahead of, while pushing any 2027 framework to the next call.
The quality of the swing to profit deserves scrutiny. Net profit of Ps. 23 million, compared with a Ps. 1.42 billion loss a year ago, came mostly from mechanics rather than operations. Non-cash share-based payment expense fell to Ps. 550 million from Ps. 1.57 billion, because the Liquidity Event Plan is expensed on a front-loaded graded schedule. A Ps. 97 million foreign-exchange gain also helped, replacing an Ps. 86 million loss last year. Excluding that FX gain, pretax profit would not have covered the Ps. 290 million tax bill. Underneath, though, the operating story is genuine:
- Gross margin widened 52 basis points to 16.7%, despite four distribution-center openings.
- Selling expenses fell 36 basis points to 9.8% of revenue.
- Adjusted EBITDA excluding share-based pay jumped 60.5% to Ps. 1.88 billion, with an 83-basis-point margin expansion to 6.6%.
The stock-compensation drag is also scheduled to fade. Management projects about Ps. 489 million in the fourth quarter and Ps. 879 million for all of 2027, which gives reported earnings a mechanical tailwind from here.
The call showed how broad the improvement has become. Same-store sales have run 16%, 20%, and 20.5% across the three quarters, against a full-year guide of 13% to 16%. Revenue growth climbed from 33% to 39% to 40%, versus a 29% to 32% guide. Adjusted EBITDA margin expansion jumped to 83 basis points from roughly 21 to 22 basis points in each of the first two quarters. Administrative costs excluding stock pay flipped from 57 basis points of deleverage in the second quarter to 6 basis points of leverage. The gap versus the ANTAD industry benchmark widened to more than 21 percentage points.
Management pointed to several drivers behind the trend:
- Newer store vintages are opening at higher sales levels and ramping faster.
- Items per basket have risen to four or five, from two or three at the IPO.
- Frozen and cosmetics categories are outperforming.
- Transportation and logistics optimization remains a major 2027 opportunity where the company has "barely scratched the surface."
Cash generation reinforces the picture. Nine-month operating cash flow reached Ps. 7.05 billion, up 128%, as negative working capital deepened to Ps. 10.8 billion and fully funded expansion.
Bears still have legitimate ammunition. Net openings of 419 year to date (123, 155, and 141 by quarter) leave roughly 171 to 211 stores needed in the fourth quarter to hit the 590 to 630 target. That would exceed any quarter so far this year, though management reiterated the target and cited a healthy pipeline. Distribution-center openings are creating sequential logistics and gross-margin pressure. Lease interest pushed financial costs up 45.7%. A pending Mexican tax reform limiting deductions could temporarily weigh on cash flow, and that uncertainty is why 2027 guidance was deferred. Competitors are also moving in hard discount, although management said it has seen no notable change.
The market setup is more demanding than the surprise implies. Shares have risen 24.5% since the open after the August report, to $56.97, and sit about 36% above the 200-day moving average of $41.99. Earnings Whispers trend signals are uniformly positive, consistent with that run. Investor sentiment, however, stayed positive but cooled modestly, slipping from 0.48 to 0.41 heading into the report. Enthusiasm has eased slightly even as the stock has climbed, which suggests a good deal of the acceleration was already anticipated.
The bottom line is that Tiendas 3B's third quarter showed a business compounding faster, with genuine operating leverage and strong self-funded cash flow. The headline profit is thinner and more accounting-driven than the beat suggests. With guidance left untouched despite a wide cushion, a heavy fourth-quarter opening schedule, and tax-reform uncertainty clouding 2027, the next catalyst is the fourth-quarter call. That call will need to translate this momentum into a credible forward outlook for a stock already priced well above its long-term trend.
Read our earnings preview for BBB Foods Inc.: https://www.earningswhispers.com/article/TBBB/21434
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-19 | |
| Aug-14 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-04 | |
| Jul-31 | |
| Jul-17 | |
| May-06 | |
| May-06 | |
| May-06 |
