Tennant's Q3 Test: Can Margins Stabilize While Robotics And Orders Keep Climbing?
Tennant heads into its third-quarter report with a split personality that the market has decided to punish rather than parse. Demand looks healthy, backlog is swelling and the robotics business is growing fast, yet the profit engine has sputtered badly enough that management cut its full-year earnings outlook by roughly a dollar a share last quarter. The question for this report is whether that reset was a one-time clearing event or the start of a longer slide.
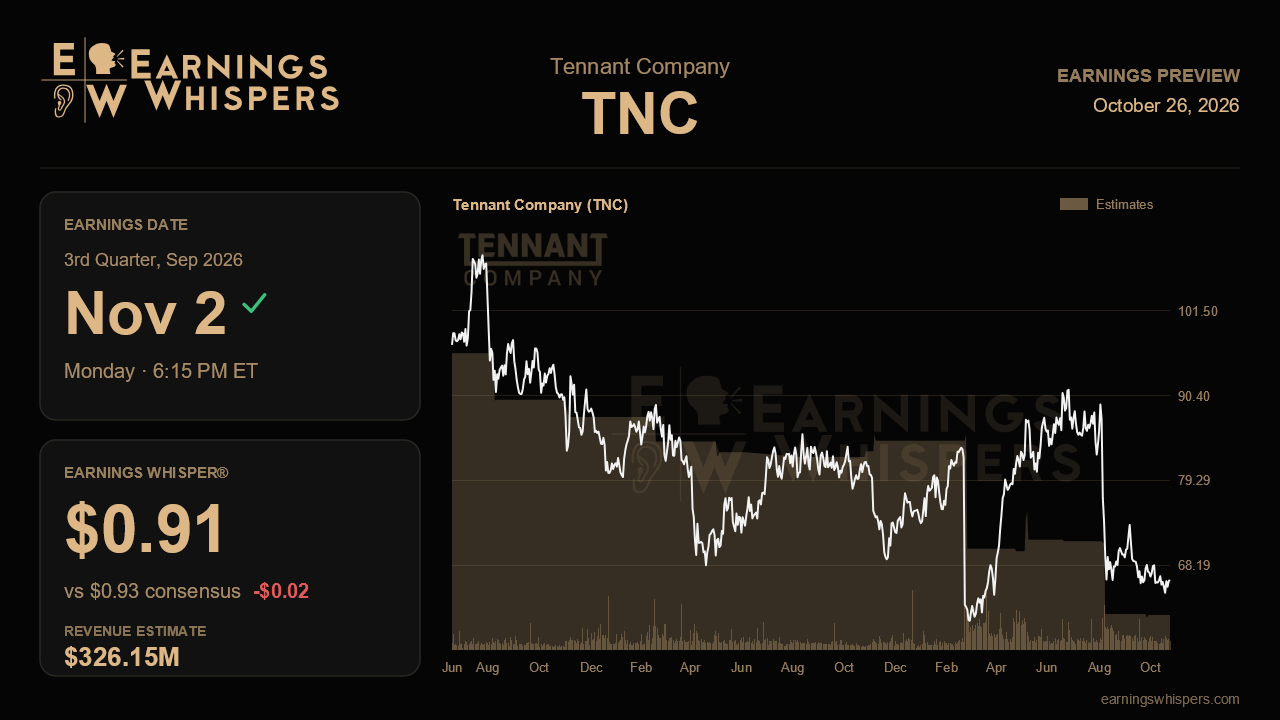
Wall Street expects earnings of $0.93 a share on revenue of $326.2 million. That implies sales growth of about 7.5% from a year ago but a 36% drop in earnings from $1.46, which captures the problem neatly: Tennant is selling more and keeping much less of it. The earnings whisper sits at $0.91, a hair below consensus, suggesting the more skeptical crowd sees a little more downside risk but not a dramatically lower bar. Sequentially, the estimate asks for only a modest step up from the $0.83 posted in the second quarter on nearly identical revenue, so the quarter is less about volume than about whether gross margin stops bleeding.
Management's revised full-year range calls for adjusted EPS of $3.80 to $4.45 and adjusted EBITDA of $155 million to $170 million, down from $4.70 to $5.30 and $175 million to $190 million. When that cut landed, the Street was still sitting at $5.12, well above even the old midpoint, so estimates have had to come down hard. On the top line, the raised sales guide of $1.27 billion to $1.31 billion compares with a consensus near the low end, leaving room for upside if supply cooperates. The width of the EPS range matters too: hitting the low end leaves little cushion, and anything that hints at a further trim would undercut the idea that the damage is contained.
The operational checklist flows directly from the last call. Gross margin fell to 39.5% in the second quarter, below the roughly 40% exit rate flagged earlier in the year and far from the 43% management considers normal. Management warned that North American parts shortages, partly caused by demand-signal errors in its new ERP system, would spill into the third quarter, and it pushed full recovery in that region out to the first half of 2027. Evidence that shortages are easing would show up as backlog, which stood at $127 million, beginning to convert into shipments rather than piling higher. Investors should also look for whether discounting and Middle East freight costs are still eroding net pricing in EMEA, and whether the 10.6% organic decline in APAC is stabilizing as distributor inventory clears. Leverage at 2.0x, the top of the target range, makes cash generation another important tell.
Robotics is the bright spot that needs to keep earning its keep. The business delivered $58 million in the first half, and the full-year target of $130 million to $145 million implies a second half of roughly $72 million to $87 million, meaningfully above the $31 million second-quarter run rate. Progress on the Savers 250-robot deployment and early shipments of the X2 and X16 machines should tell whether that ramp is on schedule.
The market is not giving Tennant the benefit of the doubt. Shares have fallen 17.2% since the last report while the S&P 500 slipped just 1.3%, and bearish sentiment has jumped to about 70% from 27% a quarter ago. At $66.26, the stock sits well below its 200-day average of $76.22 and within about 3% of its post-earnings low of $64.48, with the entire recent range trading below the prior quarter's floor. That pessimism lowers the bar somewhat, but the decisive issue remains margins: if gross margin holds near 40% or improves and management affirms its reduced outlook, the story shifts from deterioration to repair. Another leg lower in profitability would suggest the ERP problems run deeper than advertised.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-20 | |
| Oct-20 | |
| Oct-02 | |
| Sep-21 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-30 | |
| Jul-23 | |
| Jun-17 | |
| May-11 | |
| May-04 | |
| May-04 | |
| May-04 |
