Tennant Crushes EPS Estimates As Orders And Robotics Accelerate, But Tariff Refunds, EMEA Softness And A Steep Q4 Ramp Temper The Beat
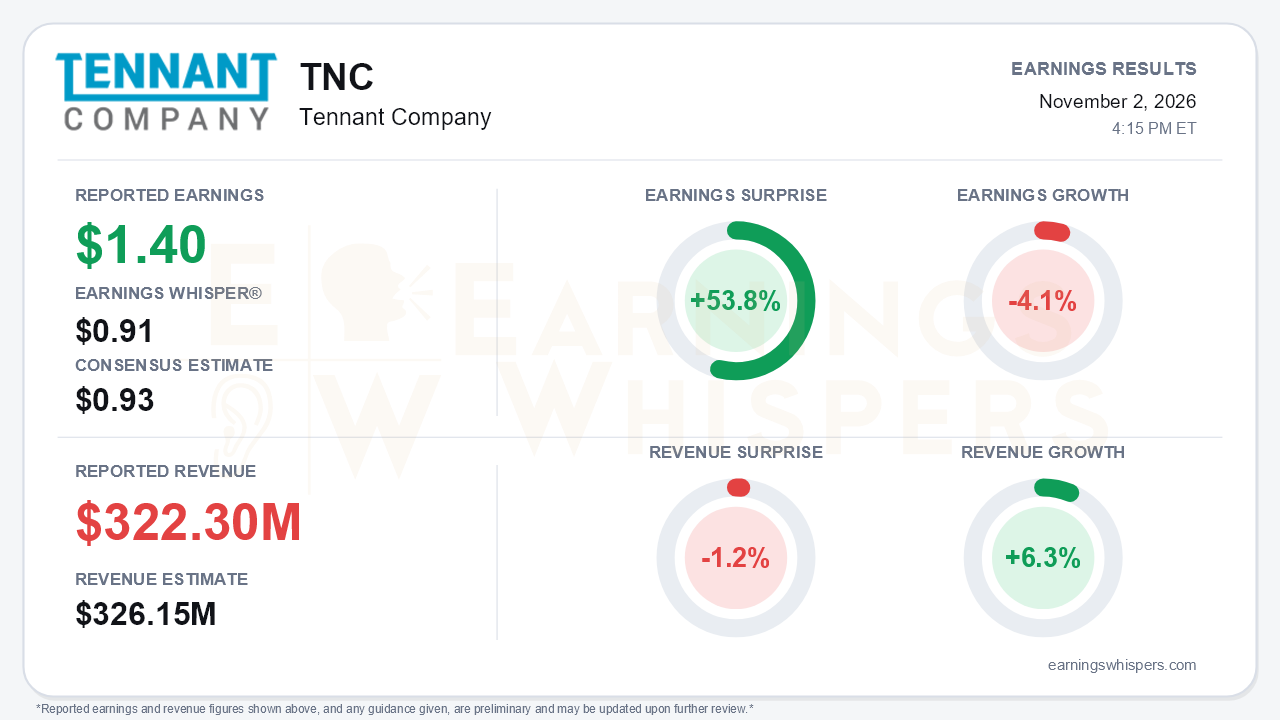
Tennant Company (NYSE: TNC) delivered a third-quarter result that looks far better against expectations than against last year. Adjusted earnings of $1.40 per share beat the $0.93 consensus by 53.8% and cleared the $0.91 Earnings Whisper number by a wide margin. Earnings still fell 4.1% from a year ago. Revenue of $322.3 million rose 6.3% year over year, a record for a third quarter, but it missed the $326.15 million consensus by 1.2%. The central tension is that operating momentum clearly improved from a weak first half, yet the size of the earnings beat overstates how much the underlying profit picture has changed.
The quality of the beat deserves scrutiny. Reported gross margin of 42.3% included roughly $6.1 million, or about 190 basis points, of one-time refunds of IEEPA-related tariffs. Excluding that benefit, gross margin was about 40.4%, down 230 basis points year over year. Management attributed the decline to Middle East-related freight and material inflation and to parts shortages that caused production inefficiencies and under-absorption. The call also noted that S&A benefited from a long-term incentive accrual adjustment, which flattered operating expenses. GAAP EPS jumped to $1.12 from $0.80, but much of that reflects lower ERP and legal charges than in the prior year rather than stronger core profitability. Higher interest expense and the declining adjusted EPS show that buybacks are doing some of the lifting.
The sequential trajectory is where the bull case lives, and it was genuinely strong. Organic growth reached 5.7%, up from declines of 0.5% in the second quarter and 1.9% in the first, led by 8.1% organic growth in the Americas. Orders rose 9.5%, accelerating from 6.6% in the second quarter, and North America orders climbed 18%. Robotics revenue of about $37 million grew 71%, nearly double the 37% pace of the prior quarter. Year-to-date robotics sales of $95.3 million already exceed all of 2025. The $130–145 million full-year robotics target and the $250 million 2028 goal remain intact.
On margins, normalized gross margin of 40.4% topped the roughly 39.5% management had guided on the prior call. Adjusted EBITDA margin excluding refunds improved to 13.2% from 10.9% in the second quarter. The ERP story also turned:
- ERP inefficiencies fell to about $2 million from roughly $10 million in the first half.
- Management expects no more than $2 million of drag in the fourth quarter.
- The EMEA rollout was cancelled, removing a source of cost and execution risk.
The forward catalysts are tangible. These include the new P-Series value robotics line, the P1 autonomous vacuum shipping in the fourth quarter, the X16 sweeper launch, and a 5% dividend increase to $0.325. Bears, however, have legitimate ammunition:
- EMEA orders fell 9% after softening in August.
- APAC organic sales declined 4.8%, and the China strategy is under reassessment.
- Parts and consumables fell 6.3%.
- Inflation is now expected to run higher than previously anticipated and not be fully offset.
- Parts constraints persist, including robotics sensing and compute components.
- Year-to-date operating cash flow is negative $14.3 million as receivables and inventory build, and net leverage has doubled to 2.0x from 1.0x at year-end.
Guidance was reaffirmed, not raised, at $1.27–1.31 billion in sales, $155–170 million in adjusted EBITDA and $3.80–4.45 in adjusted EPS. Those ranges sit well below the original $175–190 million EBITDA and $4.70–5.30 EPS targets. The guide also implies a demanding fourth quarter of roughly $346 million in sales at about a 14% margin. That ramp depends on converting a backlog that has already slipped to $118 million from $127 million.
The market setup is more complicated than the surprise implies. Investor sentiment deteriorated sharply into the report, falling from -0.27 to -0.69, which signals deep skepticism toward the recovery narrative. Shares have dropped 14.1% since opening at $80.02 after the August report, to $68.73. They sit about 9.4% below the 200-day moving average of $75.90. The Earnings Whispers trend signals remain mostly negative, with price, momentum and AVWAP all weak and sequential growth only neutral. Pessimism that entrenched leaves room for a beat of this size to register, but it also reflects real doubts about margins and cash.
The bottom line is that Tennant delivered the operational inflection turnaround skeptics were not positioned for, with accelerating orders, robotics, organic growth and normalized margins. Even so, the headline beat leaned on one-time tariff refunds and a favorable accrual. Reaffirmed guidance still requires a steep fourth-quarter ramp against weakening EMEA demand, persistent inflation and constrained parts supply. Converting that backlog and stabilizing cash flow will determine whether this quarter marks a durable recovery or a flattering pause.
Read our earnings preview for Tennant Company: https://www.earningswhispers.com/article/TNC/21436
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-01 | |
| Oct-26 | |
| Oct-20 | |
| Oct-20 | |
| Oct-02 | |
| Sep-21 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-30 | |
| Jul-23 |
