TETRA Technologies Faces A Margin Test After Stock Halves Its Post-Earnings Rally
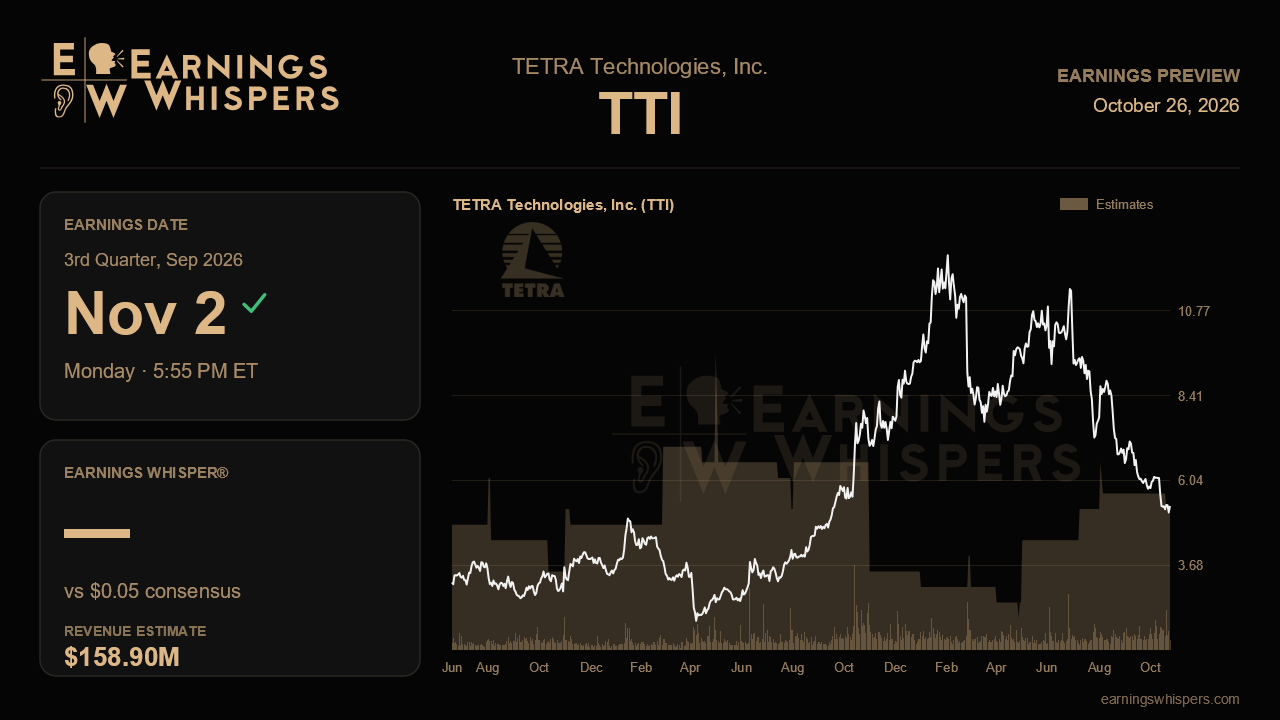
TETRA Technologies heads into its third-quarter report with an awkward split between what management described and what the market has priced. Three months ago the company posted a 19% sequential revenue jump, record international and offshore activity, a sharply cleaner balance sheet and a final investment decision on its Arkansas bromine plant. Since then the stock has fallen about 33%, while the S&P 500 was essentially flat. The report after the close on November 2 needs to show whether that selloff reflects a real crack in the story or a market that has given up too early on a company still carrying margin baggage.
The Street's bar is modest. Consensus calls for earnings of $0.05 a share on revenue of $158.9 million, up 25% and 3.7% from the year-ago $0.04 and $153.2 million. That is low single-digit top-line growth, not acceleration. More telling, the revenue estimate sits roughly 14% below the $185.7 million TETRA delivered last quarter, and the EPS figure is below the prior $0.08. Analysts appear to be modeling a quarter without a major Neptune deepwater fluids job, with some drag from delayed Middle East shipments. Per-share comparisons also absorb the $108 million equity raise, which cut net leverage to 0.4x but enlarged the share count. Management reaffirmed its base-business outlook as consistent with market expectations rather than raising it, and stressed that Neptune timing would swing second-half results. A beat on revenue alone may therefore say more about project timing than underlying strength.
The real scorecard is margins. Consolidated adjusted EBITDA margin slipped to 17.2% last quarter from 20.8% a year earlier, and completion fluids margin eased to 26.4% despite higher sales, squeezed by costly third-party bromine and mix. Management has framed bromine costs as a headwind that lasts until the Arkansas plant starts up in early 2028, so investors should not expect relief. What would validate the narrative is fluids margin holding inside the 25% to 30% band on lower revenue, along with continued gains in water and flowback, where margin climbed to 14.8% from 9.9% a year ago. A slide in fluids profitability below that band, or a stall in water and flowback, would suggest the margin problem goes beyond Neptune timing.
Several catalysts from last quarter also deserve updates. Argentina was tracking to double its 2026 revenue, a trajectory reaffirmed on three straight calls, and any slippage would undercut the international growth story. The new Neptune Z-Lite product and the three-well 20,000 PSI Gulf of America award should start showing up in activity commentary. On the Oasis desalination effort, the first direct engagement with a hyperscaler and a 100,000 barrel-per-day design were meaningful steps, but management named Texas permitting as the gating item, with six discharge permits pending. Progress there, or clearer timing on lithium and magnesium monetization, would help restore confidence in the longer-term case.
Sentiment has warmed from clearly bearish before last quarter's report to roughly neutral now, yet the stock tells a gloomier story. At $5.33 it trades far below its 200-day moving average of $8.85 and near the bottom of its post-earnings range of $4.87 to $9.16, well beneath the prior quarter's $6.86 to $11.58 band. Expectations look compressed, which lowers the hurdle but also signals deep skepticism.
The question that matters is whether TETRA can show its margin pressure is cyclical and timing-driven rather than structural. If fluids margins hold, water and flowback keeps improving and the Middle East and permitting risks stay contained, the past quarter's selloff will look overdone. If margins erode further on softer revenue, the market's verdict may prove right.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Sep-30 | |
| Sep-02 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-13 | |
| Jun-29 | |
| Jun-03 | |
| Jun-02 | |
| Jun-02 | |
| May-28 | |
| Apr-29 | |
| Apr-29 | |
| Apr-07 |
