TETRA Technologies Beats On A Decade-High Q3 And Guides 2027 Higher, But Completion Fluids Margin Compression Kept EBITDA Flat
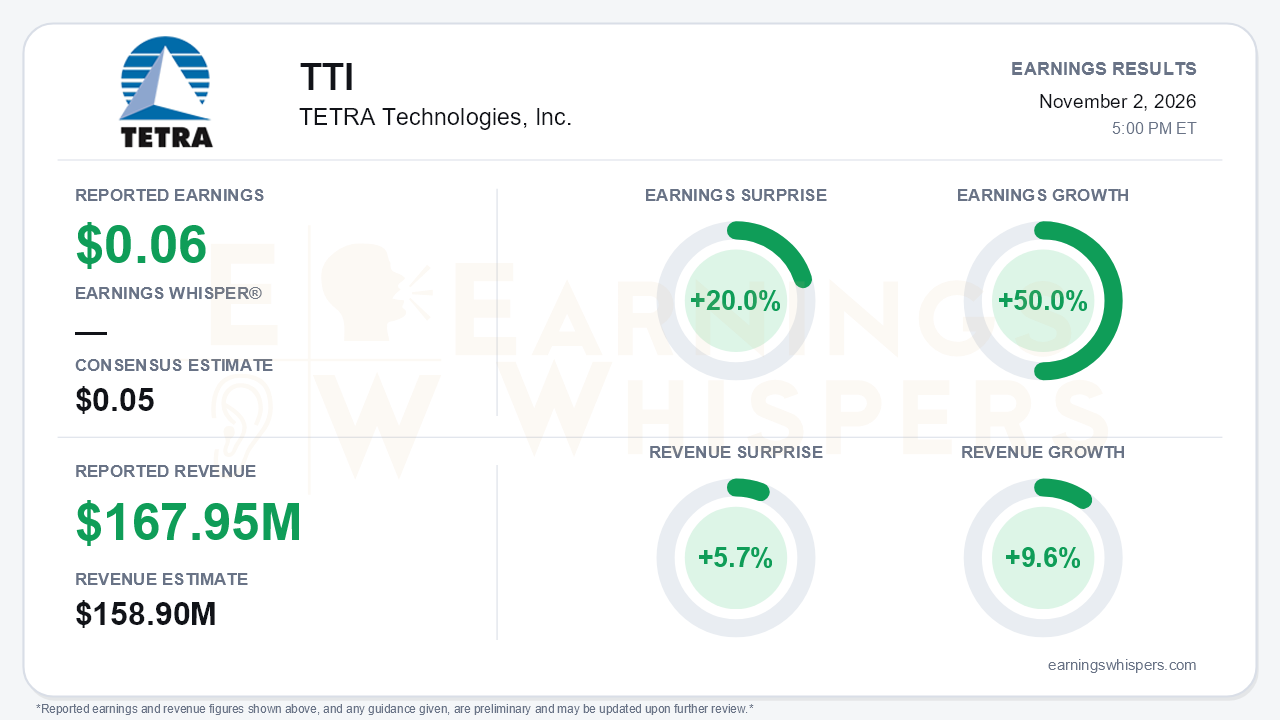
TETRA Technologies (NYSE: TTI) delivered a clean headline beat for the third quarter. Adjusted earnings of $0.06 per share topped the $0.05 consensus by 20.0%, and revenue of $167.95 million beat the $158.9 million estimate by 5.7%. Earnings grew 50.0% year over year and revenue rose 9.6%, the company's best third-quarter top line in a decade. Management paired the results with a fourth-quarter outlook calling for double-digit year-over-year growth in both revenue and Adjusted EBITDA, plus a first explicit view that 2027 revenue and EBITDA will rise from 2026. The central tension is that revenue growth is not yet turning into profit growth. Adjusted EBITDA of $25.1 million was essentially flat against $25.0 million a year ago and down sharply from $31.9 million in the second quarter. Consolidated margin slipped to 15.0% from 16.3%.
The quality of the earnings beat deserves scrutiny. Pretax income actually fell to $6.4 million from $8.1 million a year earlier. GAAP net income rose to $6.8 million largely because of a $0.4 million tax benefit and a drop in net interest expense to $2.4 million from $4.4 million. That interest decline was helped by capitalized interest on the Arkansas project. The adjusted figure strips out $3.9 million of unusual charges, chiefly $2.2 million of legal fees tied to a former subsidiary. It also removes a $1.9 million discrete tax benefit, so the $0.06 is not inflated by tax items. Even so, per-share growth came on a share count roughly 11% higher after this year's $108 million equity raise.
Beneath the consolidated numbers, the two segments moved in opposite directions. Water & Flowback was the clear standout:
- Revenue rose 21% and Adjusted EBITDA jumped 69%.
- Segment margin expanded to 16.7%, up from 14.8% in Q2 and 11.9% a year ago, and above the mid-teens guide management had set.
- Production testing grew 60% year over year, and Argentina revenue more than doubled on early production facility ramps and SandStorm utilization.
- International now represents 33% of segment revenue versus 15% in 2025.
Completion Fluids & Products went the other way. Its margin collapsed to 22.1% from 26.4% in Q2 and 30.5% a year earlier, and segment EBITDA fell to $20.3 million from $27.6 million. Management cited softer Gulf of America completion activity, product mix, and higher diesel, freight and Middle East shipping costs. The full-year margin for the segment is now expected at the low end of its 25-30% range. On the call, management also acknowledged that higher-cost third-party bromine will keep weighing on margins through 2027. That is a meaningful cut for the company's historically most profitable franchise.
The growth story nonetheless held up well:
- Industrial chemicals rose 32% and now exceed half of segment revenue, with semiconductor calcium chloride sales up 48%.
- Management described the deepwater outlook as stronger than the 8% CAGR presented at Investor Day.
- The first of three Neptune Z-Lite wells is scheduled for the fourth quarter.
- The Arkansas bromine plant remains on schedule and on budget, with equipment costs below the final investment decision estimate. Production is still targeted for early 2028.
- An October term loan amendment cut the interest margin by 75 basis points, extended maturity to December 2030 and deferred about $19 million of amortization.
The softer spots are timing and cash. Oasis desalination commercialization has slipped from the mid-2027 large-plant expectation, with six permit applications pending before the TCEQ and outside the company's control. Nine-month operating cash flow of $31.3 million trailed capex of $77.6 million, and 2027 remains a heavy investment year.
The market had already priced in considerable disappointment. Shares at $5.53 are down 30.9% from the $8.00 open following the August report and sit 36.6% below the 200-day moving average of $8.72. Investor sentiment improved substantially, rising from -0.39 to roughly neutral at -0.01. That suggests the pessimism that built through the quarter has largely unwound rather than flipped to optimism. Earnings Whispers trend readings are mixed: momentum is positive while price and AVWAP trends remain negative, consistent with a stock still repairing damage.
The bottom line is that TETRA beat on both lines and extended its growth outlook into 2027, but the quarter exposed a margin problem in completion fluids that bulls cannot dismiss. Water & Flowback and industrial chemicals are carrying the narrative while bromine costs, shipping and Gulf activity squeeze the core fluids business. Until the fourth-quarter guide translates into actual EBITDA growth rather than revenue alone, a deeply discounted stock and neutralizing sentiment leave the setup improved but unproven.
Read our earnings preview for TETRA Technologies, Inc.: https://www.earningswhispers.com/article/TTI/21437
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Sep-30 | |
| Sep-02 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-13 | |
| Jun-29 | |
| Jun-03 | |
| Jun-02 | |
| Jun-02 | |
| May-28 |
