Viper Energy's Promised Q3 Production Jump Faces A Test As Street Braces For Softer Quarter
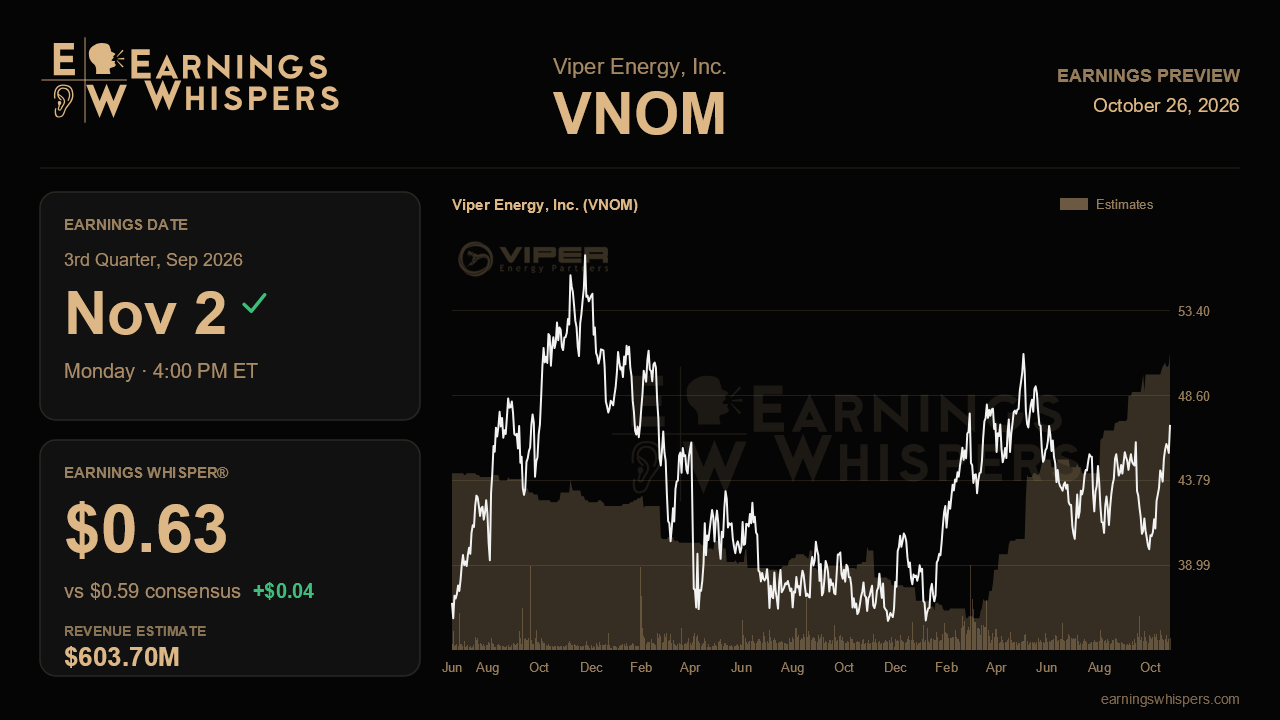
Viper Energy heads into its third-quarter report with an unusual split between what management promised and what Wall Street is penciling in. Three months ago the mineral and royalty owner told investors to expect roughly 4.5% sequential oil production growth this quarter, capping a year in which its organic growth outlook climbed from mid-single digits to high-single digits. Yet consensus calls for earnings of $0.59 per share on revenue of $603.7 million, both well below the $0.76 and $677.0 million Viper posted last quarter. The question for the November 2 report, due after the close, is whether higher volumes can offset whatever the Street is baking in for weaker realized pricing or fewer one-time items.
On a year-over-year basis the picture looks far healthier. Those estimates imply EPS growth of about 47.5% and revenue growth of 44.4% from the $0.40 and $418.0 million reported a year ago, a reflection of acquisitions such as Riverbend, which added around 2,000 barrels of oil per day, and the roughly $160 million drop-down from parent Diamondback. The Earnings Whisper sits at $0.63, a few cents above consensus, suggesting the more attentive crowd expects the volume story to show through. That is a modest premium rather than a call for a blowout, but it does set the effective bar slightly higher than the published number.
Production is the cleanest test of last quarter's narrative. Management raised its full-year oil outlook earlier in the year, then reframed 2026 as a high-single-digit organic growth year, with the third-quarter guide implying about 15% annualized oil-per-share growth versus the end of 2025. Delivering on that midpoint, or beating it, would validate the steady upward drift in guidance. Falling short would raise doubts precisely when the company has been leaning hardest on its growth credentials. Well activity is a useful companion metric: Viper counted 691 gross wells in the prior quarter, up from more than 650, and a continued rise would suggest the runway extends into 2027. Investors should also check whether the oil cut, which has slipped from the mid-50s toward the low-50s percent range, stabilizes, since oil barrels drive most of the royalty value.
Capital returns carry their own scrutiny. Viper lifted its base dividend 32% to $2.00 per share annually, which management said holds up down to $30 WTI, while dropping its commitment to return at least 75% of distributable cash each quarter and setting aside the variable dividend. This is the first full quarter under that flexible framework, so the size of buybacks, any debt reduction and fresh deal activity will show how management actually spends excess cash. Updates on the Spanish Trail Barnett tests, where Viper holds a full net royalty interest, and on Woodford and Delaware deep-rights leasing bonuses could add incremental upside to the inventory story.
The market has warmed to the stock even as sentiment cooled. Shares are up 8.8% since the last report against a flat S&P 500, trade above the 200-day moving average near $44.13, and at $46.94 sit within about 1% of the post-earnings high of $47.38, putting a breakout in view. Sentiment, however, has swung from 16.9% bullish before last quarter to 7.3% bearish now, a sign that some holders see the sequential decline in estimates as a warning.
Ultimately, this report hinges on whether Viper's volume growth is real and accelerating enough to make the lower sequential numbers look like a pricing blip rather than a stall. Hitting the production guide while showing disciplined use of cash under the new framework would keep the growth-plus-yield narrative intact and give the stock a reason to clear its recent ceiling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Sep-30 | |
| Aug-05 | |
| Aug-03 | |
| Jul-01 | |
| Jun-30 | |
| Jun-18 | |
| May-29 | |
| May-04 | |
| Apr-01 | |
| Mar-06 | |
| Mar-02 | |
| Mar-02 | |
| Feb-26 | |
| Feb-24 |
