Viper Energy Beats On Volume And Raises Guidance Again, But Cash-Funded Deals Mean Debt Is Rising And Buybacks Are Shrinking
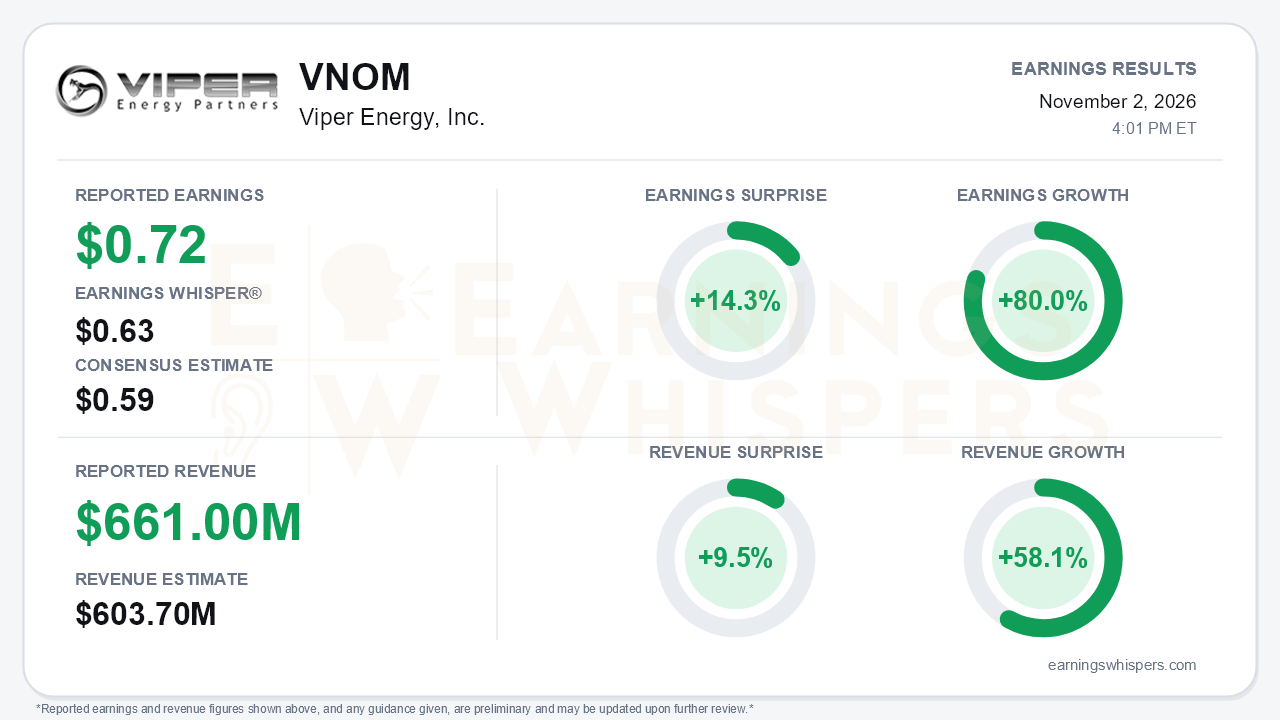
Viper Energy delivered a clean beat on both lines in the third quarter. Earnings of $0.72 per share topped the $0.59 consensus by 14.3% and cleared the $0.63 Earnings Whisper number. Revenue of $661.0 million beat the $603.7 million estimate by 9.5%. Earnings grew 80.0% year over year and revenue rose 58.1%.
The year-ago GAAP comparison was a net loss of $0.52 per share, weighed down by a $360 million impairment. This year's GAAP profit of $140 million attributable to Viper is a meaningful swing from that loss. The more important story, though, is that Viper grew its way through a weaker commodity tape.
The quality of the beat holds up because it was driven by barrels, not price. Average daily oil production reached 69,076 bo/d. That was above the high end of guidance, up more than 6% from 65,077 bo/d in the second quarter, and up 23% from a year ago.
The volume growth mattered because pricing moved the other way. Unhedged oil realizations fell to $87.65 from $98.28 sequentially, and the combined realized price slipped to $50.52/boe from $53.82. Derivatives also cost $31 million in the quarter.
A few other details add texture without changing the picture:
- Lease bonus income dropped to $4 million from $25 million a year ago, including related-party bonuses.
- Adjusted EBITDA margin of 90% trailed the 93% trailing-twelve-month figure.
- Free cash flow was $520 million, a 79% margin. GAAP operating cash flow was lower at $447 million because of working-capital drag.
The call reinforced that underlying activity on the acreage is improving. Diamondback turned 123 gross wells to production at a 9.4% average royalty interest, up from 114 in the first quarter. That is notably richer than the roughly 6% historical average management referenced last quarter.
Third-party activity held steady rather than accelerating. Gross wells turned to production were essentially flat at 689 versus 691. The forward pipeline remains deep:
- 104 rigs are running on Viper acreage, about 40% of the Permian total.
- 1,965 gross wells are in active development.
- 1,404 gross wells have line-of-sight to near-term development.
Management raised full-year oil guidance for a second consecutive quarter, to a 67,500 bo/d midpoint from roughly 65,500 bo/d earlier in the year. It also initiated fourth-quarter guidance of 70,000 to 71,000 bo/d, a figure that includes the pending Buckhorn deal.
The central tension is capital allocation. Viper spent heavily this quarter:
- It closed the $529 million McElroy Ranch acquisition, largely in cash.
- It agreed to buy Buckhorn for $280 million in cash plus 1.8 million shares.
- That brings cash-funded M&A this year to more than $1 billion.
Management framed this as the payoff from the revised return-of-capital framework announced in the second quarter: accretive deals with minimal equity. The cost to shareholders is visible, however:
- Net debt jumped to $2.4 billion from $1.6 billion at midyear.
- Interest expense per boe rose to $2.31 from $1.96 sequentially.
- Buybacks slowed to $90 million from $132 million in the second quarter.
- The variable dividend and the 75% minimum payout commitment are gone, leaving a $0.50 quarterly base dividend.
Income-oriented holders who owned Viper for near-total cash distribution now own a consolidation vehicle instead.
The acquisitions also stretch the duration of the growth story. McElroy is 96% undeveloped, with only 1.7 net producing horizontal locations today. Its value hinges on emerging Barnett development and on Chevron's timing, which operates about half of the net undeveloped Barnett inventory and which Viper does not control. Peak production is pegged at roughly 5,000 bo/d over the next decade.
Management further cautioned that organic growth percentages should moderate on a larger base and that 2027 third-party visibility is limited. Its tone was notably expansive, flagging possible surface, power and infrastructure opportunities across the Diamondback complex. It was also unusually candid: management acknowledged the stock's underperformance and called Diamondback's March share sale a mistake.
Investors were not buying the upbeat framing heading into the report. Earnings Whispers sentiment fell from 0.169 to -0.056, a meaningful shift from modestly positive to slightly negative. That likely reflects unease over leverage and the reduced payout.
Price action has been steadier than sentiment. Shares are up 6.0% since the open following the August report and sit about 2.9% above the 200-day moving average. Earnings Whispers trend readings are broadly positive, consistent with a stock that has been grinding higher rather than breaking down.
The bottom line is that Viper's operating engine is running hotter than expected, with production ahead of guidance, a richer Diamondback royalty mix and another guidance raise. The investment case has shifted, though, from cash-return yield toward levered, longer-dated inventory accumulation. Bulls get a credible growth runway. Skeptics have legitimate ammunition in rising debt, shrinking buybacks and acquisitions whose value depends on other operators' drilling schedules.
Read our earnings preview for Viper Energy, Inc.: https://www.earningswhispers.com/article/VNOM/21443
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Sep-30 | |
| Aug-05 | |
| Aug-03 | |
| Jul-01 | |
| Jun-30 | |
| Jun-18 | |
| May-29 | |
| May-04 | |
| Apr-01 | |
| Mar-06 | |
| Mar-02 | |
| Mar-02 |
