Valaris Needs A Sequential Earnings Rebound To Justify Its Rally Toward Range Highs
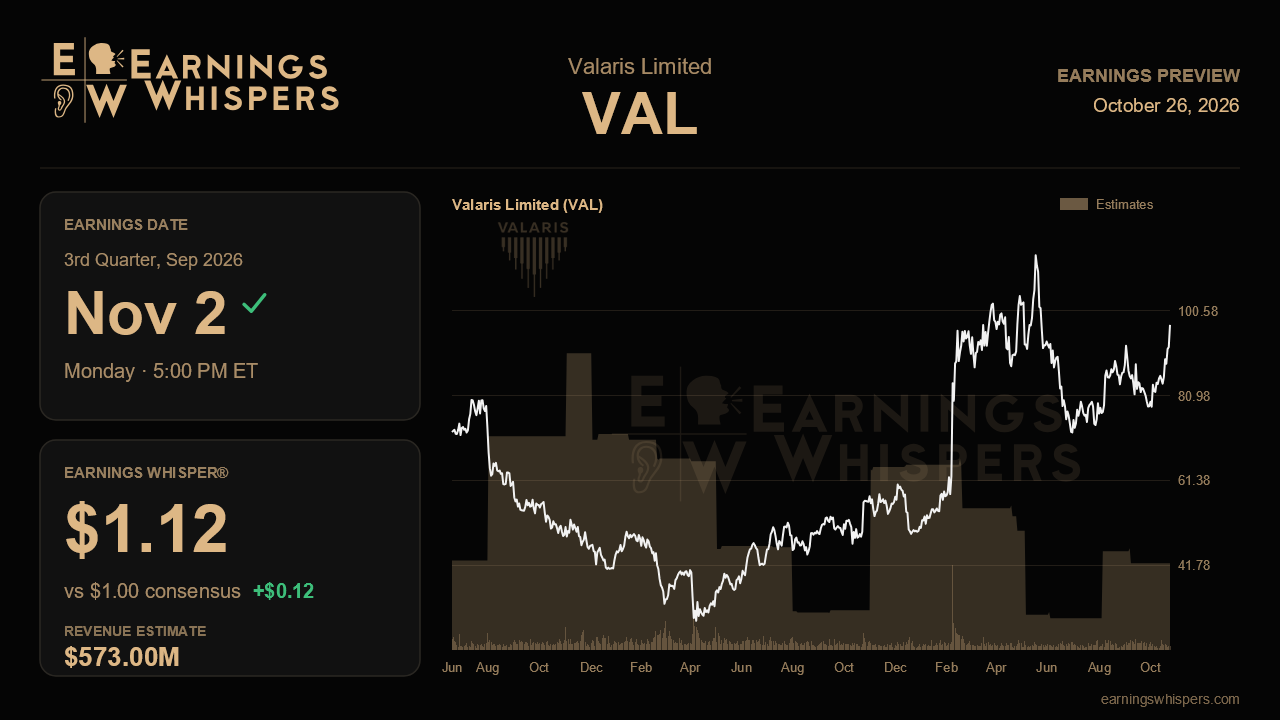
Valaris heads into its third-quarter report with a stock that has already priced in a fair amount of recovery. Shares have climbed nearly 19% since the last earnings release, while the S&P 500 slipped about 1%, and the offshore driller now trades within a couple of dollars of its post-earnings high. The year-over-year comparisons look ugly. The real test is whether the business can show a convincing sequential rebound from a soft second quarter, enough to support a rally that has come before the numbers.
Wall Street expects earnings of $1.00 per share on revenue of about $573 million. That would mean a 62% drop in per-share profit and a nearly 4% decline in revenue from a year ago, when Valaris earned $2.65 on $595.7 million in sales. The revenue decline is modest. The earnings decline is not, which suggests last year's profit figure was unusually rich and should not be read as a clean baseline. The more useful comparison is the second quarter, when Valaris earned $0.72 on $539.2 million. Against that, consensus implies revenue rising roughly 6% and earnings per share climbing nearly 40%. The Earnings Whisper of $1.12 sits about 12% above consensus, so the informal bar is higher than the published one. In practice, simply matching the Street may not be enough.
That gap between revenue growth and earnings growth is the heart of the setup. In offshore drilling, a large share of costs is fixed once a rig is crewed and working. Incremental revenue from more operating days, fewer idle periods between contracts or better day rates tends to drop heavily to the bottom line. The consensus math assumes a meaningful chunk of the roughly $34 million in added revenue turns into profit. If revenue lands near $573 million but earnings stall well short of $1.00, it would point to cost pressure, reactivation or mobilization expenses, or unplanned downtime eating into margins. If revenue beats and margins widen with it, the case that the second quarter was a trough gets much stronger.
Beyond the quarter itself, the release needs to address durability. Management has not issued formal guidance since the last report, so investors will rely heavily on any update on fleet utilization, contract coverage and the pace of new awards. A shrinking gap between rigs on contract and rigs available, or new work at firm pricing, would support the sequential story. Long idle stretches, early terminations or vague timing on future contracts would undercut it, especially with the stock near recent highs.
Sentiment has warmed considerably. Readings remain slightly bearish at about 10%, but that is a sharp improvement from roughly 41% bearish ahead of the prior report. Combined with the stock's 20-point outperformance and its position well above the 200-day moving average near $85, the mood has shifted from skepticism toward cautious optimism. The shares are testing the top of their post-earnings range near $98.83. A clean move above that level would put the wider prior-quarter range, which peaked above $114, back in view. Failure there would leave room to retreat toward the high $70s.
The central issue is conversion. Valaris does not need a blowout revenue quarter, but it does need to show that a modest top-line recovery can produce a large earnings recovery and that contract activity supports more of the same. Deliver that, and the rally has a foundation. Fall short on margins, and the year-over-year decline will look less like a temporary dip and more like a lower earnings plateau.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Oct-14 | |
| Oct-07 | |
| Oct-07 | |
| Sep-11 | |
| Aug-21 | |
| Aug-05 | |
| Aug-05 | |
| Jul-09 | |
| Jul-09 | |
| Jun-12 | |
| Jun-12 | |
| May-04 | |
| May-04 | |
| Apr-14 |
