Unitil's Quiet Quarter Becomes First Real Test Of New Rates And Water Deal
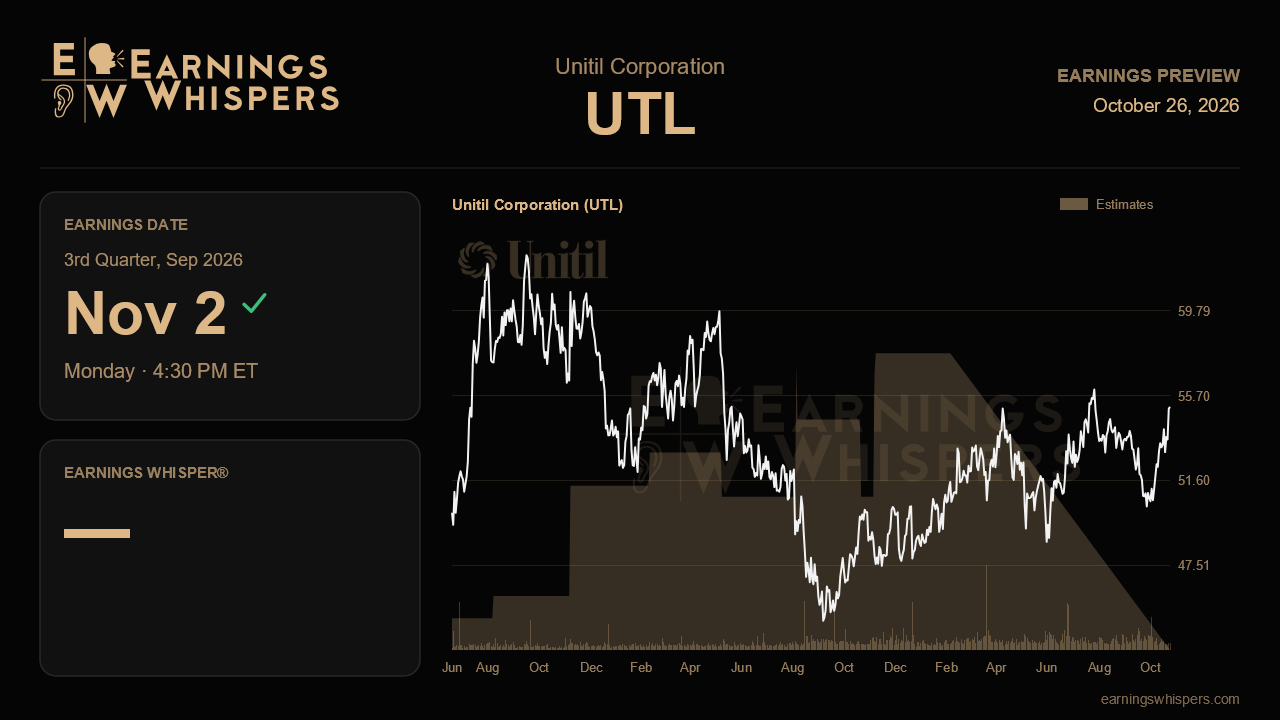
The third quarter is usually the one Unitil investors would rather skip. Heating demand vanishes, gas margins thin out, and a year ago the company earned just three cents a share on $101.1 million of revenue. This time the seasonal lull carries more weight than usual. It is the first full quarter that captures both a $13 million New Hampshire electric rate award, effective in May, and $5.5 million of temporary New Hampshire gas rates that kicked in on June 1. It is also the first quarter with the newly acquired New Hampshire water businesses on the books. A summer quarter that looks noticeably better than last year's near breakeven result would be the cleanest proof yet that the rate case machinery is converting into earnings.
A usable Street consensus for the quarter is not available, so the more meaningful yardstick is management's own full-year target. Unitil reaffirmed adjusted EPS guidance of $3.20 to $3.36 last quarter after posting $2.17 in the first half, up about 7% from a year earlier. Hitting the $3.28 midpoint therefore requires roughly $1.11 from the back half, with the bulk traditionally arriving in the fourth quarter as heating season resumes. That makes the September quarter less about the absolute number and more about whether the rate step-ups are visible enough to keep the full-year math comfortable. A third quarter that merely matches last year's thin result would put more pressure on a cold, profitable finish.
The prior call leaned clearly constructive. Electric adjusted gross margin rose nearly 15% in the first half and gas margin climbed 13.5%, helped by Maine Natural Gas, customer growth and higher rates. The five-year capital plan was lifted to about $1.2 billion, roughly 24% above the prior plan, and rate base grew almost 15% year over year. Perhaps most notable was demand: gas conversion inquiries jumped about 50% in the first half, with around 1,500 customers under contract or construction, a sharp shift from earlier remarks that it was too soon to read trends. Validation this quarter would look like continued customer additions, steady margin growth outside of weather, and confirmation that the capex ramp is proceeding without straining a balance sheet that showed funds from operations to debt of 17.2%.
There are also clear limits on what the quarter can deliver. Management described the $55.8 million water acquisition as earnings-neutral for 2026, so any contribution now should be modest, and the real payoff depends on future rate outcomes. Permanent New Hampshire gas rates are not expected until April 2027, and the $10.4 million Maine Northern Utilities case filed in June is still early in the process. The Massachusetts Aquarion piece remains only a non-binding letter of intent tied to an Eversource rate case, and any sign that path is slipping further would chip at the growth story. Notably, the 5% to 7% long-term growth rate was reaffirmed rather than raised despite the bigger capital plan, leaving room for an upgrade if regulatory progress allows.
The market has treated Unitil well since its last report. Shares rose 4.6% while the S&P 500 was essentially flat, and at $55.15 the stock sits comfortably above its 200-day moving average and is pressing against its post-earnings high of $55.19, effectively testing a breakout, though still below the prior quarter's $57.26 peak. Sentiment has moved the other way, with bearish readings climbing to 66% from about 36% heading into the last report. That divergence suggests the recent price strength is not resting on broad enthusiasm, which can make a stock that is near the top of its range vulnerable if the numbers are flat.
Ultimately, the report will be judged on whether the new rates are showing up as advertised. If the summer quarter demonstrates meaningful year-over-year improvement, steady conversion momentum and an intact full-year range, the improving narrative holds and a breakout becomes easier to justify. If the gains are hard to see, the reaffirmed rather than raised guidance may start to look like caution rather than conservatism.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 | |
| Jul-28 | |
| Jul-21 | |
| Jul-07 | |
| Jul-01 |
Unitil completes purchase of two affiliate water companies
UTL
New Hampshire Union Leader, Manchester
|
| Jun-30 | |
| May-04 |
