Unitil's Seasonal Q3 Loss Widens As Cost Growth Outpaces Rate Relief, Leaving Q4 To Carry Reaffirmed Guidance
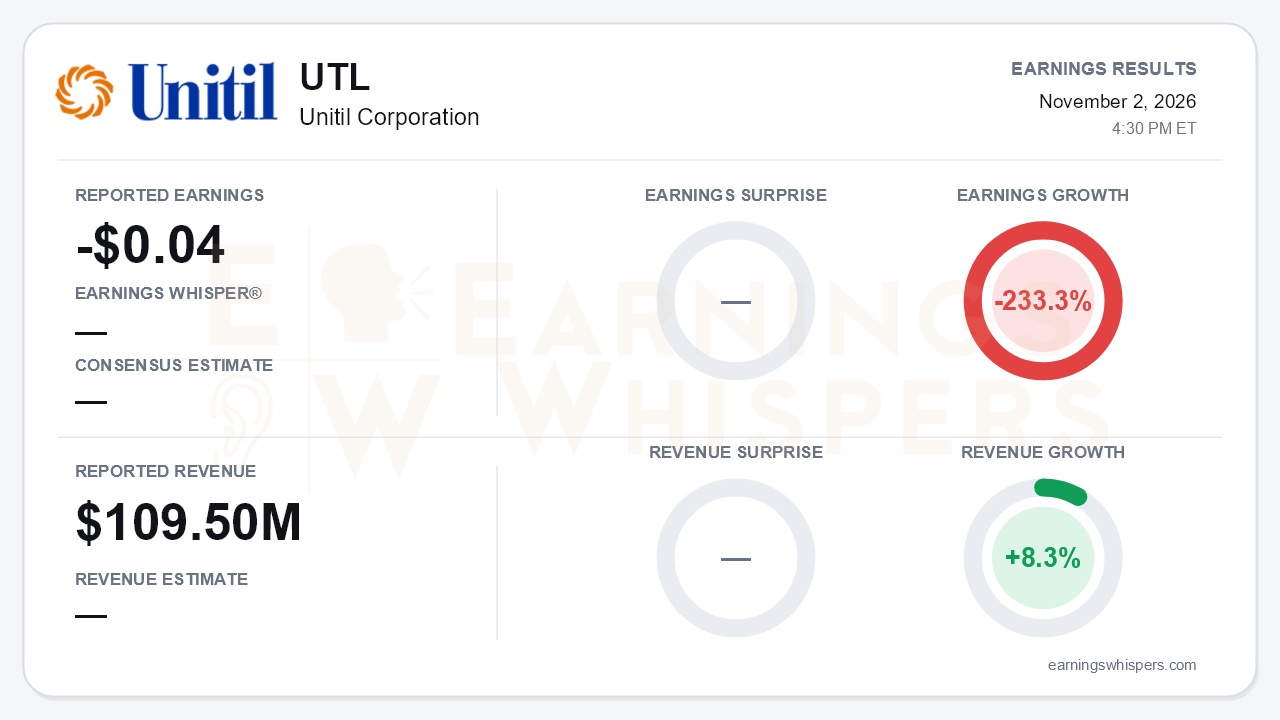
Unitil Corporation reported an adjusted loss of $0.04 per share for the third quarter, compared with adjusted earnings of $0.03 a year earlier. That is a 233.3% year-over-year decline in earnings, even as revenue rose 8.3% to $109.5 million. On a GAAP basis, the net loss widened to $0.08 per share from $0.02. The difference reflects $0.8 million of transaction costs tied to the Bangor, Maine Natural and Aquarion acquisitions.
The third quarter is seasonally Unitil's weakest because gas heating demand is minimal, so a small loss is not alarming on its own. The problem is direction. Rate increases and acquisitions are expanding the top line, but costs grew faster than margin.
- **Margin:** Total adjusted gross margin rose $4.3 million to $64.0 million, helped by gas therm sales up 10.5% and electric kWh sales up 1.3%.
- **Operating costs:** O&M rose $4.9 million, D&A rose $2.6 million and net interest expense rose $2.1 million.
- **Legacy costs:** Excluding Maine Natural, the Aquarion companies and transaction costs, legacy O&M still increased $2.4 million in the quarter. That was most of the $3.8 million legacy increase for the full nine months.
That is the central tension. The rate-base growth story remains intact, but the quarter showed cost pressure and financing drag absorbing much of the incremental margin.
The year-to-date picture shows the deceleration more clearly. Nine-month adjusted EPS of $2.12 is up $0.09, or 4.4%, from $2.03. That compares with gains of $0.14 at both the first-quarter and first-half marks, which were growth rates near 7%-8%. Margin growth also slowed:
- Electric adjusted gross margin growth eased to 11.1% year-to-date from 14.8% at midyear.
- Gas adjusted gross margin growth slipped to 12.8% from 13.5%.
Meanwhile, nine-month O&M growth of $8.2 million compares with roughly $3.3 million at the half. In the second quarter, management had emphasized that legacy O&M was up only about 1%. That claim looks dated now.
Management reaffirmed 2026 EPS guidance of $3.20-$3.36 and its 5%-7% long-term growth target for the fourth consecutive call. The balance-sheet work is largely done:
- a $200 million private placement at a 5.76% weighted average rate;
- $27.3 million of at-the-market equity issued year-to-date;
- acquisition term loans fully repaid in October.
The acquisitions are now permanently financed, and S&P FFO-to-debt held near 17%.
Rate base is up 14.9% year over year. Management's five-year average rate base growth of 9.5% sits above its 6.5%-8.5% guide. Maine Natural is fully integrated, and Aquarion's New Hampshire water operations contributed $3.1 million of revenue in their first quarter. Rate cases supply the next leg of earnings:
- New Hampshire gas has $5.5 million of temporary rates in place and permanent rates expected April 1, 2027.
- The Maine gas case, seeking $10.4 million, is proceeding.
The risks are more about timing and execution than thesis. Hitting the $3.28 guidance midpoint requires roughly $1.16 in Q4, versus about $1.13 a year ago. That is achievable, but it leaves the full year dependent on winter weather and cost control. The Aquarion Massachusetts acquisition now hinges on a base rate case expected to be filed around mid-November, with a possible order in the second half of 2027. That pushes the Eversource purchase further out. Management's tone was also noticeably more muted. Second-quarter language about "outstanding performance" and fully earning authorized returns gave way to "disciplined execution." Commentary on gas conversions, which had cited a 50% rise in inquiries last quarter, disappeared. No analysts asked questions.
Investors have turned more skeptical. Earnings Whispers sentiment fell from -0.36 to -0.62, a meaningful move deeper into negative territory. The stock tells a different story. Shares have gained 7.1% since opening at $52.71 after the August report and closed at $56.44, about 7.6% above the 200-day moving average of $52.46. The price and AVWAP trend readings remain positive. That divergence matters. The market has rewarded the defensive, rate-base-driven profile, while investors weigh slowing earnings momentum and a back-end-loaded year. A stock trading above trend with souring sentiment leaves less cushion if Q4 falls short of the roughly $1.16 needed.
The bottom line is that Unitil delivered on the structural pieces: financing, integration, rate base growth and reaffirmed guidance. However, the quarter's earnings quality deteriorated as O&M, depreciation and interest costs outran margin growth. Bears have legitimate ammunition in the slowing year-to-date trend and the more cautious tone. Bulls can point to a rate-case pipeline that should restore momentum in 2027. Until Q4 shows the cost curve bending, the gap between rising shares and falling sentiment is the key tension to watch.
Read our earnings preview for Unitil Corporation: https://www.earningswhispers.com/article/UTL/21440
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-20 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Aug-03 | |
| Jul-31 | |
| Jul-28 | |
| Jul-21 | |
| Jul-07 |
