Alkermes Faces A Planned Profit Dip As R&D Ramp Tests Orexin Optimism
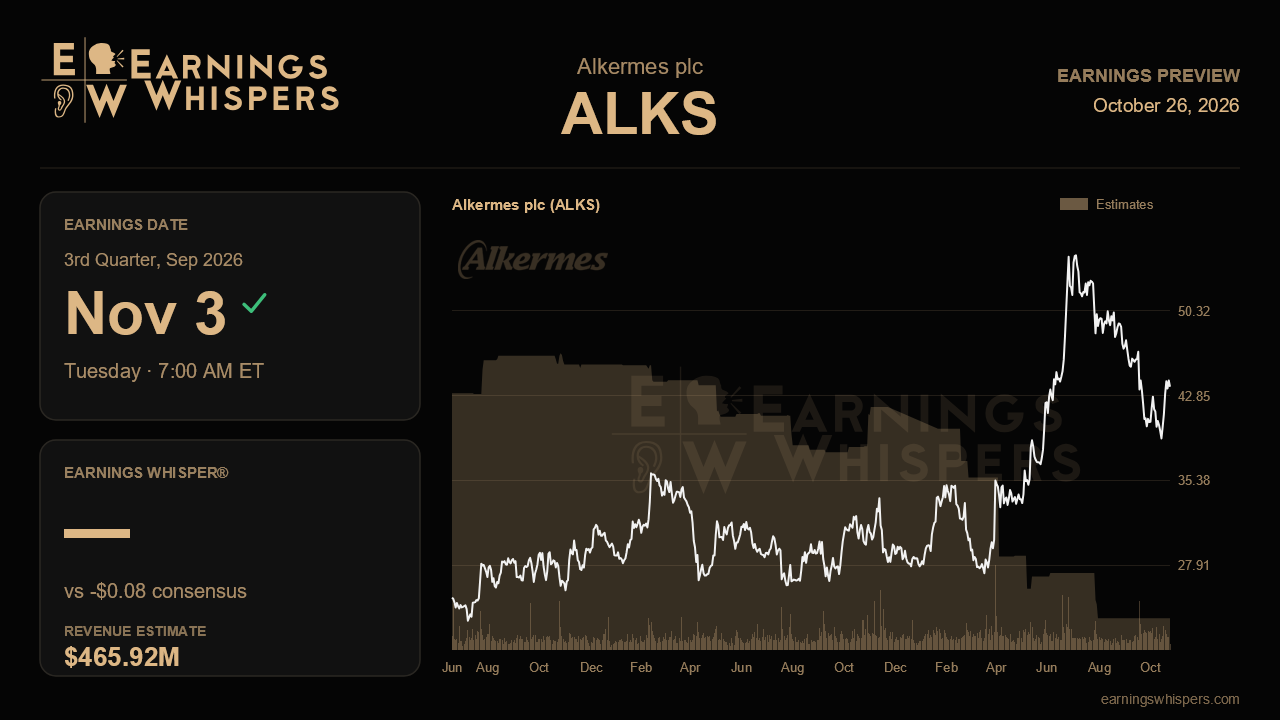
Alkermes heads into its third-quarter report with an unusual setup: management has already told investors that profits will fall sharply, and the stock has been punished anyway. Shares are down 13.5% since the last report, trailing the S&P 500 by more than 16 percentage points. That came after a quarter in which the CEO sounded more confident than at any point in the past year. The question for the November 3 release is whether the expected step down in earnings reads as the deliberate investment management described, or as the start of something less comfortable.
The Street expects a loss of 8 cents a share, compared with a profit of 49 cents a year ago. Revenue is forecast at $465.9 million, up 18.2% from the prior-year quarter but below the $496.0 million reported last quarter. The gap between those two trends is mostly explained by management's own guidance. Alkermes guided third-quarter proprietary sales to $390 million to $410 million excluding one-time items. Last quarter's results were helped by roughly $8 million of favorable gross-to-net adjustments and a $7 million Lumerize inventory timing benefit, and both are expected to reverse. R&D is guided to $120 million to $130 million, up from $112.9 million, and adjusted EBITDA is expected at $80 million to $100 million, down from $139.2 million. A sequential decline that lands inside those ranges should not surprise anyone. A shortfall below them would.
For the full year, Alkermes reaffirmed revenue guidance of $1.73 billion to $1.84 billion. Consensus of $1.81 billion sits in the upper half of that range, so the Street is already giving management credit for solid execution. That leaves limited room for disappointment in the commercial lines that drove last quarter's momentum. Lumerize is the clearest test. Patients on therapy climbed from about 3,500 at the end of last year to roughly 3,900 last quarter, and investors will want those steady sequential gains to continue once the inventory benefit falls away. Lybalvi is the second swing factor. Management raised its full-year gross-to-net expectation to the high 30s, giving up some price in exchange for coverage of more than 80% of insured lives through three large Part D plans. This quarter should start to show whether that broader access is turning into faster prescription growth, because the higher discount cost is visible immediately while the volume benefit has to be earned.
The pipeline may matter as much as the income statement. Top-line Phase 1b data for ALK7290 in ADHD were due by the end of the third quarter. That would be the first test of an orexin-2 agonist outside sleep disorders, and this report is management's first formal chance to put the result in context. Progress on the Lumerize idiopathic hypersomnia filing, slated for year end, and enrollment in the elixirexin Phase 3 program will help show whether the higher R&D spending is buying the catalysts promised. Competition has become a bigger part of the story, too. Takeda is positioned to launch first in narcolepsy type 1 and could set the class price corridor, while Lilly has widened its own Phase 2 effort.
Sentiment has cooled noticeably, shifting from moderately bullish before the last report to slightly bearish now. The stock sits at $43.63, above its 200-day moving average of about $40, in the lower middle of its post-earnings range of $38.98 to $52.51. The lowered expectations give a clean quarter some room to be rewarded.
Ultimately, the narrative holds if the earnings dip is fully explained by planned R&D and the reversal of one-time benefits, while Lumerize patient growth and Lybalvi volume prove the commercial engine is intact. Steady sales alongside a credible orexin readout would support management's optimism. Any softness in demand would make the margin squeeze much harder to defend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-20 | |
| Oct-16 | |
| Oct-13 | |
| Sep-22 | |
| Sep-21 |
How Alkermes Used Its Narcolepsy Playbook In ADHD - And Seemingly Won
ALKS
Investor's Business Daily
|
| Sep-21 | |
| Sep-16 | |
| Sep-10 | |
| Aug-24 | |
| Aug-06 | |
| Jul-28 | |
| Jul-28 | |
| Jul-14 | |
| Jul-13 |
