ADT's Cash Machine Is Humming, But Shrinking Subscriber Adds Remain The Real Test
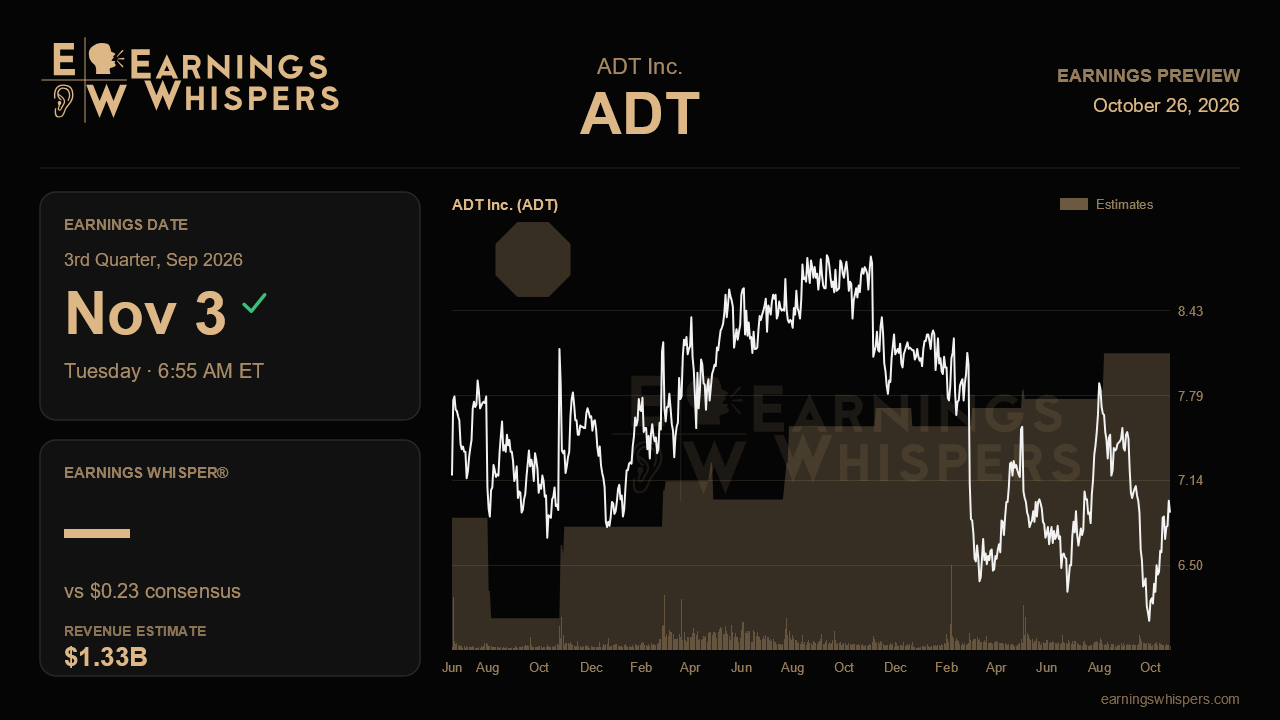
ADT heads into its third-quarter report with a split personality. Last quarter management delivered its first guidance raise after two straight flat outlooks, powered by surging free cash flow and aggressive buybacks, yet the engine that ultimately feeds a subscription business, new accounts, kept losing speed. The stock has sided with the skeptics, falling 5.5% since that report while the S&P 500 gained 3.3%. The November 3 release, due before the open, needs to show that the better financial story is not simply outrunning a weakening customer funnel.
The bar itself is modest. Analysts expect earnings of $0.23 a share, up about 4.6% from $0.22 a year ago, on revenue of roughly $1.33 billion, a 2.5% increase. That is low-single-digit growth, consistent with a mature, recurring-revenue model rather than a turnaround. Management now guides to full-year adjusted earnings of about $0.91 a share and revenue near $5.23 billion, up from $0.89 and $5.13 billion previously. Consensus sits right on the earnings target but only around $5.16 billion on revenue, well short of the company's outlook. In other words, the Street has accepted the profit raise but remains unconvinced on the top line, which makes the revenue figure arguably more telling than the per-share number this time.
That skepticism is rooted in the subscriber data. In the second quarter, gross recurring monthly revenue additions fell 17% and gross unit adds dropped 22% from a year earlier, extending a multi-quarter pattern of shrinking bulk account purchases, a deliberate wind-down of the affiliate channel and softness among dealers. Monitoring and services revenue slipped about 1%, partly because of last year's multifamily divestiture. Installation revenue jumped 17% as customers shifted toward buying equipment outright under ADT Plus, but that is a one-time sale, not the recurring stream that drives valuation. Validation this quarter would look like a narrowing in the gross add decline, attrition holding near 13.1% without further non-pay deterioration, and direct do-it-for-me growth continuing in the high single digits. A deeper slide in adds, or a tick up in attrition, would suggest the guidance raise leaned more on financial engineering than on the business.
Several newer initiatives deserve early scorecards. The ADT Blue self-install product launched last quarter, with most buyers choosing the fully monitored tier, so any color on volumes and whether it adds incremental customers rather than cannibalizing professional installs will matter. The dealer migration to ADT Plus began in July and is expected to take three to four quarters, making this the first period with real data on whether it stabilizes dealer production. Management should also update on AI tools that cut human-handled contacts by about a fifth, a lever for service margins, and on Origin AI smart plug pilots slated for this fall.
Cash flow is the other pillar. Adjusted free cash flow rose 64% through the first half, and the full-year target was lifted to roughly 30% growth. But management itself warned that much of that strength stems from tax planning and working capital timing, and that 2027 brings an estimated $50 million to $100 million each in higher cash taxes and cash interest as swaps expire and cheap notes refinance. Any early framing of next year will draw scrutiny.
Sentiment has improved, with bearishness easing to about 30% from 51% ahead of the last report, yet the shares sit at $6.90, below the 200-day average of $7.09 and in the lower half of their post-earnings range. That combination suggests skepticism has softened but not lifted. Ultimately the verdict turns on one question: can ADT show its subscriber base is stabilizing, so the cash and earnings gains look durable rather than borrowed from a shrinking funnel?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 42 min | |
| Oct-20 | |
| Sep-14 | |
| Sep-10 | |
| Aug-17 | |
| Aug-03 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-16 | |
| Jun-18 | |
| Jun-17 | |
| May-20 | |
| May-12 | |
| May-04 |
