ADM's Biofuel Windfall Faces Its Proof Test As Whisper Number Runs Well Ahead Of Consensus
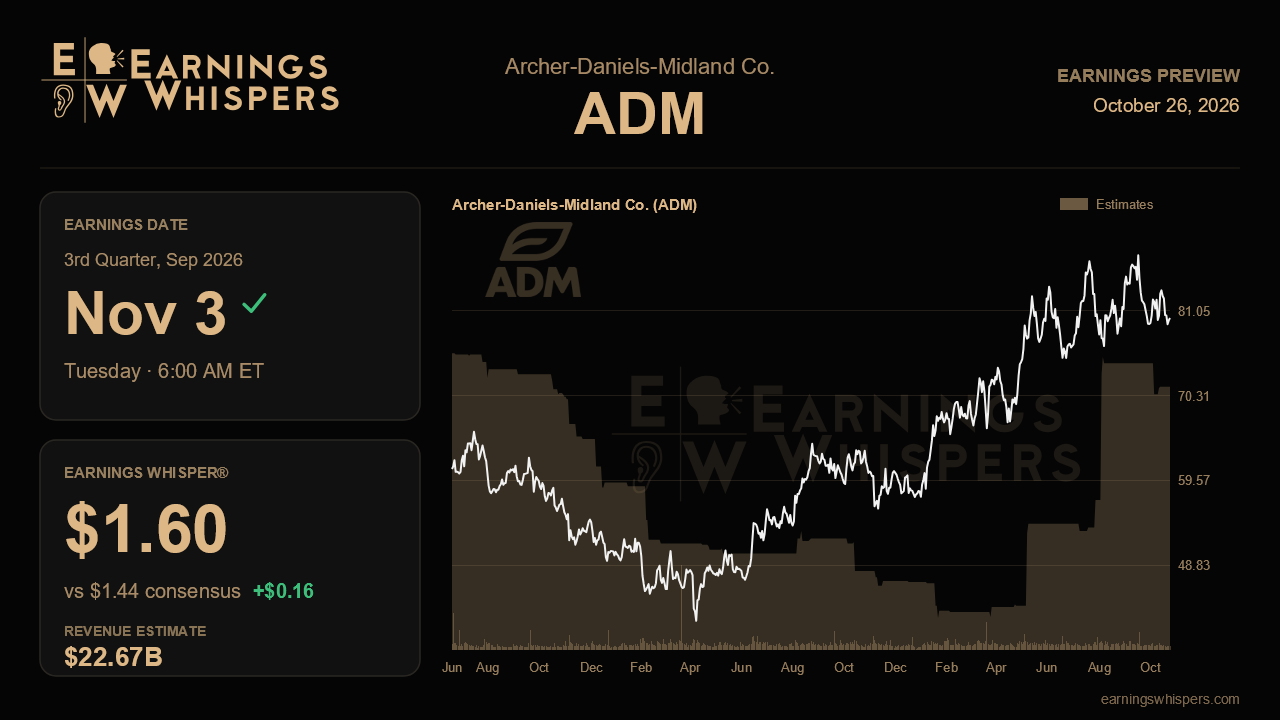
Archer-Daniels-Midland spent the past two quarters turning a guidance cut into a comeback story, and the third-quarter report due before the bell on November 3 will show whether that story has staying power. After raising its full-year outlook twice in a row, management has set a high bar for itself. The open question is whether the crushing recovery that powered the second quarter can carry into the back half of the year, or whether the second quarter marked the peak.
The Street is looking for earnings of $1.44 a share on revenue of about $22.67 billion. That would be a 56.5% jump from the $0.92 earned a year ago on sales growth of roughly 11%, a sharp year-over-year improvement. Sequentially, though, it would be a step down from the $1.84 posted last quarter, a sign that analysts expect some cooling in margins. The whisper number of $1.60 sits a meaningful 16 cents above consensus, so the market's informal bar is closer to a repeat of second-quarter strength than to a pullback. Full-year consensus of $4.76 also sits well below management's raised range of $5.15 to $5.60. Either analysts doubt the guidance or their models have not caught up with it. A solid third quarter would pressure estimates higher, while a soft one would suggest the skeptics had a point.
Crushing is the swing factor. That business went from a $79 million loss in the first quarter to $363 million in operating profit in the second, helped by clearer federal biofuel mandates and a 45Z tax credit benefit that management has raised from about $100 million to roughly $250 million. Global crush volumes accelerated to 5% growth. To validate the narrative, ADM needs to show that crush margins held up and that volumes kept rising. The Q2 call also introduced a plan to de-bottleneck four U.S. crush plants for about $100 million, a fraction of greenfield cost, and an update on timing would show whether management is leaning into the cycle. One caveat matters: only about 30% of North American fourth-quarter crush was locked in at the time of the last call. Commentary on how much of that book has since been secured may matter more for the stock than the headline number.
Ag Services and Nutrition are the supporting cast. Ag Services profit rose to $293 million as China resumed U.S. soybean buying under a roughly 25 million ton commitment, so evidence that those shipments kept flowing near the pace of about a million tons a week would support the fall export season. Nutrition grew operating profit 51% even as revenue slipped 5%, partly due to portfolio moves. Continued progress in flavors, along with signs that the natural colors push, which management sized at about $1 billion in U.S. demand, is producing revenue, would bolster the case that ADM is more than a commodity trade. The weak spots to monitor are liquid sweeteners in North America, refined products under South American oversupply, and declining Wilmar equity earnings. Higher energy and packaging costs tied to Middle East oil volatility could also squeeze Nutrition margins.
Sentiment has flipped from mildly bearish before the last report to solidly bullish now, and the shares have gained about 2.6% since then while the S&P 500 was flat. Still, at around $80 the stock trades much closer to the bottom of its post-earnings range of roughly $76 to $89 than the top, though it remains above its 200-day average near $76. The market has given ADM credit, but not a blank check.
The verdict hinges on durability. If crush margins and volumes hold, the fourth-quarter book is filling at attractive levels and management reaffirms or nudges up its range, perhaps alongside clarity on the share repurchases it was evaluating, the comeback narrative stays intact. If the quarter merely meets the sequentially lower consensus and fourth-quarter visibility looks thin, the gap between guidance and Street estimates will look like caution rather than opportunity.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-06 | |
| Oct-02 | |
| Sep-29 | |
| Sep-22 | |
| Sep-21 | |
| Sep-18 | |
| Sep-15 | |
| Sep-15 | |
| Sep-07 | |
| Sep-04 | |
| Aug-27 | |
| Aug-24 | |
| Aug-18 | |
| Aug-17 |
