ADM Beats And Raises Again On Biofuel Tailwinds, But Peak Crush And A Weaker Q4 Path Temper The Story
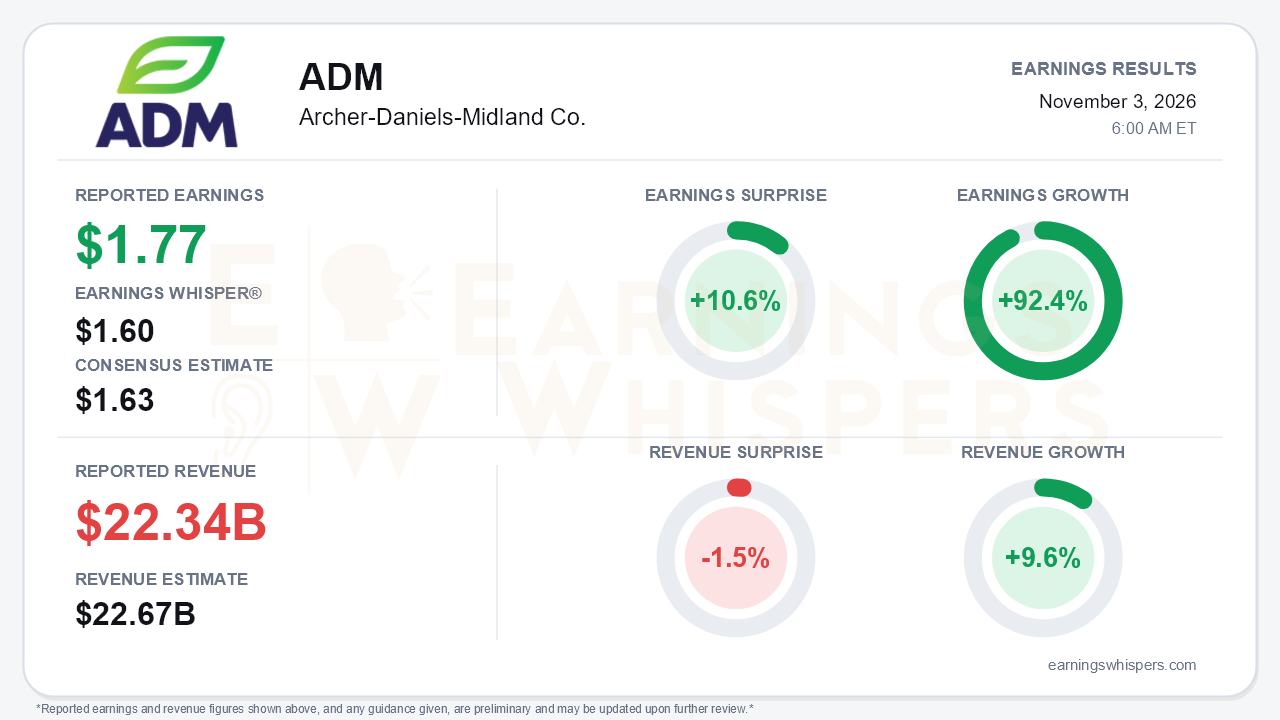
Archer-Daniels-Midland delivered another policy-fueled beat. Adjusted EPS of $1.77 topped the $1.63 consensus and the $1.60 Earnings Whisper number by 10.6%, and earnings grew 92.4% year over year. GAAP EPS rose to $1.70 from $0.22, reflecting both stronger operations and the absence of last year's heavy impairment and Wilmar-related charges. Revenue of $22.335 billion grew 9.6% but missed consensus by 1.5%. ADM also raised full-year adjusted EPS guidance for the third straight quarter, to $5.50-$5.80 from $5.15-$5.60. The central tension is that this looks like a peak quarter rather than an inflection. Adjusted EPS slipped from $1.84 in Q2, and management signaled that crush margins likely topped out in Q3.
The beat deserves some scrutiny. Total segment operating profit rose 64% to $1.38 billion, but the gain was concentrated in two places. Crushing profit jumped to $311 million from just $13 million, and Vantage Corn Processors rose to $146 million from $43 million. Both were driven by North American biofuel economics: the RVO finalized in March, higher energy prices, and ethanol policy incentives. AS&O included roughly $35 million of net positive mark-to-market and timing effects, mostly in Refined Products. Other Business got a one-time lift of about $40-50 million from an insurance reserve release. Excluding those items, the quarter still clears expectations, but by a narrower margin than the headline suggests.
Beneath the biofuel strength, the operating mix softened. Ag Services profit fell 9% to $172 million after rising 159% in Q2, hurt by an inventory revaluation tied to Ukraine's export shutdown. Global crush volume growth slowed to 1.6% from roughly 5% in Q2. Nutrition growth nearly stalled at 3% ($134 million) versus 51% the prior quarter. Human Nutrition actually declined 3% on unplanned plant downtime, input inflation and Biotics softness. Liquid sweeteners also remain weak, with contracting season visibility limited. Animal Nutrition was a bright spot, up 21% on portfolio actions and operational improvements, and Carbohydrate Solutions accelerated to 40% growth from 22%.
The forward story rests heavily on policy. Management lifted its expected 45Z net benefit to about $350 million, up from roughly $250 million last quarter and $100 million at the start of the year. That progression explains much of the guidance ratchet. The arithmetic of the new range is less flattering, though. With $4.33 of adjusted EPS through nine months, guidance implies fourth-quarter adjusted EPS of roughly $1.17 to $1.47, clearly below Q3. The guidance raise was also viewed as in line with estimates, so it validated expectations rather than reset them higher. Initial 2027 framing was "similar to 2026, plus or minus," alongside higher interest and investment costs and open questions about policy durability. Brazil's delayed biofuel policy is already pressuring South American crush margins.
Capital allocation offers support. ADM resumed buybacks with about $360 million repurchased, trimmed 2026 capex to $1.2-$1.3 billion, and reported trailing adjusted ROIC of 9.0%, up from 6.3% at year-end. Cash generation needs a caveat. Operating cash flow before working capital reached about $3.0 billion year to date. Reported operating cash flow, however, fell to $1.8 billion from $5.8 billion as working capital absorbed cash, and short-term debt rose to $1.16 billion from $246 million. Newer initiatives include the CJ lysine JV, carbon removal credits at Columbus, precision fermentation and a new COO. These are longer-dated optionality, not near-term earnings drivers.
The market had already been fading the story before the print. Shares closed at $75.77 on the eve of the report, down 3.0% since the open after the August release. That is about 1% below the 200-day moving average and just above the inter-earnings low of $75.31 set the same day. The stock had hit a 52-week high of $88.75 in September and has since given back the entire rally, now sitting 14.6% below that peak. Investor sentiment was roughly unchanged, edging from -0.064 to -0.053, so it remains slightly negative. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative. Taken together, the market appears to be pricing a cyclical peak more than rewarding the guidance raises.
The bottom line is that ADM's quarter was strong on paper and the third guidance increase keeps the 2026 earnings story intact. The quality of that strength, however, leans on biofuel policy, timing gains and a one-time reserve release, while Ag Services, Nutrition and crush volumes all decelerated. With Q4 implied lower and 2027 framed as flat-ish, bears have legitimate ammunition that earnings are cresting. The stock's slide to the bottom of its range suggests investors are already discounting that peak.
Read our earnings preview for Archer-Daniels-Midland Co.: https://www.earningswhispers.com/article/ADM/21451
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 3 hours | |
| 6 hours | |
| 7 hours | |
| Nov-02 | |
| Oct-26 | |
| Oct-06 | |
| Oct-02 | |
| Sep-29 | |
| Sep-22 | |
| Sep-21 | |
| Sep-18 | |
| Sep-15 | |
| Sep-15 |
