After A 34% Rally, Waystar Must Show Its Retention Slide Has Bottomed
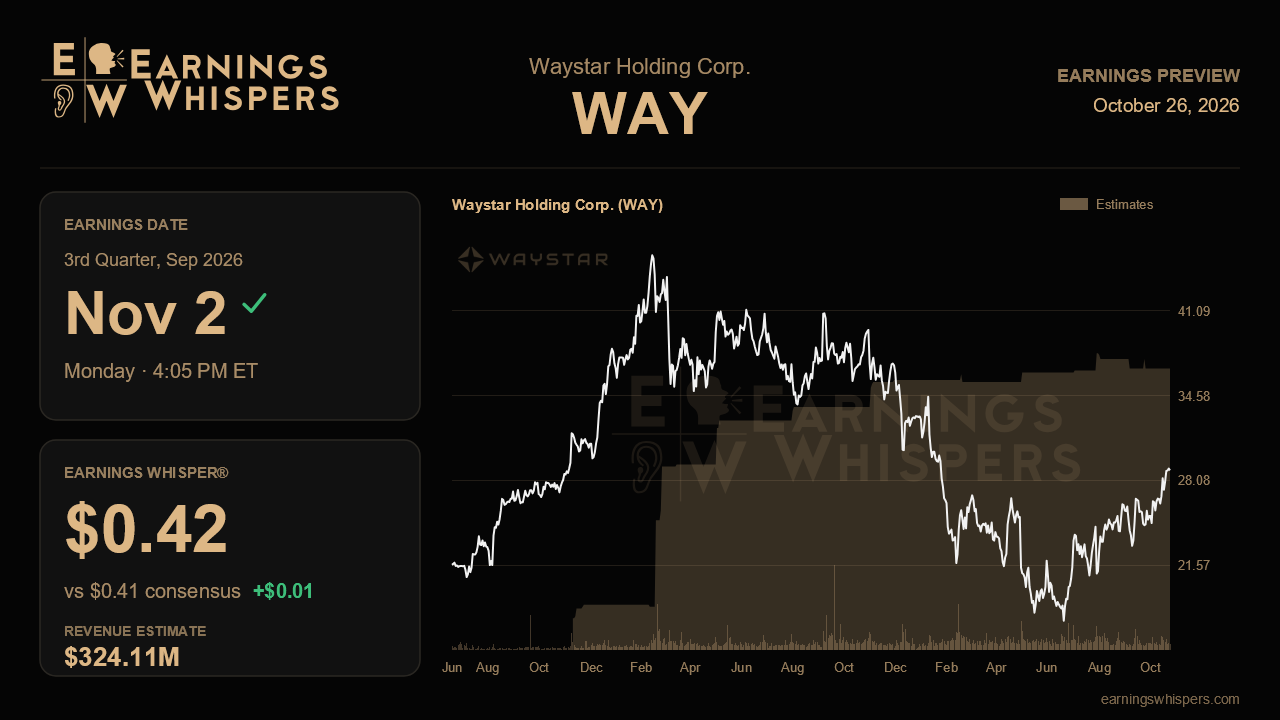
Waystar heads into its third-quarter report with a stock that has run well ahead of its fundamentals' most recent trajectory. Shares have climbed more than 34% since the last report, while the S&P 500 gained about 3%. That rally came even though the company's net revenue retention fell for a fourth straight quarter and organic growth cooled noticeably. The question for this report is whether the market was right to look past that deceleration, or whether it simply priced in a recovery that has not yet arrived.
The Street is looking for non-GAAP earnings of $0.41 per share on revenue of about $324.1 million, which would be roughly 20.6% revenue growth from the year-ago $268.7 million. That headline growth rate flatters the underlying business. Last quarter, organic growth was just 7%, or about 10% on a normalized basis, so much of the reported expansion reflects acquired revenue rather than core momentum. The earnings bar is more demanding than it first appears. Waystar earned $0.32 in the second quarter and $0.32 in the same quarter a year ago, so consensus implies a sizable step up on only modestly higher revenue. The Earnings Whisper of $0.42 sits a penny above consensus, a small difference but one that suggests the informal bar leans slightly higher.
Management's full-year outlook frames how much room exists. Waystar nudged its 2026 range to $1.61 to $1.70 per share on revenue of $1.276 billion to $1.294 billion, and lifted adjusted EBITDA guidance to a $540 million midpoint. Consensus of $1.67 sits in the upper half of the earnings range, while the $1.28 billion revenue estimate sits in the lower half. That split tells the story: analysts trust Waystar's cost discipline more than its top line. Second-quarter adjusted EBITDA margin ran at 43%, ahead of the 42% full-year target, and another quarter at that level would support the earnings view even if revenue merely meets expectations. The company has beaten nine quarters in a row, but its raises have been incremental, so a tenth beat accompanied by only a token raise may not be enough for a stock priced this richly.
The operational evidence matters more than the headline numbers. Net revenue retention slid from 113% to 108%, now at the bottom of the company's historical 108% to 110% band, as tailwinds from elevated patient utilization and earlier industry disruption faded. Volume-based revenue grew only 3% last quarter as utilization drifted back toward its long-term 1% to 2% pace. If retention holds at 108% or ticks up, it would validate management's argument that the slowdown is a comparison issue rather than a demand problem. Another step below the range would challenge that narrative directly, especially with coverage pressure from ACA exchange roll-offs and Medicaid declines still in the background.
On the offense side, management pointed to a fourth consecutive quarter with a double-digit count of deals above $1 million in annual contract value, more than $6 million in cross-sell bookings for iodine capabilities, and early traction for new AI products, including next-generation anomaly detection and an automated payer recoupment tool. Continued growth in clients generating over $100,000 annually, which reached 1,453 last quarter, would show that these bookings are converting into larger relationships. Free cash flow is also worth watching after conversion fell to 47% on tax timing while capitalized software roughly doubled. A rebound would ease worries that AI spending is eating into cash generation, and the first report under a new CFO will be judged on how clearly that tradeoff is explained.
Sentiment has softened from 58.7% bearish to 52.8% bearish, so skepticism is fading but has not disappeared. The stock trades well above its 200-day moving average near $24 and sits within about 1.5% of its post-earnings high of $29.25, effectively testing a breakout. That leaves little cushion. For the rally to hold, Waystar needs to show that retention and organic growth have stabilized, not just that margins can carry another quarter.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-22 | |
| Oct-14 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Aug-26 | |
| Aug-25 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-21 | |
| Jul-15 |
