Waystar Beats On Record Bookings, But A Soft Implied Q4 Reveals A Widening Gap Between Demand And Revenue
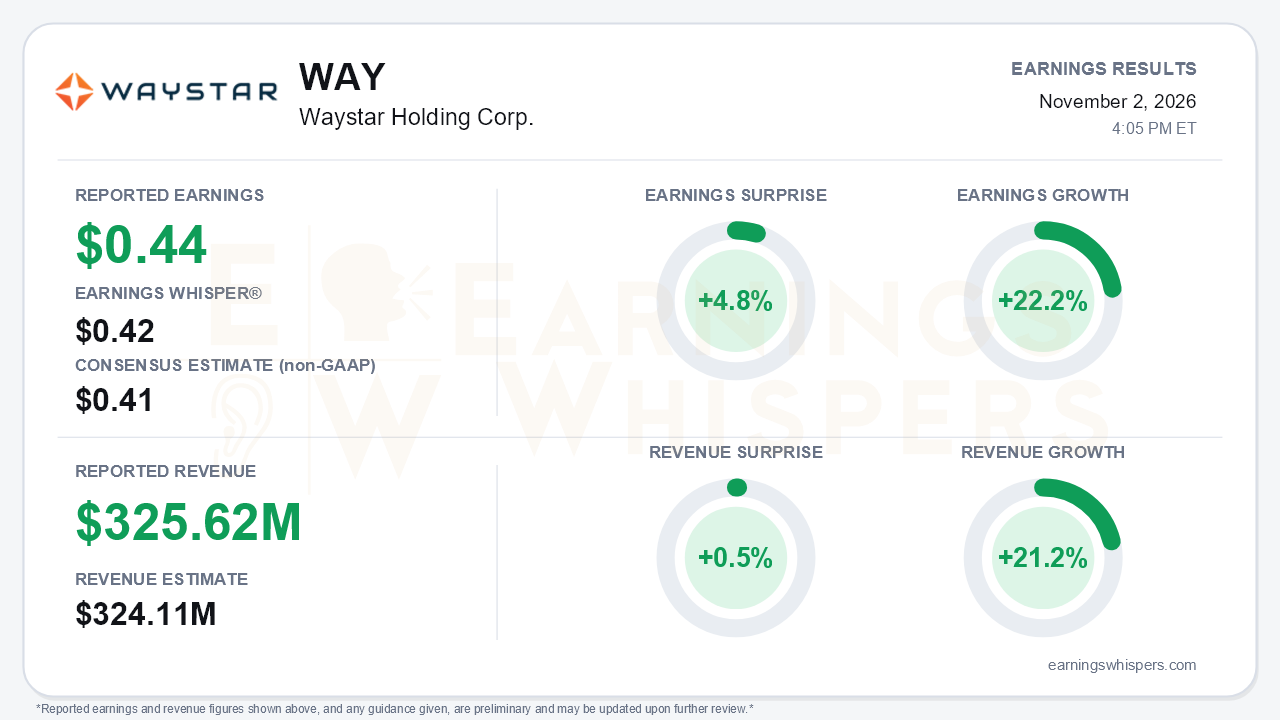
Waystar Holding Corp. (NASDAQ: WAY) delivered a clean third-quarter beat. Non-GAAP earnings were $0.44 per share, ahead of the $0.41 consensus and the $0.42 Earnings Whisper number, a 4.8% surprise. Earnings grew 22.2% year over year. Revenue of $325.62 million topped the $324.11 million consensus by 0.5% and grew 21.2%. The headline is not the story, though. The central tension is a company reporting the strongest demand signals in its history while simultaneously trimming its revenue outlook and guiding to a sequential decline in the fourth quarter. Bookings are outrunning recognized revenue, and investors now have to decide how long that gap persists.
The quality of the beat holds up better at the operating level than at the GAAP line. Organic growth improved to about 10% from roughly 7% in the second quarter. Subscription revenue rose 34% to $180.7 million, or 12% organically. Volume-based revenue growth improved to 8% from 3% in Q2. Adjusted EBITDA of $139.3 million produced a 42.8% margin, up from 42.0% a year ago, and unlevered free cash flow rose to $114.8 million from $95.7 million. GAAP results tell a less flattering story:
- Diluted GAAP EPS slipped to $0.16 from $0.17.
- Net income margin compressed to 9.5% from 11.4%.
- Stock-based compensation more than doubled to $24.4 million.
- Acquisition and integration costs rose to $9.6 million, and G&A jumped 59%.
- Diluted share count grew about 8%, diluting per-share results.
The non-GAAP growth is real, but so is the widening spread between adjusted and reported profitability.
The call's most compelling evidence was on demand, and some of it came from newly disclosed metrics:
- Year-to-date bookings rose 25%.
- Large-deal bookings increased 30%.
- Large-client implementation backlog climbed 50% year over year.
- Waystar signed the largest client win in its history, an East Coast health system with roughly $7 billion in net patient revenue that is consolidating onto the full platform and replacing more than 20 vendors.
- Iodine bookings ran 74% above year-to-date plan.
- Cross-sell of Iodine into existing Waystar clients reached about $9 million in Q3, up from about $6 million in Q2.
- AI-driven Altitude products rose to roughly 43% of bookings from about 40%.
Management also launched autonomous claim resubmission and expanded a physical therapy channel partnership.
The problem is conversion. The full-year revenue range narrowed to $1.277 billion to $1.287 billion, lowering the midpoint to $1.282 billion from $1.285 billion and cutting the high end by $7 million. That implies fourth-quarter revenue of about $323 million, below Q3's $326 million and only about 6% reported growth. Management put normalized Q4 growth closer to 10% and cited roughly four points of headwinds from three sources:
- A faster-than-expected print-to-digital shift in patient statements.
- Performance-based pricing for pre-bill anomaly detection, which delays Iodine revenue recognition. Iodine's 2026 revenue contribution is now expected below plan.
- Difficult comparisons against unusually fast implementations a year ago.
Large platform deals are also ramping over a longer 12-to-18-month window than originally assumed. Net revenue retention held at 108%, still down from 112% in Q4 of fiscal 2025 and 111% in Q1. Bears have legitimate ammunition here: retention has not recovered, and the near-term revenue curve is flattening.
On the other side of the ledger, adjusted EBITDA guidance rose for a second straight quarter to $543 million to $549 million, with full-year margin now near 42.5%. Net leverage fell to 2.2x from 2.5x in Q2, and share repurchases rose to about $21 million. Implied Q4 EBITDA of roughly $135 million is down sequentially, however, breaking a multi-year pattern of fourth-quarter increases. Management deferred its fiscal 2027 outlook, and a CFO transition to Alpana Wegner, alongside a new Chief Product and Technology Officer from Salesforce, adds a layer of near-term uncertainty.
The market setup is more complicated than the modest surprise implies. Shares entered the report at $28.00, up 30.4% from the $21.47 open after the July report. The stock was 17.1% above its 200-day moving average and only 4.3% below its inter-earnings high of $29.25, set October 22. It had rallied 39% off its $20.14 low, which came the day after the last report. Earnings Whispers trend signals were uniformly positive heading in. Investor sentiment, however, remained firmly negative at -0.56, only marginally better than -0.59 after the prior report. That combination of a stock pricing in recovery while sentiment stays skeptical leaves little cushion for a guide that softens the near-term revenue trajectory.
The bottom line is that Waystar's demand story strengthened materially this quarter, with record bookings, a historic client win, and Iodine traction that skeptics were not positioned for. Those wins are taking longer to show up as revenue, as the soft implied Q4, the trimmed revenue midpoint, stalled 108% retention, and the deferred 2027 view all show. With the stock near its quarterly high after a 30% run, the burden now shifts to proving that bookings and backlog convert into reaccelerating revenue in 2027.
Read our earnings preview for Waystar Holding Corp.: https://www.earningswhispers.com/article/WAY/21449
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 5 hours | |
| Oct-26 | |
| Oct-22 | |
| Oct-14 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Sep-15 | |
| Aug-26 | |
| Aug-25 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 |
