Ball's Startup-Cost Quarter Tests Whether Its 10% Earnings Growth Framework Holds
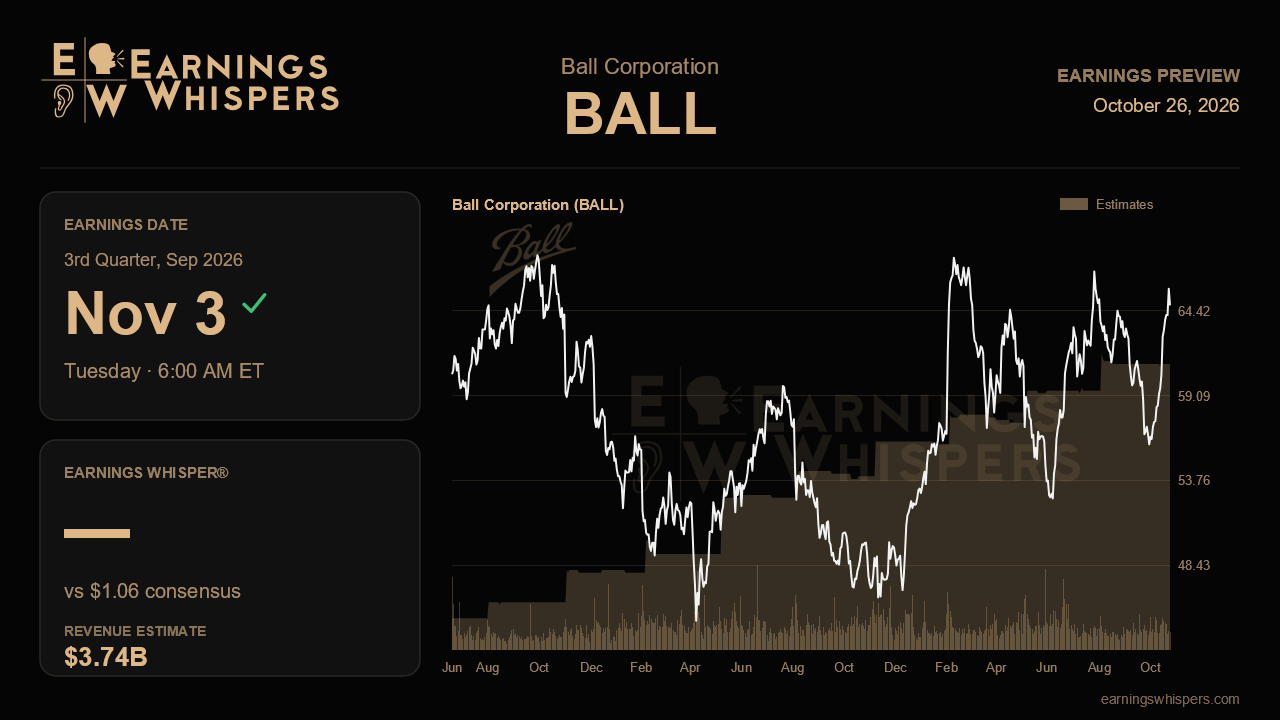
Ball Corporation heads into its third-quarter report with a story that sounds good on paper but faces its most awkward stretch on the calendar. Management spent the last call highlighting a broad volume re-acceleration and reaffirming its framework for at least 10% comparable EPS growth this year. It also said that most of the roughly $35 million in Millersburg and related startup costs would land in the second half, with the bulk falling in the third quarter. This is the quarter where those costs show up, and investors will learn whether the rest of the business can absorb them.
The Street has clearly factored in the drag. Consensus calls for EPS of $1.06, up only about 3.9% from $1.02 a year ago, a sharp slowdown from the 14.4% comparable EPS growth Ball posted in the second quarter. Revenue is expected to reach $3.74 billion, up a much stronger 10.7%. That gap matters. Ball passes elevated aluminum and Midwest premium costs through to customers, which inflates sales without adding much profit. The headline revenue figure will flatter the quarter, so segment operating earnings and volumes are the better guide to how the business is actually doing. A modest third quarter also puts more weight on the fourth quarter to deliver the full-year 10%-plus target. Any wobble in that reaffirmation would matter more than a penny or two on the quarter itself.
North and Central America is the region to scrutinize. Segment earnings slipped 2.4% last quarter as the system ran notably tight, with labor, freight and scheduling friction on top of about $5 million in startup costs. Volume growth sat at the low end of the 1% to 3% range because Ball simply lacked capacity. Commercial can production at Millersburg began in July. The useful evidence now is whether that line is ramping cleanly enough to ease the strain, or whether startup costs come in heavier than planned. Results that show the region holding roughly steady despite the cost burden would support the view that 2027 is set up for a meaningful rebound. A deeper earnings decline paired with ongoing operational friction would undercut it. Demand mix matters too. Beer remains soft, and growth has leaned on energy drinks and non-alcoholic beverages. Persistent aluminum inflation could test consumer appetite even though Ball itself is protected by pass-through.
Outside the U.S., the question is durability. South America swung from a mid-single-digit volume decline in the first quarter to mid-teens growth in the second, helped by World Cup and America 250 demand, and segment earnings jumped 64%. Management nudged its full-year outlook for the region to the low-to-middle part of the 4% to 6% range. Holding that guide once event-driven demand fades would show the rebound was more than a one-off. EMEA, guided above its 3% to 5% range with help from the BenePak acquisition, needs to keep growing steadily to offset the North American cost drag. Confirmation of free cash flow above $900 million and roughly $800 million in buybacks and dividends would round out the picture.
The market has leaned positive. Shares are up 4.7% since the last report while the S&P 500 was roughly flat. At $64.76, the stock sits comfortably above its 200-day moving average and about 2% below its post-earnings high of $66.12, close enough that a clean report could push it through. Sentiment has cooled, however. Bullish readings fell to 12.8% from 23.6% ahead of the prior report, suggesting more caution about the cost-heavy quarter even as the shares have firmed.
The central issue is whether Ball can get through peak startup spending without cracking its full-year framework. If volumes keep growing, North American earnings stabilize and management again commits to 10%-plus EPS growth, the soft quarterly figure will look like planned investment. If the cost drag spills beyond expectations or the region's capacity strain worsens, the confident tone from last quarter will be harder to sustain.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-19 | |
| Oct-06 | |
| Sep-11 | |
| Sep-11 | |
| Sep-09 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Jul-29 | |
| Jul-06 | |
| Jun-17 |
