Cinemark Seeks A Second Straight $1 Billion Quarter As Crowded Summer Slate Tests Capacity
Cinemark crossed a symbolic threshold last quarter, posting its first-ever billion-dollar revenue quarter alongside record adjusted EBITDA of $294 million. The question heading into its third-quarter report, due before the open on November 3, is whether that was a peak or a new baseline. Management spent much of its last call celebrating a well-spaced first-half film slate, then warned that the back half would bring more blockbusters crammed into the same weekends. That warning sets up the core test: can Cinemark keep converting a hot box office into profit when its auditoriums, not demand, become the limiting factor?
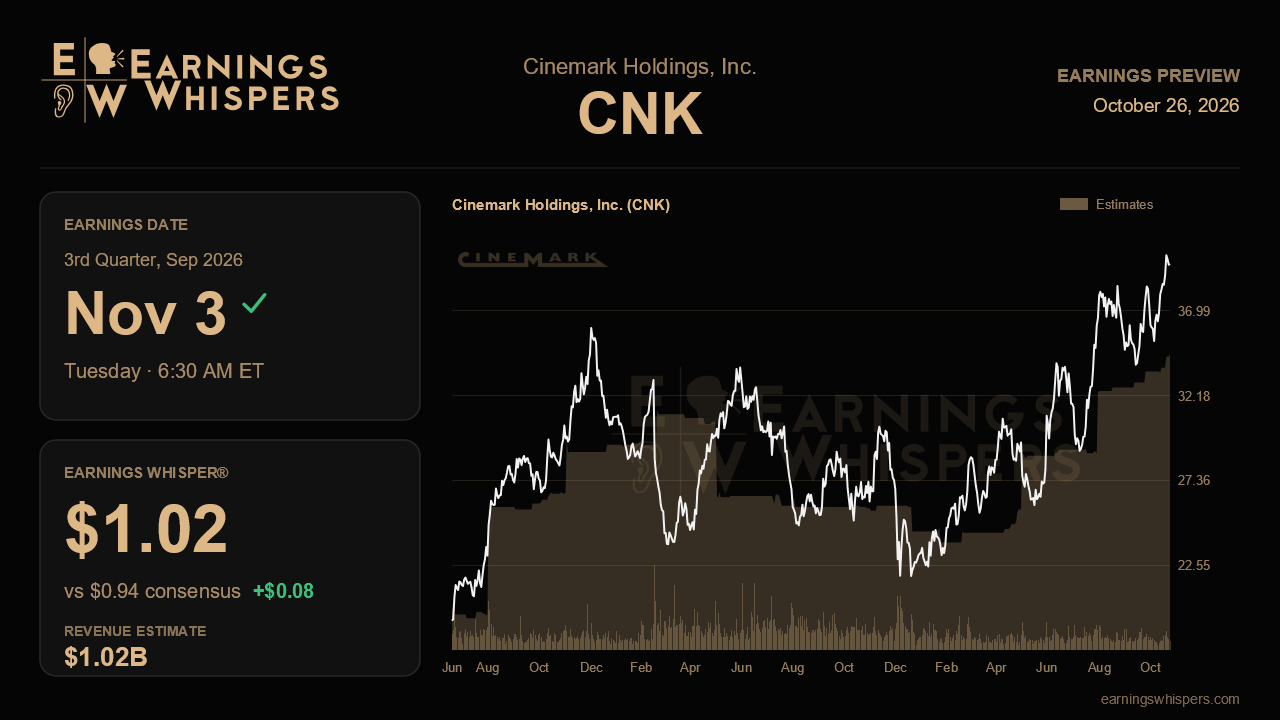
Wall Street expects earnings of $0.94 per share on revenue of about $1.02 billion. That would mark a second consecutive quarter above $1 billion and a 19% revenue gain from the $857.5 million posted a year ago, while earnings would more than double from $0.40. The growth math reflects operating leverage at work. Theaters carry heavy fixed costs in rent, staffing and utilities, so each incremental ticket and popcorn sale drops disproportionately to the bottom line. The Earnings Whisper of $1.02 sits meaningfully above consensus, suggesting the more engaged corner of the market believes analysts are still underestimating that leverage. Cinemark offers no formal numerical guidance, so the Street is working from management's clearly more confident tone rather than a stated range.
The swing factor is margin. A year ago, the third quarter produced $178 million of adjusted EBITDA at a 20.7% margin, and free cash flow was just $38 million. Last quarter's 27.1% margin and roughly $300 million of free cash flow show how far the model has come, but some sequential cooling is normal after the summer kickoff. A margin holding comfortably in the mid-20s would validate management's argument that structural improvements, not just a lucky slate, are driving results. Those improvements include the 45-day theatrical window studios began honoring in the second quarter, a roughly 20% jump in moviegoing frequency among under-25 audiences, record merchandise sales of 25 million units, and a premium footprint of about 350 large-format screens and 660 D-Box auditoriums that lifts per-ticket revenue. Strong per-capita spending on concessions and merchandise would be the clearest sign these levers are durable.
The risks management flagged are equally concrete. Film bunching could cap attendance on the biggest weekends and erode the market share gains Cinemark enjoyed in the first half, a point management itself conceded remains uncertain until box office normalizes. Electricity costs in data-center-heavy Texas markets have climbed for several quarters running, and mandated wage increases in Latin America continue to outpace inflation. Latin America is worth particular attention after rebounding from a disappointing first quarter to record profit and an all-time high margin; repeating anything close to that would ease concerns that the region's results swing wildly with film resonance. Commentary on Spider-Man presales, The Odyssey and the run of low-budget creator-led hits will shape how investors think about the holiday quarter.
The stock has rewarded the story, rising 8.7% since the last report against a 3.3% gain for the S&P 500. At $39.66 it trades well above its 200-day moving average of $30.87 and within about 2% of its post-earnings high of $40.53, effectively testing a breakout. Its entire trading range since the last report sits above most of the prior quarter's range. Yet sentiment has cooled, with bullish readings slipping to 39.7% from 46.6%, hinting that some investors worry the good news is priced in.
Ultimately, this report hinges on whether Cinemark can show that last quarter's record profitability survives a less forgiving release calendar. Revenue near $1 billion with margins that hold their gains would confirm a structurally stronger business; a sharp margin retreat blamed on capacity and costs would suggest the first half flattered the model.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-26 | |
| Oct-25 | |
| Oct-25 | |
| Oct-22 | |
| Oct-15 | |
| Oct-08 | |
| Oct-08 | |
| Sep-30 | |
| Sep-30 | |
| Sep-23 | |
| Sep-23 | |
| Sep-21 | |
| Sep-21 | |
| Sep-16 | |
| Sep-04 |
